How Hotel Owners Build a Single Source of Truth for Performance
Learn how Saudi hotel owners can build a single source of truth for property performance. Cut reporting time 70–90%, track RevPAR, ADR & occupancy in real time....
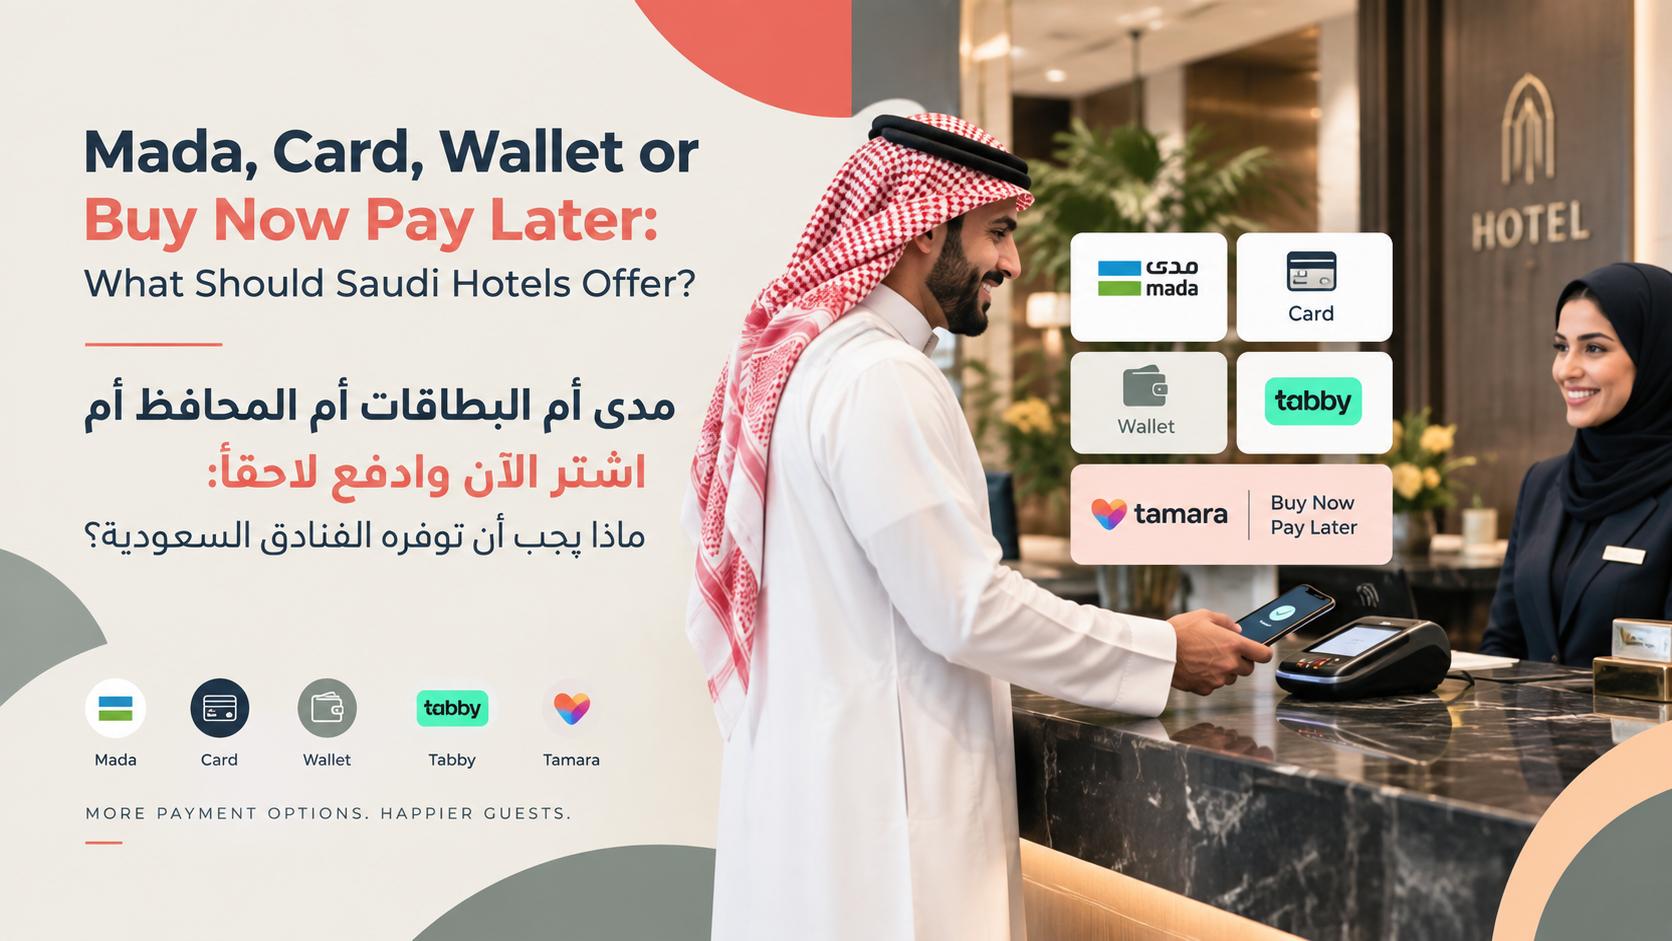
A guest finds your hotel online, loves the photos, checks the price, and clicks "Book Now." Then they reach the payment page — and their preferred payment method isn't there. No Mada. No Apple Pay. No Tabby or Tamara. Just a form asking for an international credit card. In Saudi Arabia, that moment is where a shocking number of direct bookings quietly die.
Choosing the right payment methods for Saudi hotels is no longer a back-office technical detail — it is a revenue decision as important as your pricing strategy. The Kingdom has one of the fastest-moving digital payment markets in the world: Mada dominates domestic spending, digital wallets like Apple Pay and stc pay have exploded, and Buy Now Pay Later (BNPL) services have become a normal way for Saudi travelers to book trips. In this guide, we break down each payment option — Mada, credit and debit cards, digital wallets, and BNPL — with real market data, guest-behavior insights, use cases for different hotel types, a side-by-side comparison table, and a clear recommendation for what your property should offer to maximize direct bookings and protect your margins.
Quick Answer (for readers in a hurry): Saudi hotels should offer a layered payment mix: Mada for domestic guests (the majority of local card transactions), Visa/Mastercard for international and corporate travelers, Apple Pay and stc pay for mobile bookers, and at least one BNPL option (Tabby or Tamara) to capture younger domestic leisure travelers and increase average booking value. Hotels that expand from cards-only to this full mix typically see measurably higher direct booking conversion and larger average transaction sizes — often enough to offset the fees within the first season.
Cart abandonment research across e-commerce consistently shows the same pattern: when shoppers do not see their preferred payment method at checkout, a large share simply leave. Hospitality is no exception. A guest who abandons your booking engine does not disappear — they usually complete the same booking on an OTA that does support their payment method, and you pay 15–25% commission for the privilege.
This is why hotel payment gateway strategy in Saudi Arabia deserves owner-level attention. Every payment method you add or omit changes three numbers at once:
The Saudi context makes this even sharper. Under the Financial Sector Development Program of Vision 2030, the Kingdom set out to make the majority of transactions electronic — and it succeeded ahead of schedule, with electronic payments now representing the clear majority of retail transactions. Saudi guests are not "moving toward" digital payments; they have already arrived. The question is whether your hotel's checkout has arrived with them.
Mada is Saudi Arabia's national payment network, operated under the Saudi Central Bank (SAMA). Nearly every Saudi resident with a bank account holds a Mada card, and Mada consistently accounts for the overwhelming majority of domestic card transactions in the Kingdom. For many Saudi guests — especially domestic leisure travelers and families — Mada is not one option among several. It is the way they pay.
Note: Mada acceptance is also a compliance and expectation matter at the front desk, not just online. Ensure your on-property POS terminals support Mada and Mada Atheer (contactless) — guests paying for restaurant bills, spa services, and incidentals expect to tap a Mada card or phone without friction.
Visa, Mastercard, and American Express remain the backbone of international travel payments. With Saudi Arabia targeting 150 million annual visits under Vision 2030 — including rapidly growing international leisure tourism to Riyadh, Jeddah, AlUla, and the Red Sea — international card acceptance is mandatory for any hotel that wants inbound business.
International card fees are meaningfully higher than Mada, chargebacks are a real operational cost (especially for no-show disputes), and cross-border cards can trigger higher decline rates. The fix is not to avoid cards — it is to route intelligently: let domestic debit traffic flow through Mada rails and reserve international schemes for the guests who genuinely need them. A modern Saudi-licensed payment gateway does this routing automatically.
Saudi Arabia is one of the most mobile-first consumer markets on earth, with smartphone penetration near universal and a young population that lives on their phones. Apple Pay adoption in the Kingdom is among the highest globally as a share of contactless payments, and local wallets like stc pay (now part of STC Bank) and urpay have millions of active users.
"In Saudi hospitality, the payment page is the new front desk. A guest who taps Apple Pay in eight seconds remembers a smooth arrival before they ever arrive. A guest who fights a clunky card form remembers the friction — or worse, finishes the booking on an OTA and costs you 20% commission."
Buy Now Pay Later in Saudi Arabia has grown from a fashion-retail novelty into a mainstream payment behavior, led by Tabby and Tamara — both now major regional fintechs regulated by SAMA, with millions of Saudi users. Travel is one of BNPL's fastest-growing categories: splitting a hotel stay into interest-free installments fits exactly how younger Saudi travelers budget for Riyadh Season weekends, Eid family trips, and staycations.
BNPL merchant fees are the highest of the four options — typically several percent per transaction. That is why the right strategy is selective: enable BNPL on your direct booking engine where it displaces a 15–25% OTA commission (an easy win), and measure whether the uplift in conversion and booking value justifies the fee for your specific guest mix. For most leisure-focused Saudi hotels, it does.
| Factor | Mada | Credit/Debit Cards | Digital Wallets | BNPL (Tabby/Tamara) |
|---|---|---|---|---|
| Primary audience | Domestic guests, families | International & corporate | Mobile-first bookers, under 40 | Young domestic leisure travelers |
| Processing cost | Lowest | Medium–high | Follows underlying card/Mada | Highest |
| Conversion impact | Essential for domestic trust | Baseline expectation | Strong lift on mobile | Lifts conversion + booking value |
| Cash flow | Fast settlement | 1–3 day settlement | Same as underlying rail | Full amount paid upfront by provider |
| Chargeback/risk | Low | Highest (esp. no-show disputes) | Low (tokenized, authenticated) | Provider absorbs installment risk |
| Best used for | All domestic transactions, POS | Guarantees, deposits, inbound guests | Mobile booking engine, front desk tap | Direct leisure bookings, packages |
| Verdict | Mandatory | Mandatory | Strongly recommended | Recommended for leisure hotels |
Your guest mix is heavily international, arriving from dozens of countries. Priority: broad international card acceptance with high authorization rates, plus Mada for the large domestic Umrah segment. Wallets help for domestic mobile bookings around Ramadan, when demand spikes and guests book on their phones days before arrival. BNPL is lower priority here but increasingly relevant for Saudi families booking Ramadan packages months ahead.
Corporate cards and virtual cards from travel management companies dominate midweek. Weekend leisure demand from Riyadh Season and events is where wallets and BNPL earn their place — the Saudi couple booking a Friday staycation on a phone behaves completely differently from the Tuesday corporate traveler. A layered checkout serves both without compromise.
Domestic family leisure is your core. This is the strongest BNPL case in Saudi hospitality: family suites and multi-night packages carry higher totals that installments make psychologically easy. Mada and Apple Pay handle the on-property spend — beach club, dining, water sports — where tap-to-pay speed keeps queues short and ancillary revenue flowing.
High-ADR international leisure guests expect frictionless premium payment: Apple Pay, seamless card checkout in multiple currencies, and flawless pre-authorization handling. Domestically, affluent young Saudi travelers — a key AlUla segment — are strong wallet and BNPL users even at premium price points, because BNPL for them is a budgeting tool, not a financing necessity.
Pro Tip: Don't guess which methods your guests want — measure it. Track payment-method share, checkout abandonment point, and average booking value per method in one dashboard. If you see high mobile traffic but low mobile conversion, missing wallets are usually the culprit. If domestic direct bookings lag your OTA share, missing Mada or BNPL is often why.
The payment landscape your hotel builds today should be ready for where the Kingdom is heading:
At minimum: Mada for domestic guests, Visa and Mastercard for international and corporate travelers, and Apple Pay for mobile bookings. Leisure-focused hotels should add at least one BNPL provider (Tabby or Tamara) to capture younger domestic travelers and increase average booking value.
Yes. Mada accounts for the overwhelming majority of domestic card transactions in Saudi Arabia, carries lower processing fees than international schemes, and is the payment method many domestic guests trust most. A checkout without Mada pushes local direct bookings toward OTAs.
For leisure-focused Saudi hotels, usually yes. BNPL increases average booking value and conversion among under-35 travelers, and the hotel receives the full payment upfront while the provider carries installment risk. The higher merchant fee is typically justified when BNPL displaces a 15–25% OTA commission on a direct booking.
Both are SAMA-licensed, widely adopted, and travel-friendly. Compare merchant fees for your booking volume, settlement terms, integration support with your booking engine, and the marketing exposure each app offers. Many merchants start with one, measure uplift for a season, and add the second if the segment responds.
On mobile, yes — measurably. Wallets remove the highest-friction step of mobile checkout (typing card details), and Saudi Arabia has some of the world's highest contactless and Apple Pay adoption. Hotels with mobile-heavy traffic typically see conversion improvements immediately after enabling wallets.
As a general pattern: Mada is the cheapest, international cards cost more (with added chargeback exposure), and BNPL carries the highest merchant fee but pays the hotel upfront and lifts booking value. The right lens is net revenue per booking after fees and OTA commissions — not the fee percentage alone.
Yes — payment friction is one of the main hidden reasons guests finish bookings on OTAs after finding a hotel directly. Matching the payment options guests expect (Mada, wallets, BNPL) removes that reason, making your direct channel genuinely competitive with OTA checkouts.
Track four metrics per method: share of bookings, checkout abandonment rate, average booking value, and total cost (fees + chargebacks). Reviewing these monthly in a unified performance dashboard shows exactly which methods earn their fees and which segments remain underserved.
The question is not "Mada, card, wallet, or Buy Now Pay Later?" — for a Saudi hotel in 2026, the answer is a deliberate combination of all four, weighted to your guest mix. Mada is the non-negotiable foundation for domestic guests. International cards are mandatory for inbound and corporate business. Digital wallets are the conversion engine of mobile booking. And BNPL is the growth lever for young domestic leisure travelers — the fastest-growing segment in the Kingdom.
Hotels that treat payments as a revenue strategy — measuring method mix, abandonment, booking value, and fee cost like any other KPI — consistently convert more direct bookings, reduce OTA dependency, and capture more of the extraordinary demand Vision 2030 is creating. The payment page is where your marketing spend either becomes revenue or evaporates. Make it work as hard as the rest of your hotel.
Fandaqah unifies your booking, channel, and payment performance into one real-time dashboard — so you can see conversion, booking value, and cost per payment method across your entire property or portfolio, and decide with facts instead of guesses.
Tags: payment methods for Saudi hotels, Mada for hotels, hotel payment gateway Saudi Arabia, Buy Now Pay Later hotels, Tabby hotel booking, Tamara travel payments, Apple Pay hotel booking Saudi Arabia, stc pay hotels, hotel direct booking payments, digital wallets Saudi hospitality, BNPL for hotel bookings, reduce OTA commission direct bookings, hotel checkout conversion optimization, best payment gateway for hotels in Saudi Arabia, Mada vs credit card fees for hotels, hotel payment analytics, Vision 2030 cashless payments, Saudi hotel booking engine payments, hotel revenue management, Fandaqah
Learn how Saudi hotel owners can build a single source of truth for property performance. Cut reporting time 70–90%, track RevPAR, ADR & occupancy in real time....
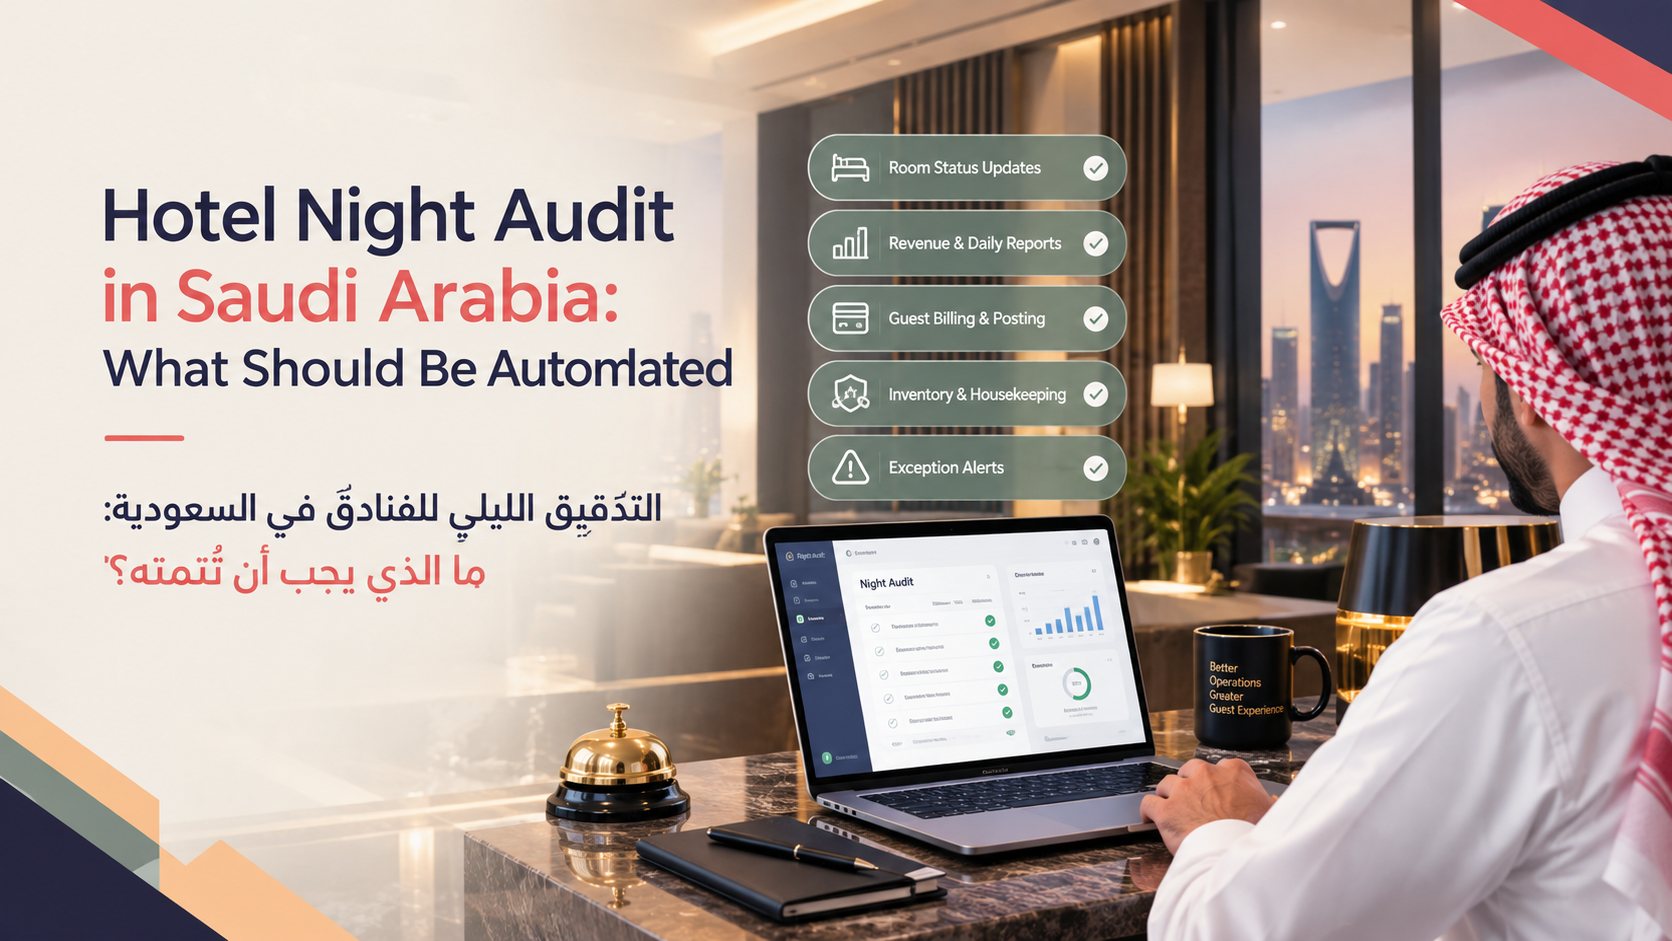
Complete guide to automating hotel night audit in Saudi Arabia: room & tax posting, no-shows, ZATCA Fatoora e-invoicing, payment reconciliation & continuous close....
Discover proven strategies for Saudi hotels to protect revenue in low occupancy: dynamic pricing, RevPAR & TRevPAR focus, direct bookings, ancillary income, staycations & Vision 2030 insights....
A hotel management system (PMS) cuts queues on Saudi National Day 2026 with pre-check-in, auto room assignment, live housekeeping, channel sync and instant e-invoices. Shorter waits, zero overbookings...
Connected hotel technology creates a seamless guest journey for Saudi National Day 2026. Link PMS, booking engine, POS, mobile keys & more—enter data once, zero friction from search to review....
12 proven strategies to increase direct hotel bookings in Saudi Arabia. Grow commission-free revenue with booking engines, WhatsApp, Google Free Booking Links & more in 2026....
Learn proven strategies to reduce OTA commissions, boost direct bookings, and increase hotel profits in Saudi Arabia. Practical tips for Riyadh, Jeddah, Makkah & more in 2026....
How Fandaqah integrates HyperPay, mada, Visa, Apple Pay, Tamara and Tabby for secure direct hotel payments in Saudi Arabia — with ZATCA invoicing built in....
Practical guide to MOT-compliant hotel PMS in Saudi Arabia. Cover NTMP reporting, guest registration, Baladi licences, ZATCA invoicing and how Fandaqah helps....
The 10 essential daily hotel reports every general manager should review before 10 a.m.: flash, night audit, ADR & RevPAR, pace, room status, and more — with red flags to watch....
Discover how a hotel PMS cuts front-desk check-in and billing errors with live room status, channel sync, auto POS posting, and ZATCA e-invoicing for Saudi properties....
How hotel sales managers in Saudi Arabia win corporate rate agreements and MICE contracts. Practical RFP tips, smart pricing, account targeting and sales KPIs....
How hotel IT managers in Saudi Arabia select secure, ZATCA Phase 2-compliant PMS systems. Checklist for e-invoicing, Fatoora integration, PDPL & guest data protection....
Discover the hotel food and beverage manager’s real duties, key KPIs (food cost %, average check, waste), and how POS-PMS integration cuts costs and raises profit in Saudi hotels....
Learn what a hotel revenue manager does daily, the KPIs that matter (RevPAR, ADR, GOPPAR), and 8 practical ways to use a PMS to raise profits in the Saudi market....
Design a frictionless guest journey in 7 stages. Map friction points, apply 5 principles, cut check-in time, and connect bookings to billing with one PMS. Practical guide for Saudi hotels and serviced...
Turn PMS data into personalized stays for repeat guests. 5-step framework: unify profiles, segment, tag preferences, activate at 3 moments, and measure results. Built for Saudi hotels & serviced apart...
Is your hotel battling rising chargebacks? Discover why chargebacks are eating into hotel revenue and learn essential strategies to prevent, dispute, and protect your bottom line from fraudulent claim...
By 2030, hotel payment landscapes will be unrecognizable. Explore how biometrics, digital wallets, and blockchain are set to redefine the guest experience, moving beyond traditional cards and cash for...
Prevent payment collection errors and streamline your hotel's end-of-day operations. Discover expert strategies, technology solutions, and best practices to ensure accurate financial reconciliation an...
Unlock hotel success with key performance indicators. Learn the essential metrics like RevPAR, ADR, Occupancy, GOPPAR, and more that every hotel manager needs to master for profitability and growth....
Unlock the secrets to boosting your hotel's direct bookings. This expert guide provides actionable strategies, from enhancing your online presence to personalizing guest experiences, all without compr...
Unlock the secrets to transforming first-time hotel guests into lifelong advocates. Discover actionable strategies for exceptional service, personalized experiences, and powerful loyalty programs that...
Saudi hotels can reclaim direct bookings from OTAs. Discover expert strategies to enhance guest loyalty, personalize experiences, optimize your online presence, and drive repeat business directly to y...
Discover why hotel guests will increasingly choose WhatsApp over traditional phone calls by 2026. Explore the convenience, efficiency, and personalized communication driving this digital shift in hosp...
Uncover the top reasons guests abandon hotel bookings before payment and learn expert strategies to reduce cart abandonment, boost conversions, and maximize revenue....
Prepare for the future of hospitality in Saudi Arabia. Discover the top 10 trends poised to shape hotel revenue in 2027, from AI integration to sustainable tourism, and learn how to optimize your stra...
Unlock the untapped revenue potential hidden within your hotel rooms. Discover expert strategies, from personalized upsells to smart technology, to maximize profitability and guest satisfaction withou...
Uncover the unique motivations behind Saudi guests' hotel reviews and the cultural nuances that drive virality. Learn how hospitality businesses can leverage these insights for unparalleled guest enga...
Explore the transformative impact of Instagrammable design on Saudi Arabia's burgeoning hospitality sector. Discover how aesthetics, technology, and cultural narratives are driving unprecedented growt...
Explore the future of hospitality in Saudi Arabia. Discover how AI, robotics, and hyper-personalization will transform Saudi hotels by 2030, offering unparalleled luxury and efficiency. ...
Maximize your hotel's profitability. Discover the strategic moments to raise your room rates and crucial times when lowering prices can be a costly mistake. Learn to optimize your pricing strategy fo...
Saudi Arabia's ambitious mega-projects like NEOM, Red Sea Project, and Qiddiya are set to revolutionize global tourism and hotel booking. Discover how these futuristic developments will reshape travel...
Maximize summer hotel revenue in Saudi Arabia with dynamic pricing, family packages, staffing tips & operations best practices. Align with Vision 2030 for higher RevPAR and guest satisfaction....
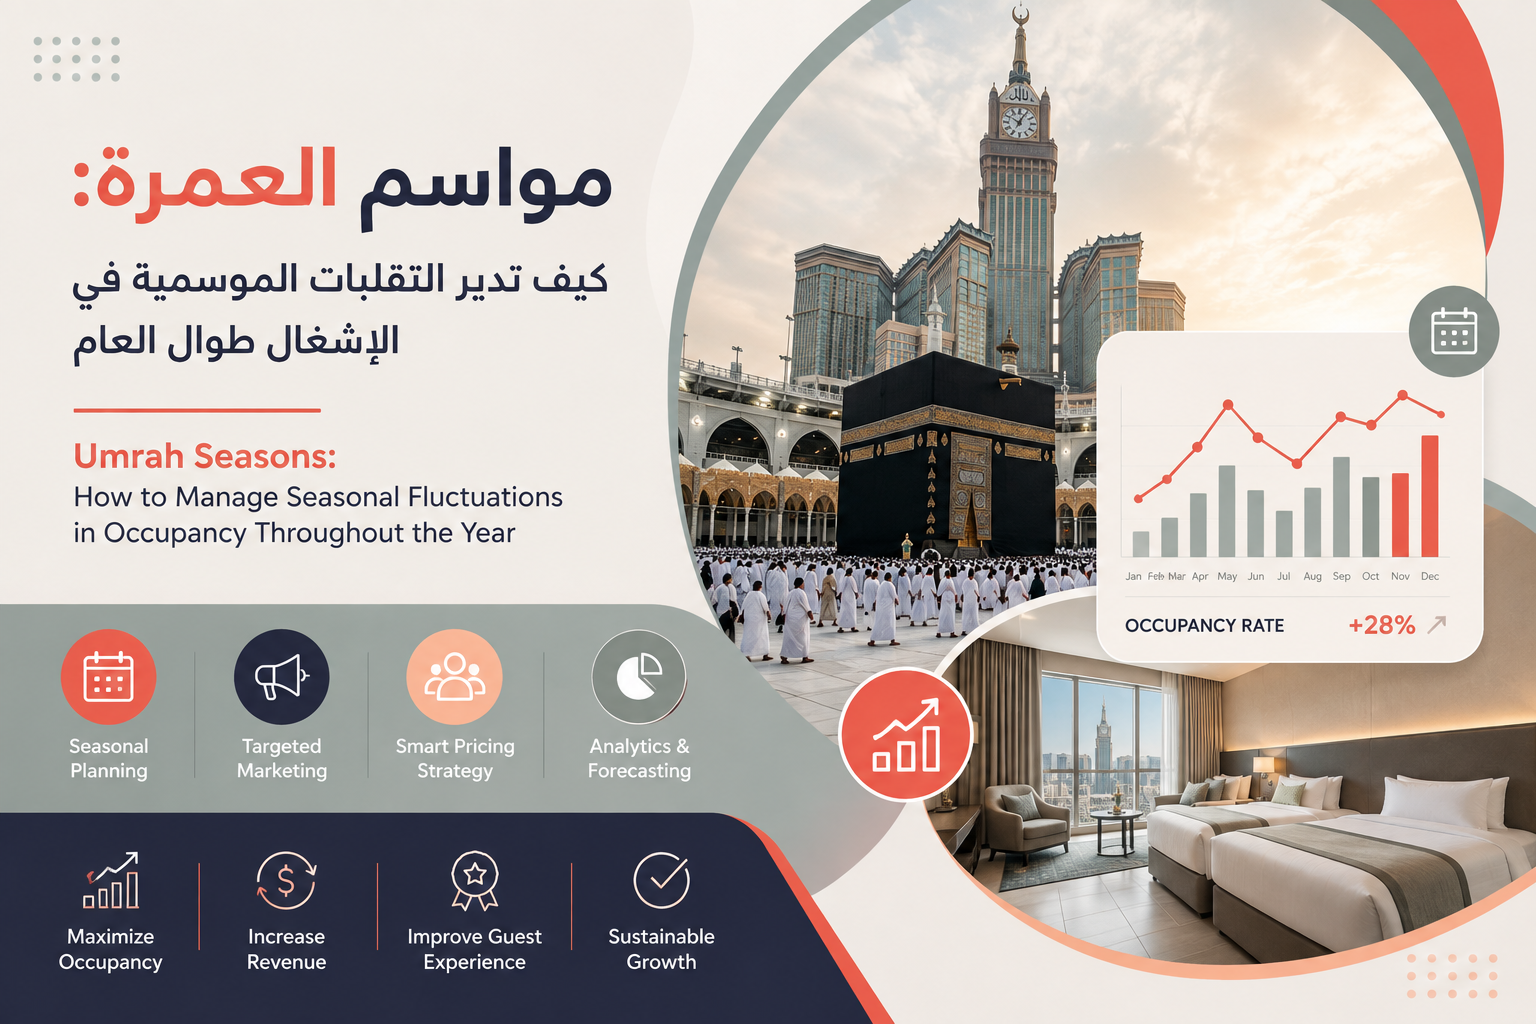
Master Umrah seasonal occupancy with dynamic pricing, packages, loyalty programs & Fandaqah.com. Strategies to boost RevPAR in Ramadan peaks and fill rooms in low seasons....
Unlock the power of guest data to craft unforgettable, personalized hotel experiences. Learn strategies to collect, analyze, and apply insights for enhanced loyalty and revenue. ...
Unlock the power of domestic tourism in Saudi Arabia. Discover expert strategies for hotels to transform local guests into loyal, repeat customers, driving sustainable growth in this dynamic market. ...
Unlock the secrets to converting TikTok views into bookings for Saudi hotels. Discover expert strategies, content types, and measurement techniques to maximize your social media ROI in the Kingdom's d...
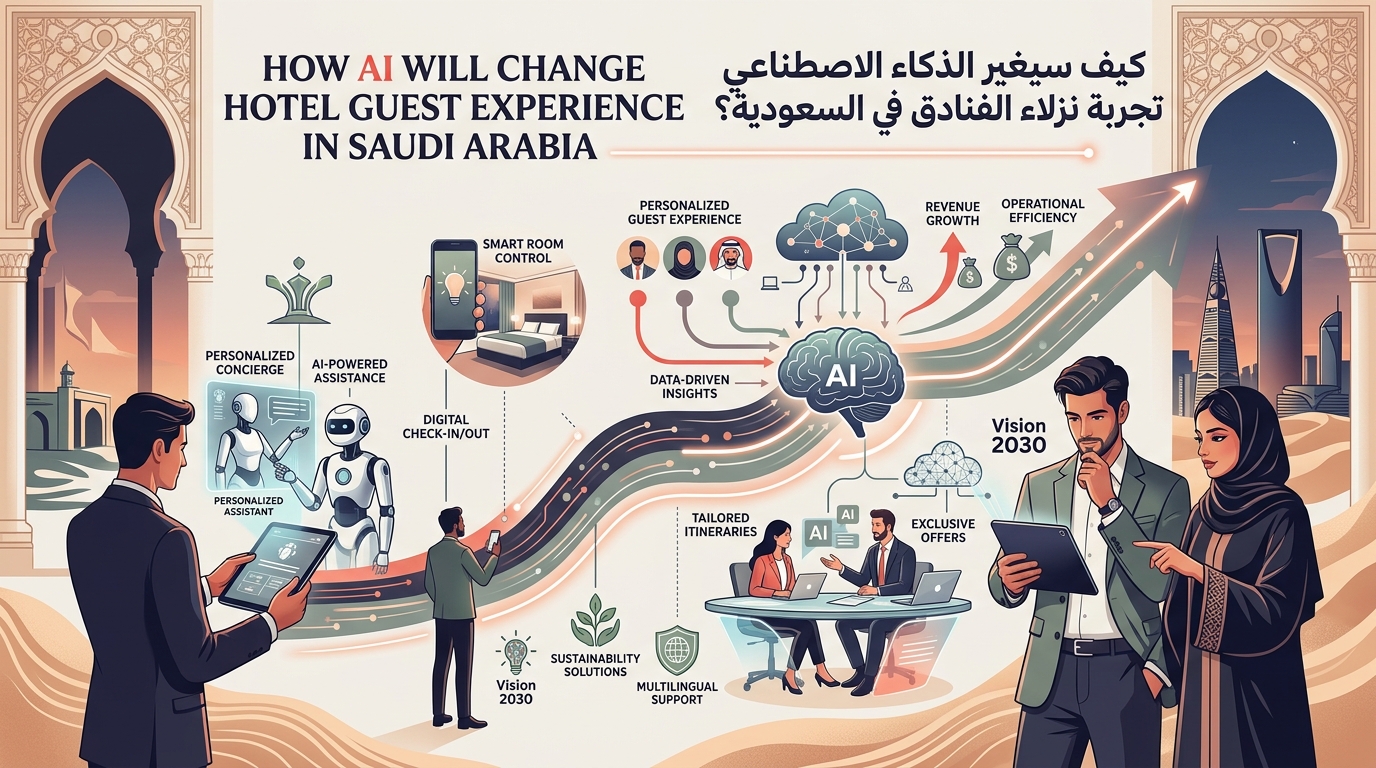
Explore how AI is revolutionizing hotel guest experiences in Saudi Arabia. From personalized service to smart rooms, discover the future of hospitality in the Kingdom. ...
Learn how to manage AlUla hotel bookings in this emerging cultural destination. Best times, prices, accommodation types & tips for Hegra, Winter at Tantora. Compare on Fandaqah.com....
Discover how The Red Sea Project, AMAALA & Sindalah prepare Saudi hotels for global luxury standards. Sustainability, AI tech, Vision 2030 & top resorts reviewed on Fandaqah.com....
Discover effective Saudi National Day hotel offers, staycation packages, and campaigns. Boost occupancy with family deals, luxury experiences, and Vision 2030-aligned promotions across Riyadh, Jeddah ...
Proven strategies to boost weekend occupancy in Saudi secondary cities. Packages, social media, local partnerships & Vision 2030 tips for hotels in Abha, Taif, AlUla & more....
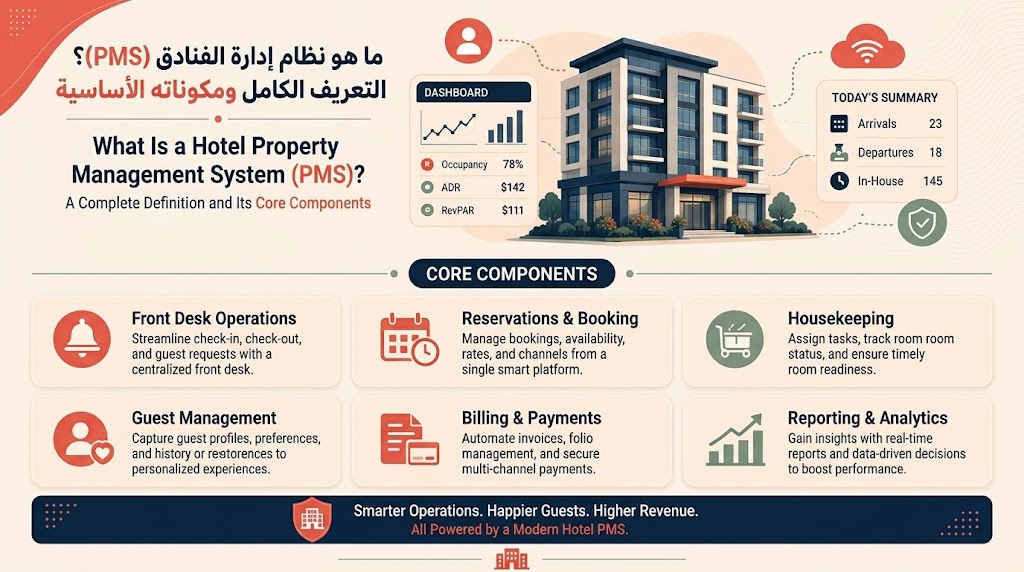
A Hotel PMS is the central software for managing reservations, rooms, guests, check-in/out, billing & reporting. Learn core components, benefits & how Saudi hotels can choose the right system....
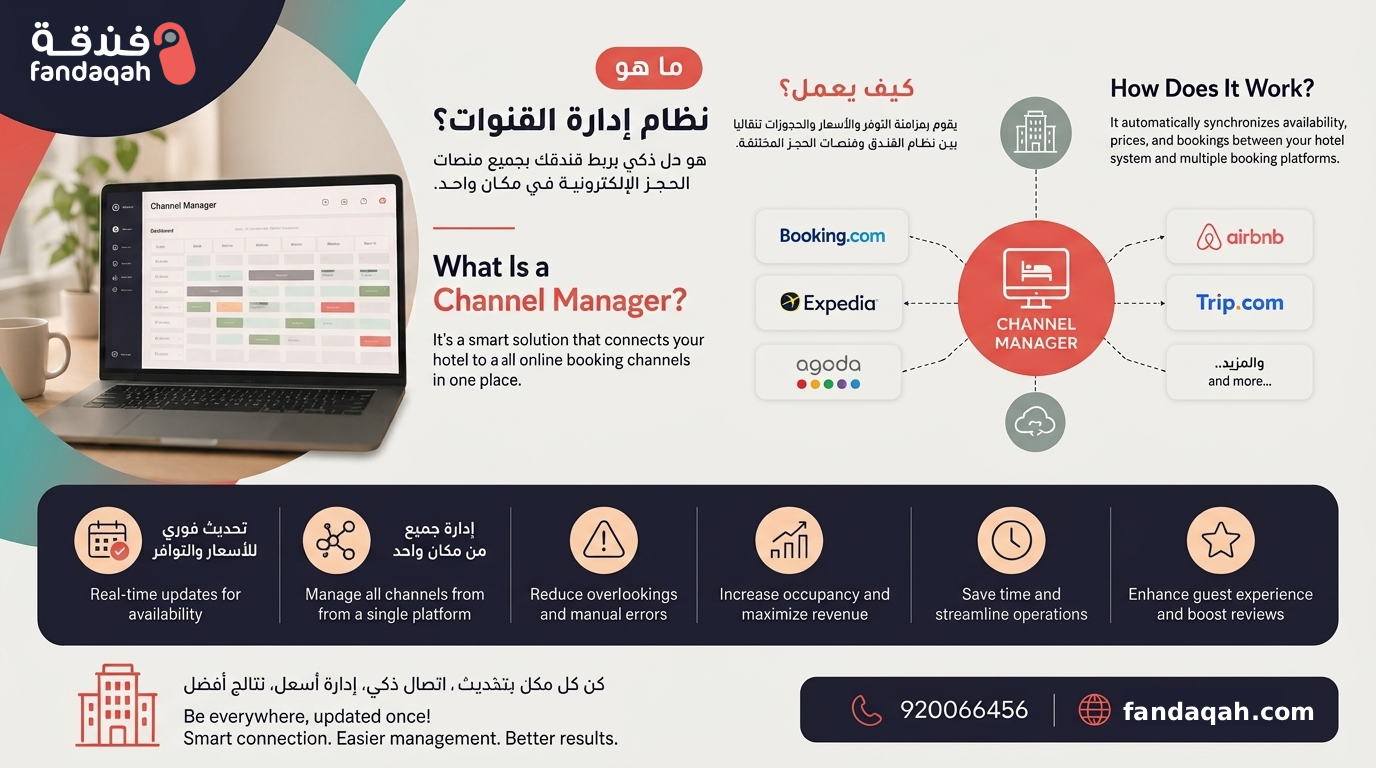
A hotel Channel Manager syncs rates, availability & reservations across OTAs from one place. Learn how it cuts overbooking risk, saves time & boosts distribution for Saudi hotels....
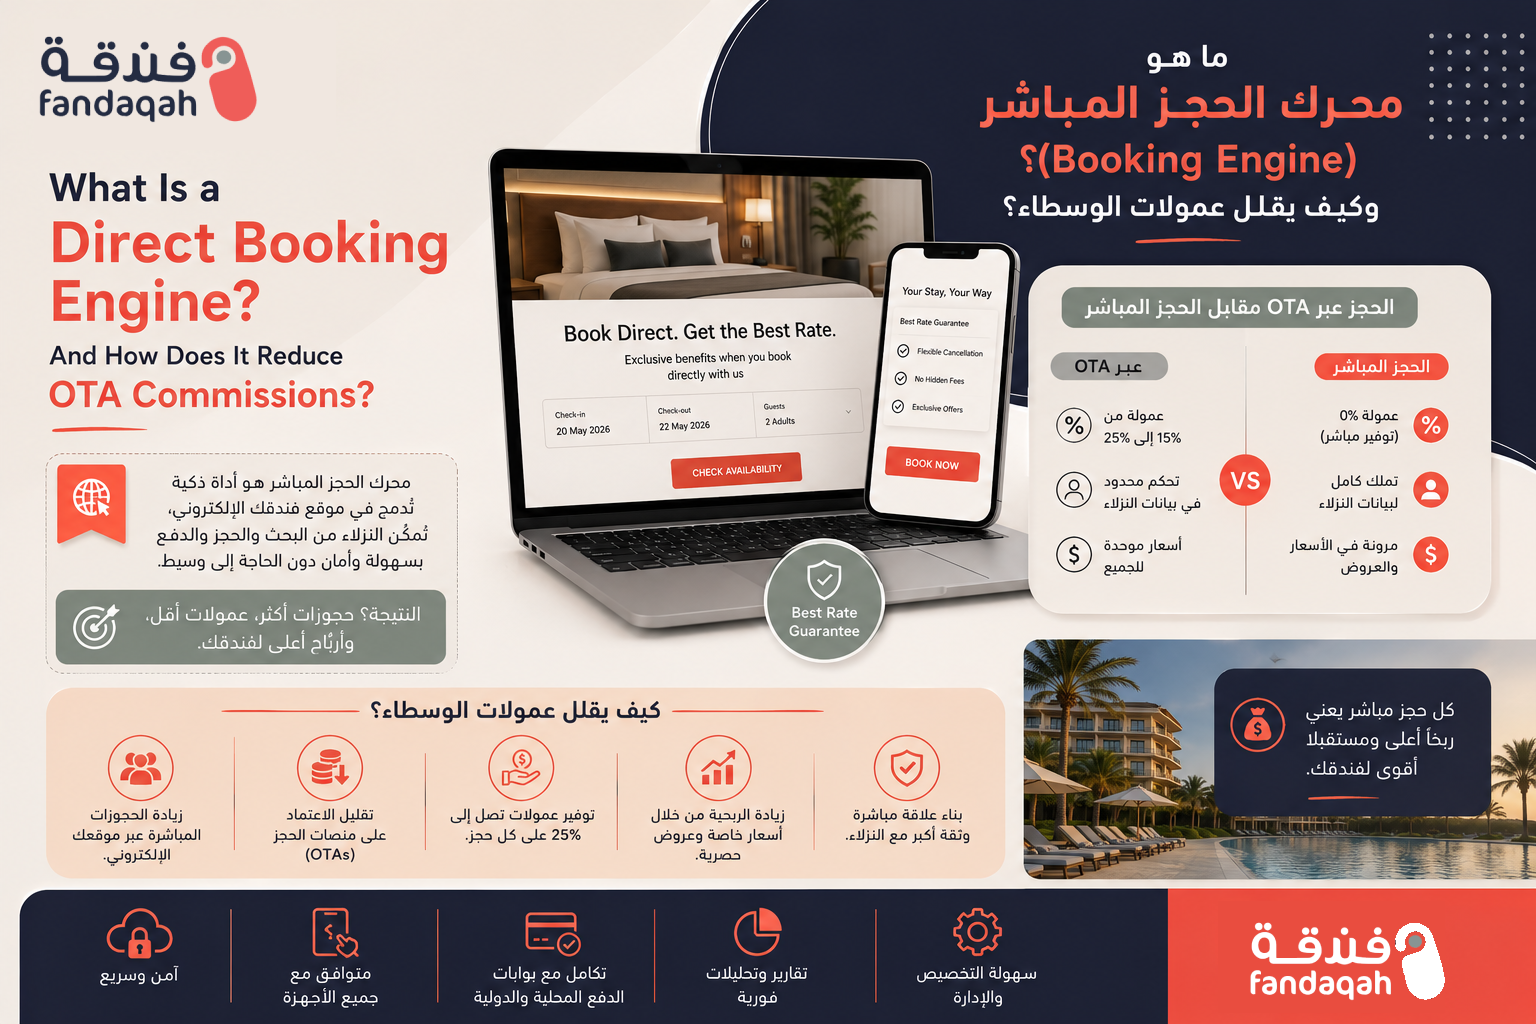
Learn what a direct booking engine is and how Saudi hotels can use it to cut OTA commissions by 15–25%, own guest data, boost direct revenue, and improve profitability under Vision 2030....
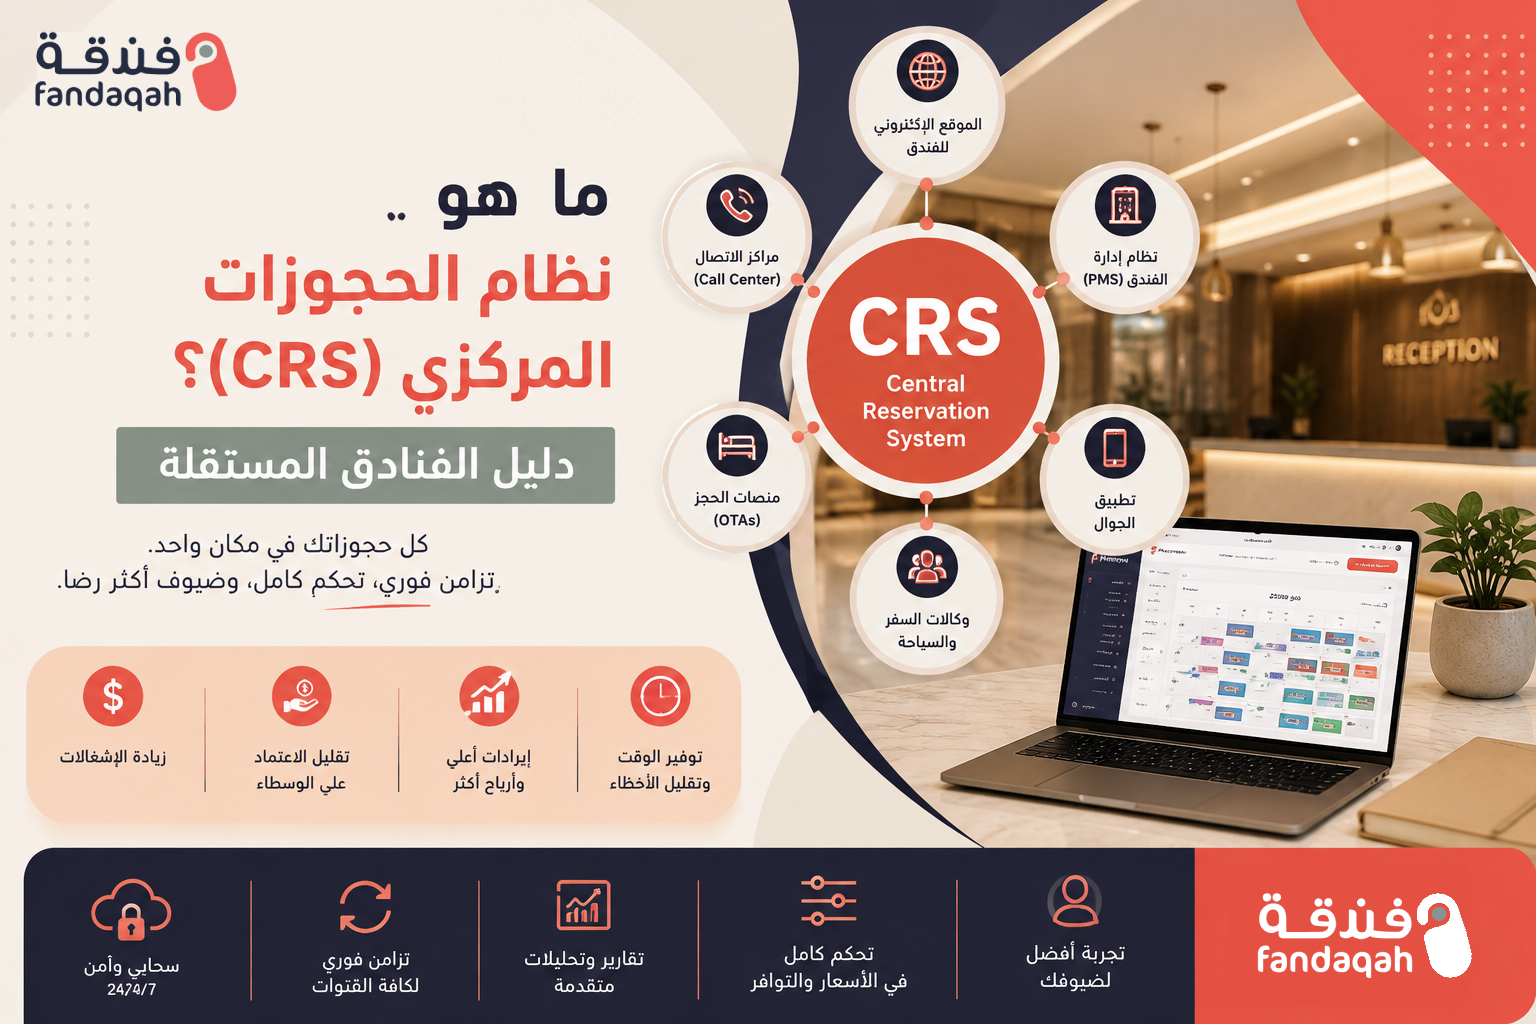
Discover what a Central Reservation System (CRS) is and how independent hotels in Saudi Arabia can use it to prevent overbookings, boost direct bookings, and maximize revenue under Vision 2030....
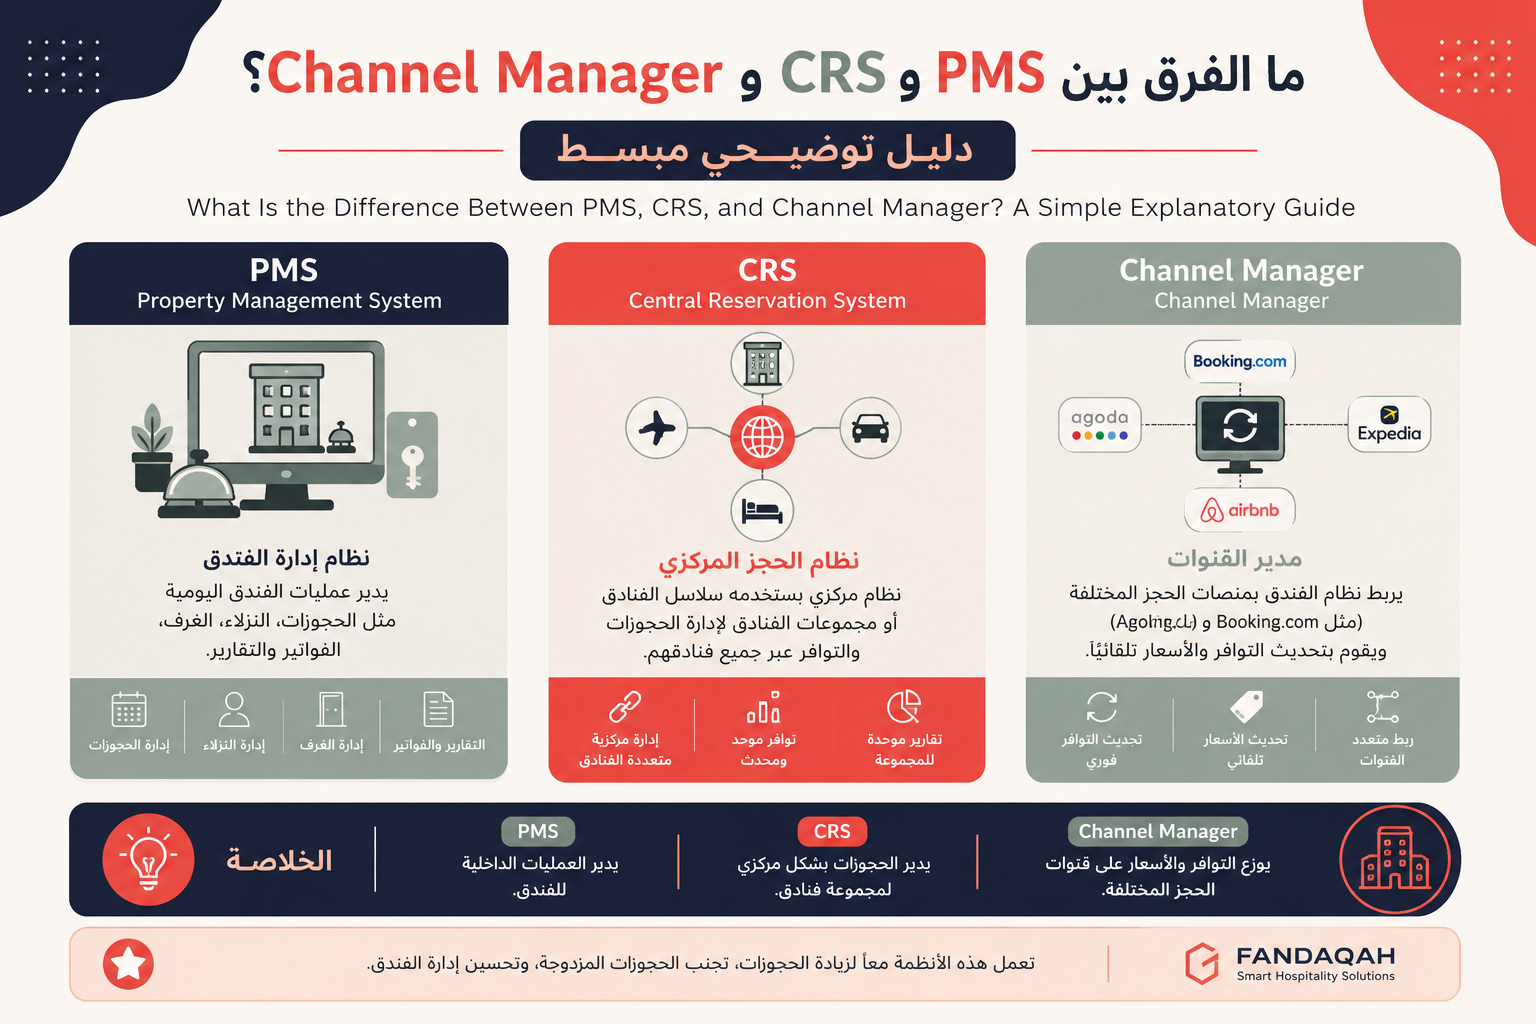
Clear differences between PMS, CRS, and Channel Manager explained. Learn which systems Saudi hotels need for operations, central bookings, and OTA distribution....
Discover the 15 most common hotel management mistakes draining Saudi hotel revenue. Practical fixes for booking systems, pricing, staff training, reviews & Vision 2030 alignment....
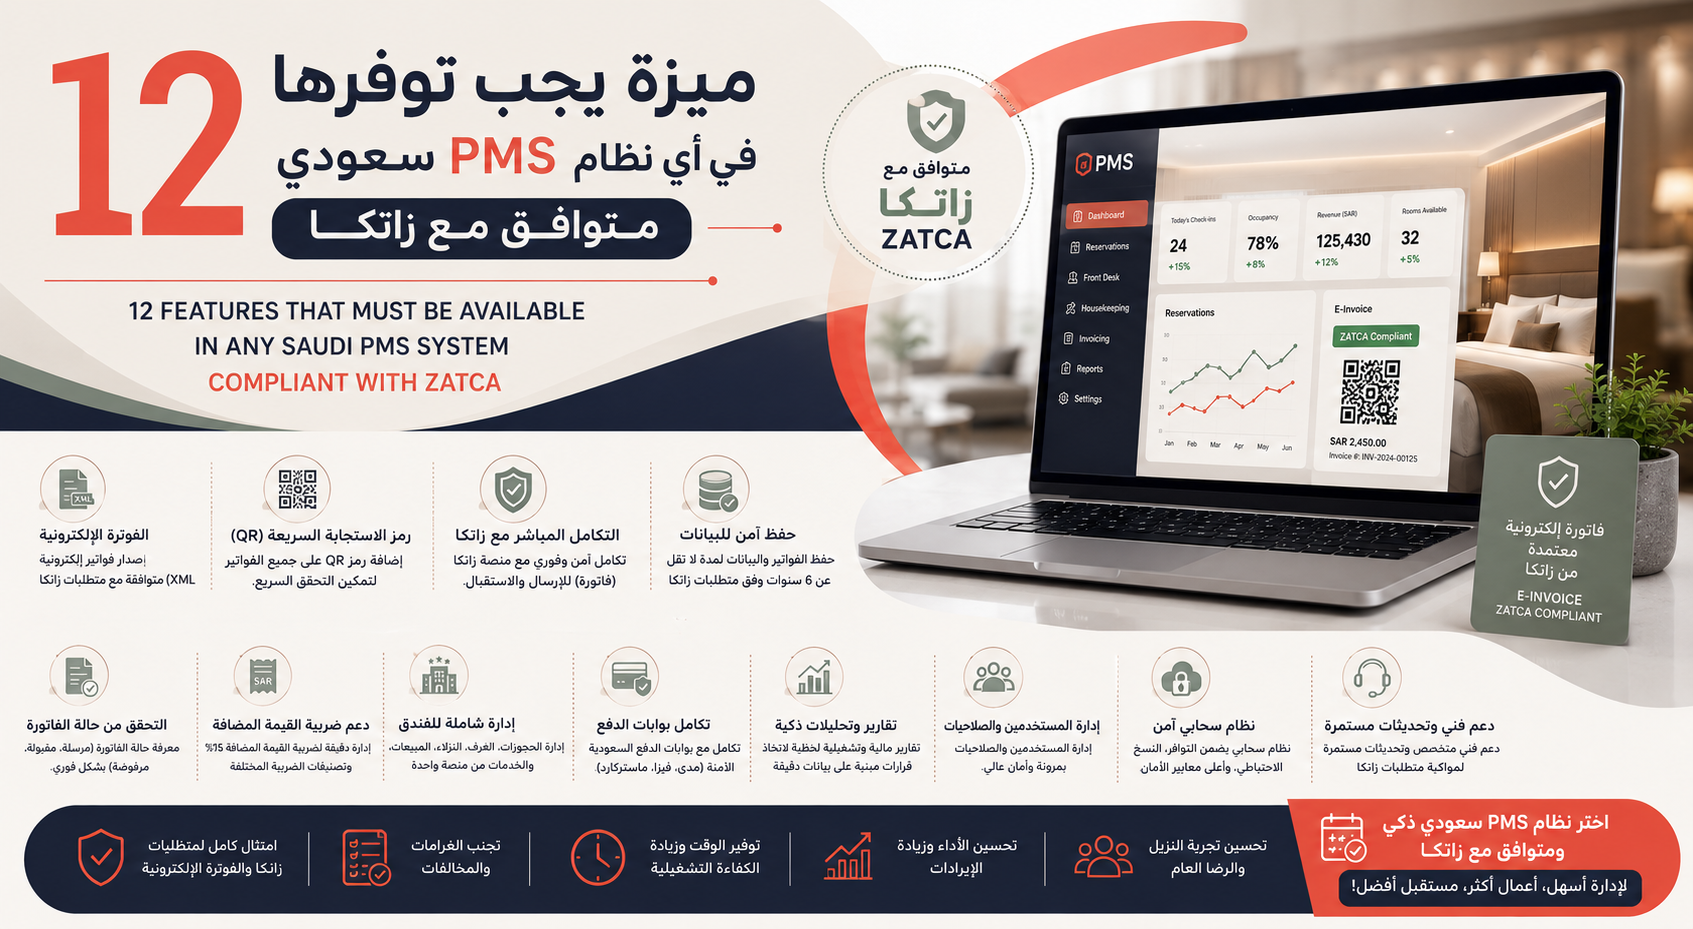
Discover the 12 essential features every Saudi property management system needs for full ZATCA e-invoicing compliance, Fatoora & Ejar integration, and seamless operations....
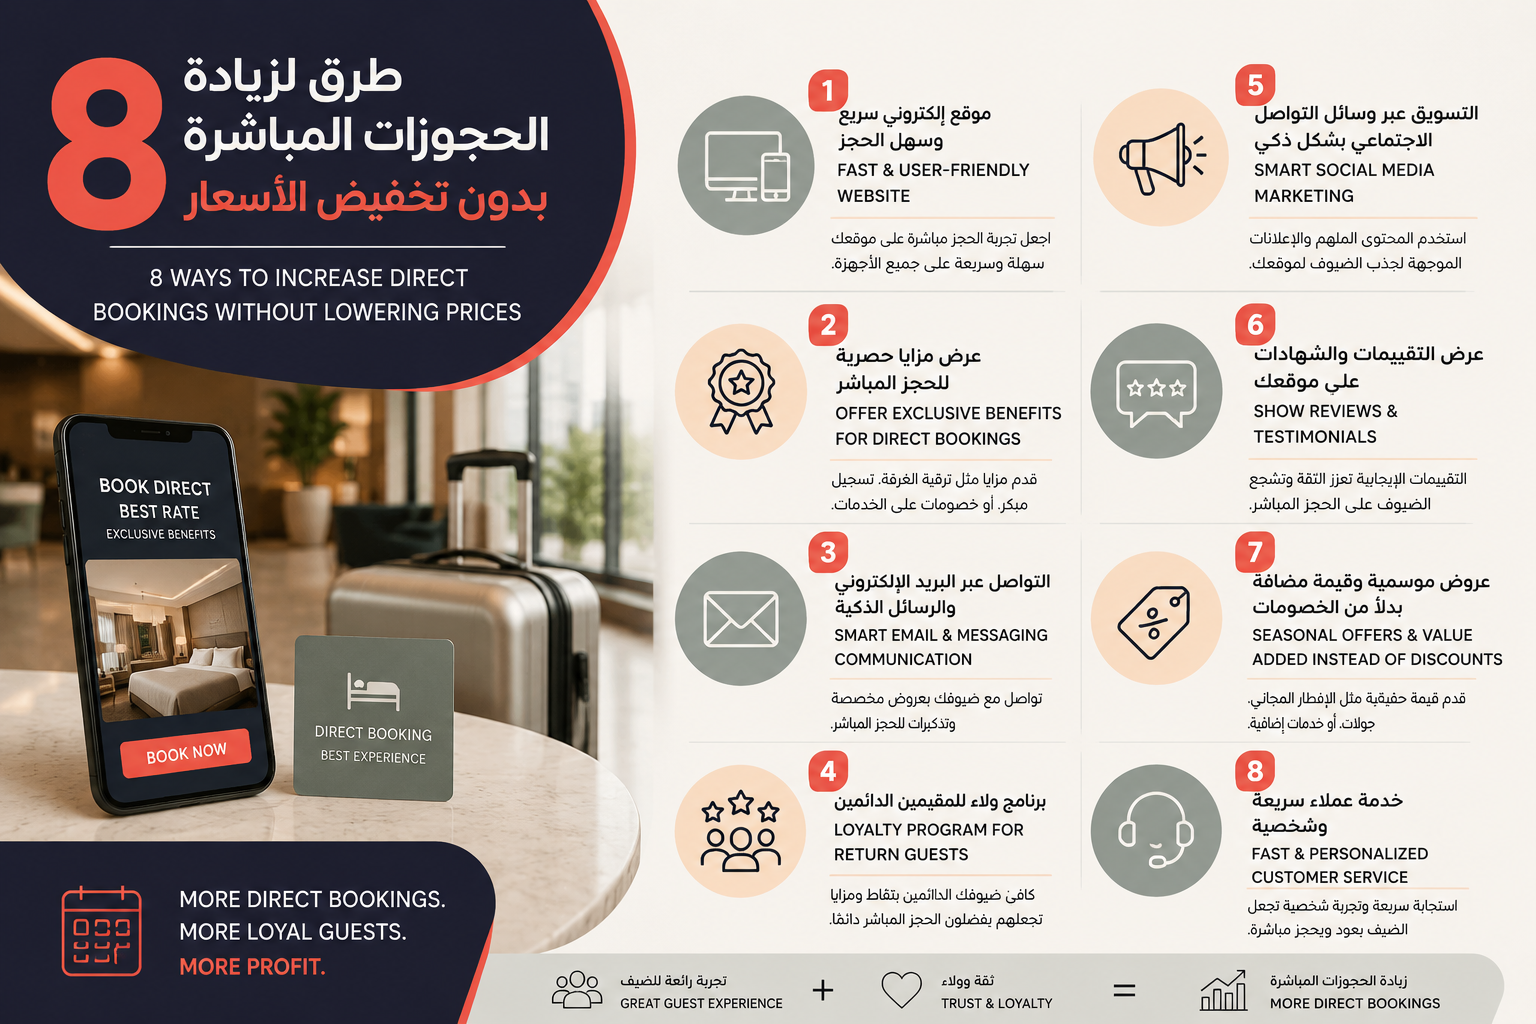
Discover 8 proven strategies for Saudi hotels to increase direct bookings without lowering prices. Optimize your booking engine, loyalty programs & more aligned with Vision 2030....
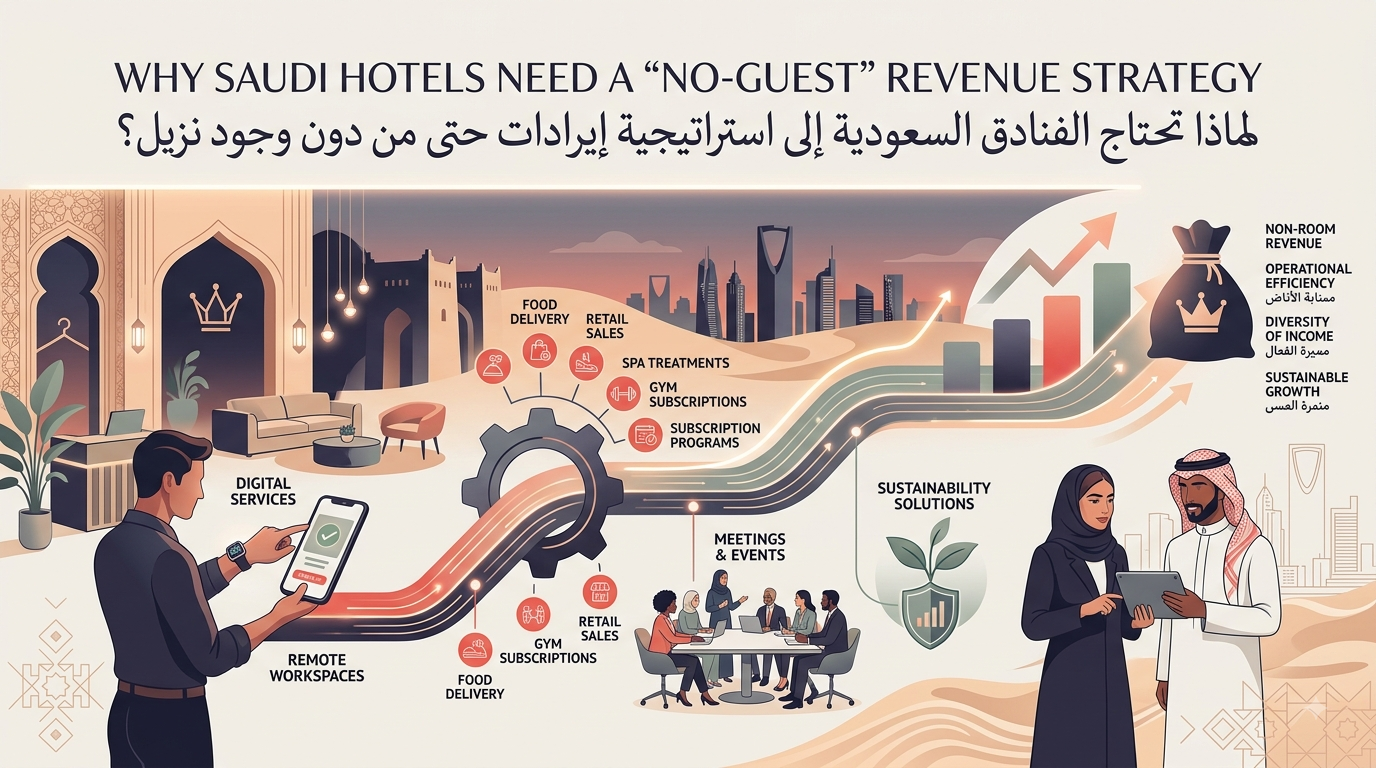
Unlock new profit streams beyond room nights. Discover why Saudi hotels must embrace "no-guest" revenue strategies to enhance profitability, diversify income, and boost guest loyalty in a competitive ...
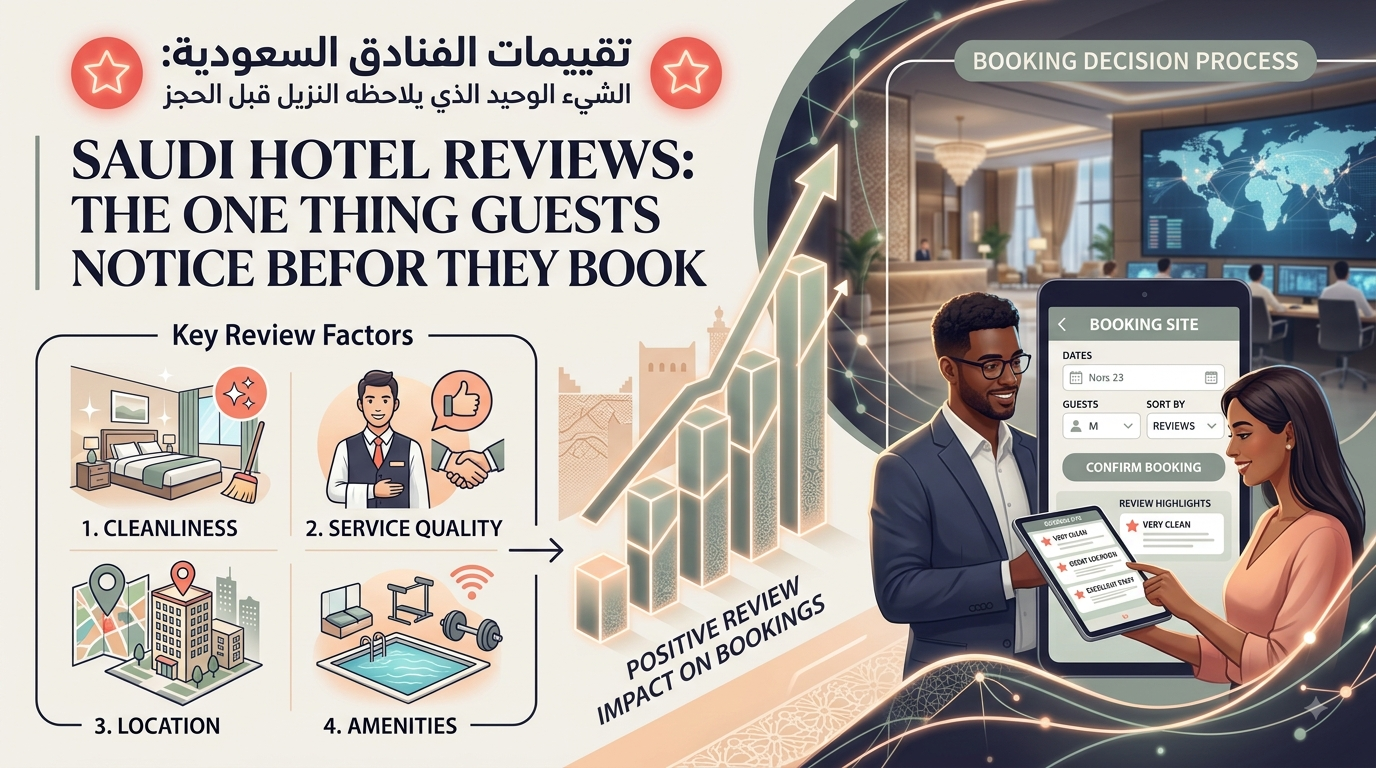
Discover the ultimate factor influencing Saudi hotel bookings. Learn how online reviews, especially around service and culture, shape guest decisions and why they're crucial for your next stay. ...
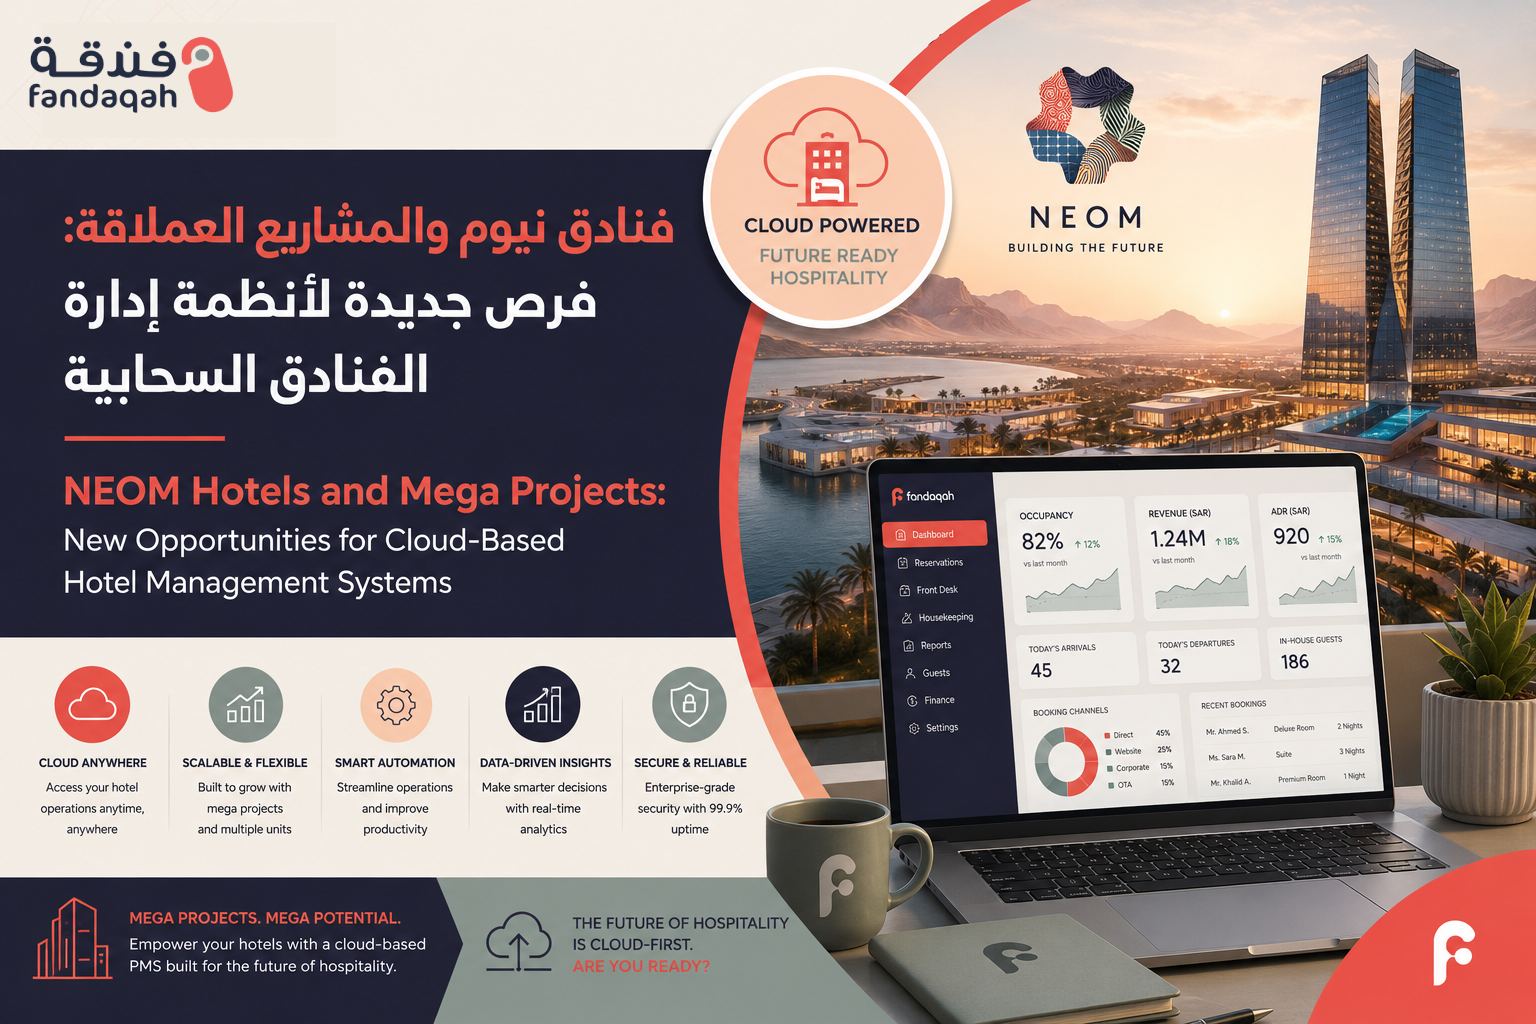
Discover how NEOM hotels and Saudi mega projects create huge opportunities for cloud-based hotel management systems. Boost efficiency, guest experience & Vision 2030 readiness....
Explore the battle between Saudi hotels and short-term rentals for today's traveler. Discover which accommodation type offers the best experience, value, and authenticity for your next Saudi adventure...
Learn how hotels manage high demand during Riyadh Season with dynamic pricing, demand forecasting & smart strategies to maximize revenue without losses....
Discover how creating a single, highly photogenic "Instagram Room" can significantly boost hotel revenue through organic social media marketing, enhanced guest experience, and increased bookings. Lear...
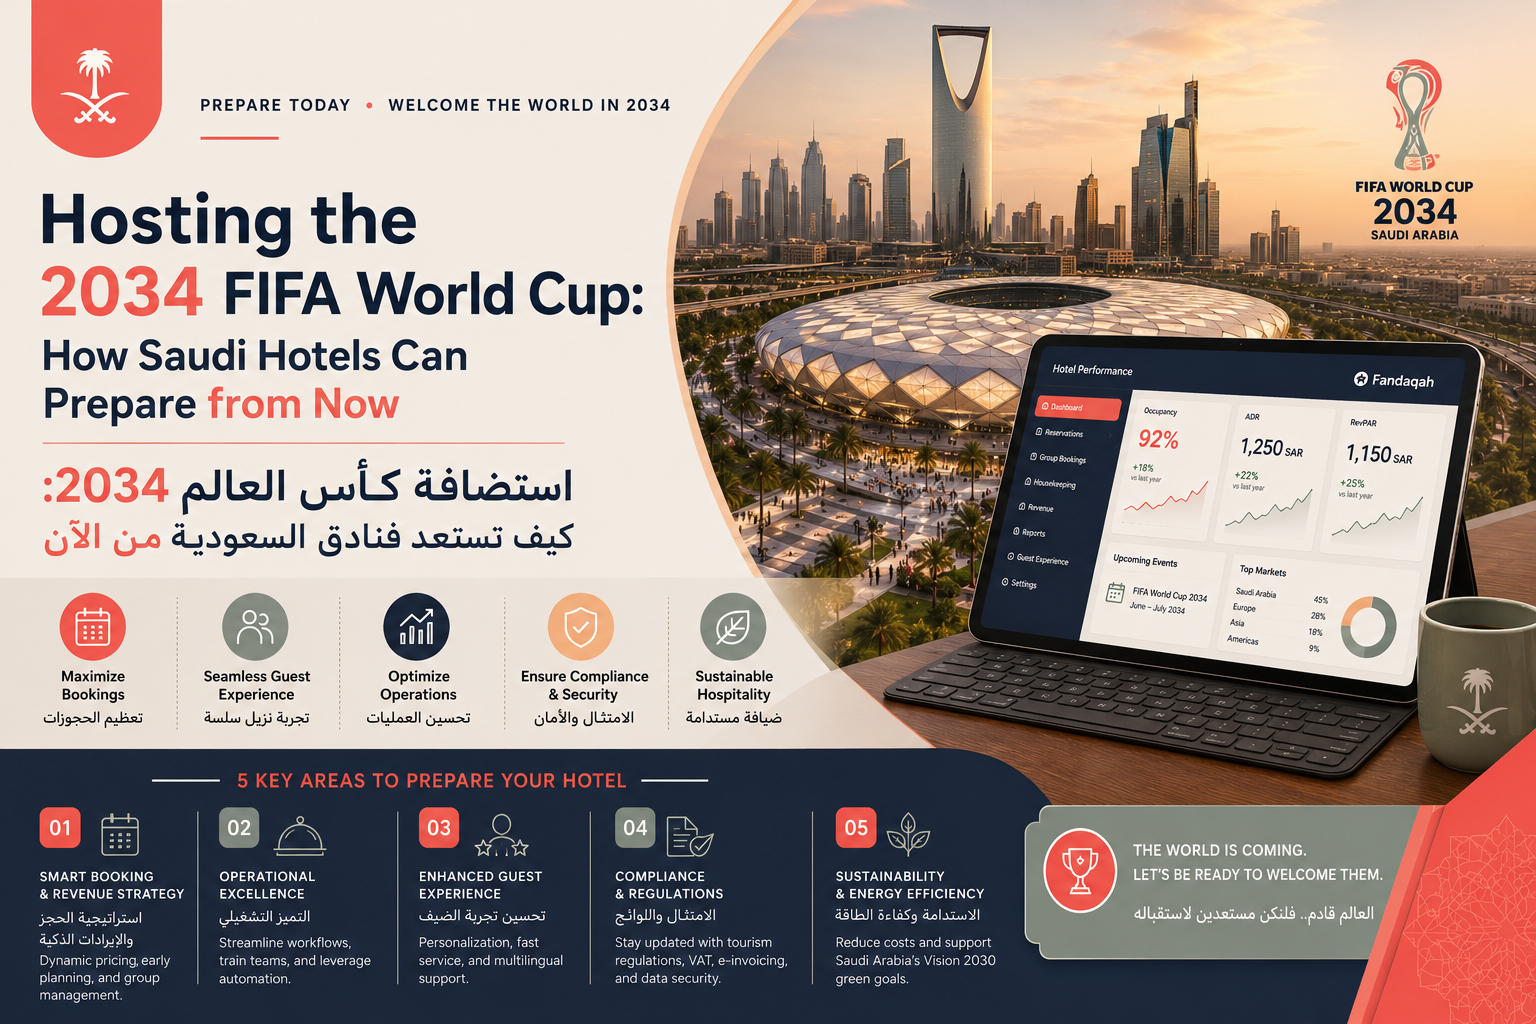
How Saudi hotels are gearing up for the 2034 FIFA World Cup: capacity expansion, smart tech, sustainability, and Vision 2030 strategies to deliver world-class hospitality for millions of fans....
Prepare your hotel for Hajj 2027 with modern PMS systems, full Ministry of Hajj & Umrah compliance, and smart capacity management. Boost efficiency, pilgrim experience, and seasonal revenue....
Unlock more bookings without spending more. Discover expert strategies to optimize your hotel's online presence, enhance guest experience, and leverage existing resources for maximum revenue growth. ...
Discover how AI is revolutionizing hotel management in Saudi Arabia by 2026. Explore key trends, applications, and the strategic advantages AI offers in enhancing guest experience, optimizing operatio...
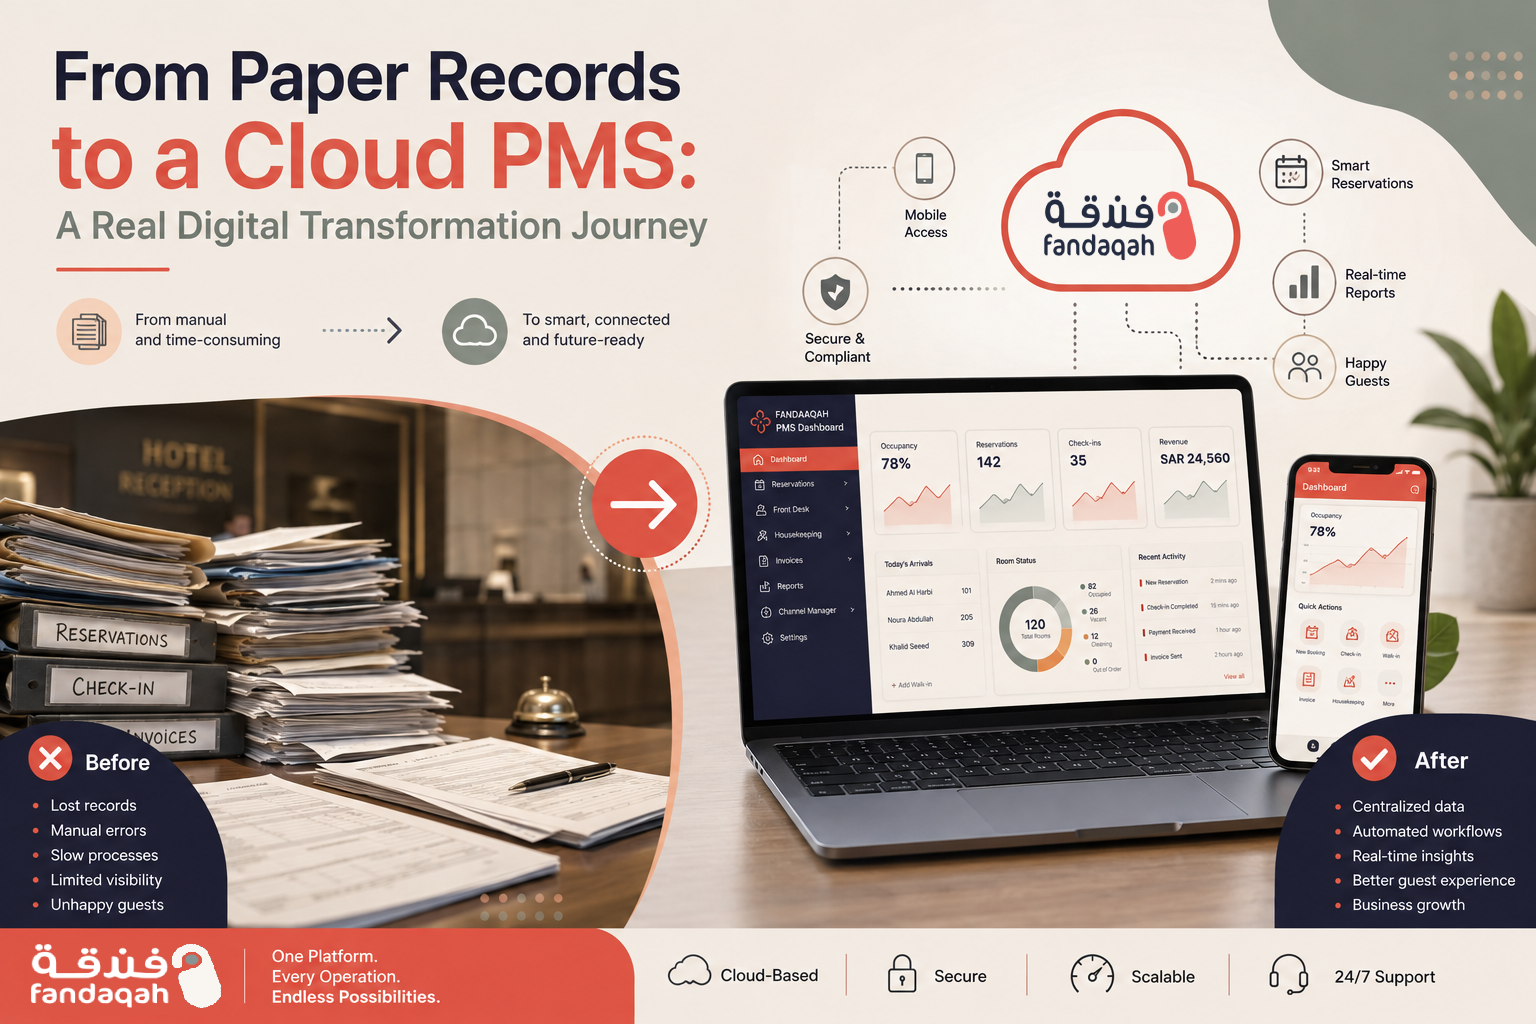
Discover how Saudi hotels move from paper records to a cloud PMS. Boost efficiency, guest experience & align with Vision 2030. Real benefits, comparison & FAQ....
Exclusive interview with Khalid Al-Shahri, Jeddah hotel GM, on how Fandaqah PMS eliminated double bookings, cut check-in to 3 min, and boosted occupancy to 78%....
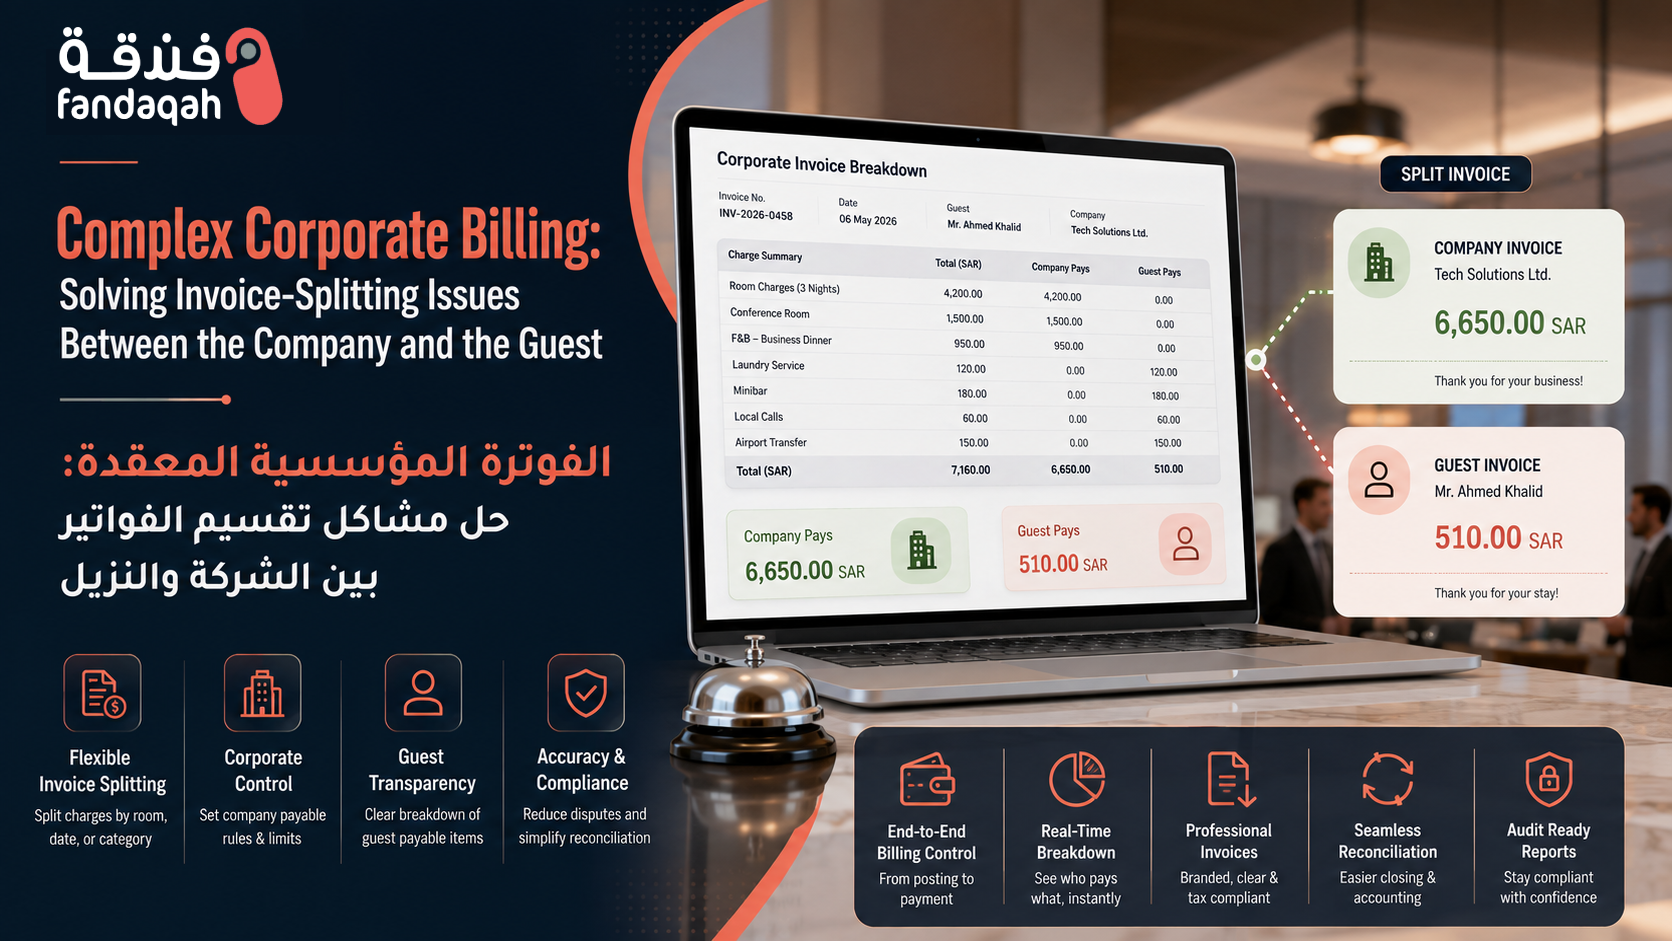
Master complex corporate billing & invoice splitting between company and guest. Automate ZATCA-compliant solutions for Saudi hotels & serviced apartments....
Master large group bookings in Saudi hospitality. Avoid operational chaos with proven strategies for hotels, restaurants & events during Hajj, Riyadh Season & Vision 2030....
Discover the best cloud-based elite hotel & luxury resort management software (PMS) for Saudi Arabia. Boost guest experience, automate operations & align with Vision 2030....
Practical guide for independent boutique hotels in Saudi Arabia to compete with major chains on a limited budget. Leverage local hospitality, organic SEO/GEO, Vision 2030 opportunities, and smart part...
Explore the rise of AI receptionists in hotels. This expert analysis compares AI to human front desks, examining benefits, drawbacks, and the future of hospitality. Discover if AI is truly better for ...
Unlock the secrets to a fully booked hotel. Discover 50 actionable marketing ideas, from local SEO to immersive virtual tours, designed to skyrocket your bookings and boost revenue....
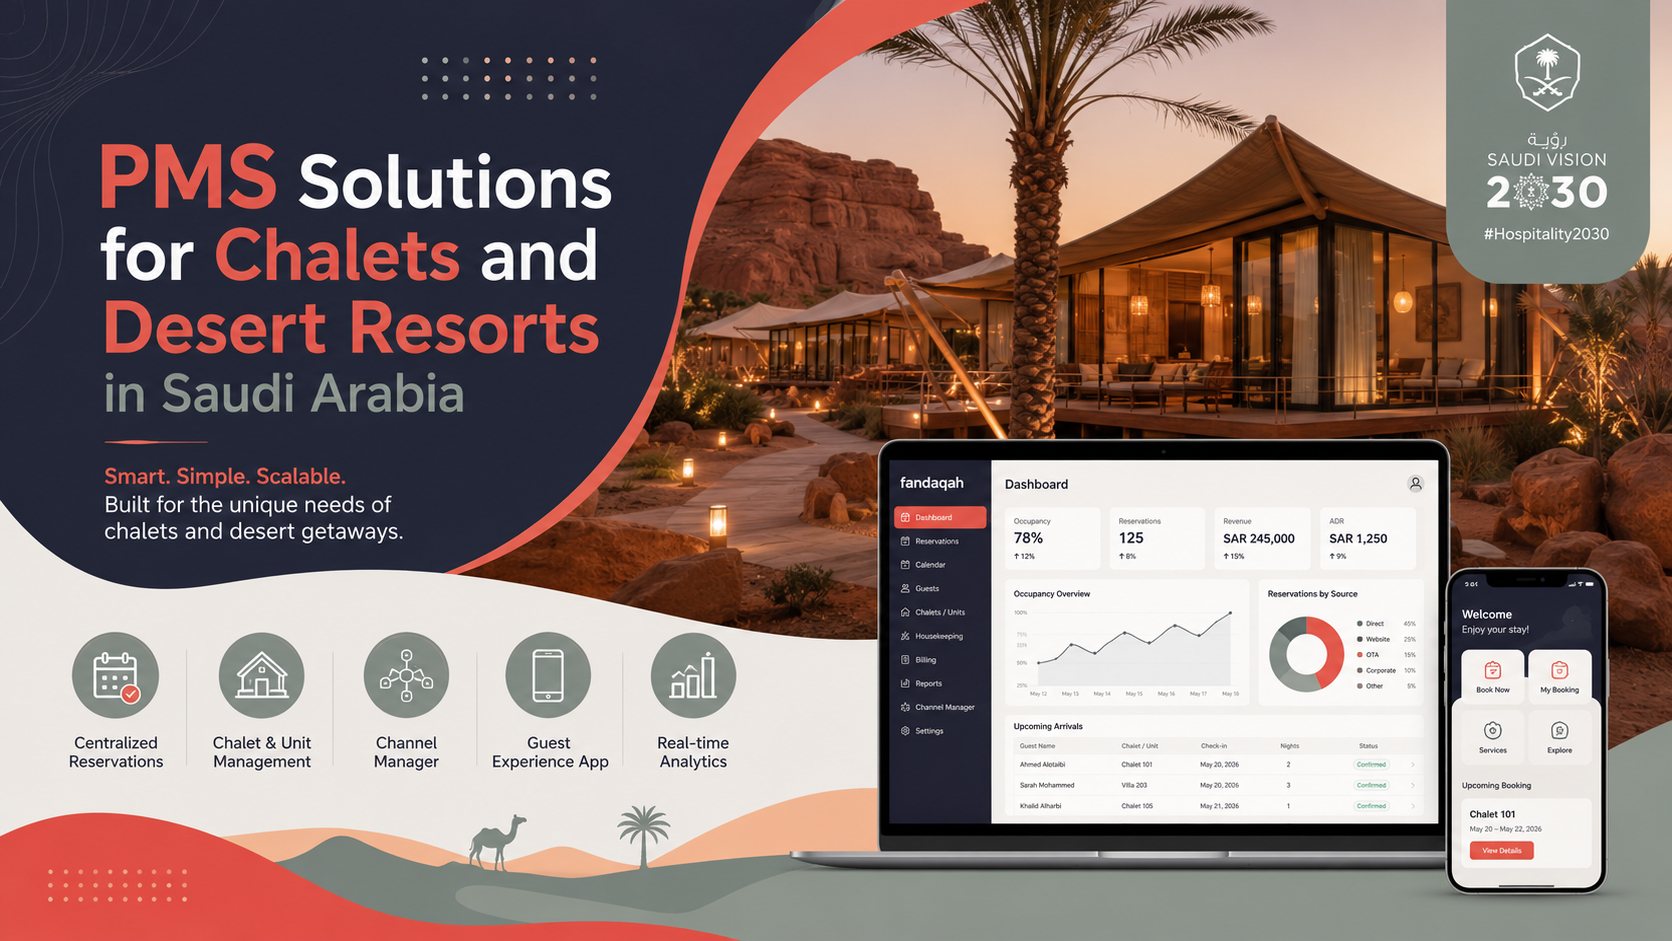
Discover how a modern PMS transforms chalet and desert resort management in Saudi Arabia. Boost bookings, automate operations, and align with Vision 2030 tourism goals....
ZATCA e-invoicing alone isn’t enough. Learn how Saudi hotels can secure guest payment data with PCI DSS, NCA controls, and Vision 2030-aligned strategies to prevent breaches and build trust....
Where should Saudi hotels store guest data? A practical guide to data sovereignty, PDPL compliance, local cloud storage, and protecting privacy under Vision 2030....
Secure hotel PMS accounts with passkeys. A practical guide for Saudi hotel owners on passwordless, phishing-resistant authentication, implementation, and recovery....
Learn how Saudi hotels can cut energy, water, and food waste costs while aligning with Vision 2030. Practical steps, KPIs, and a clear sustainability plan for better profits and guest experience....
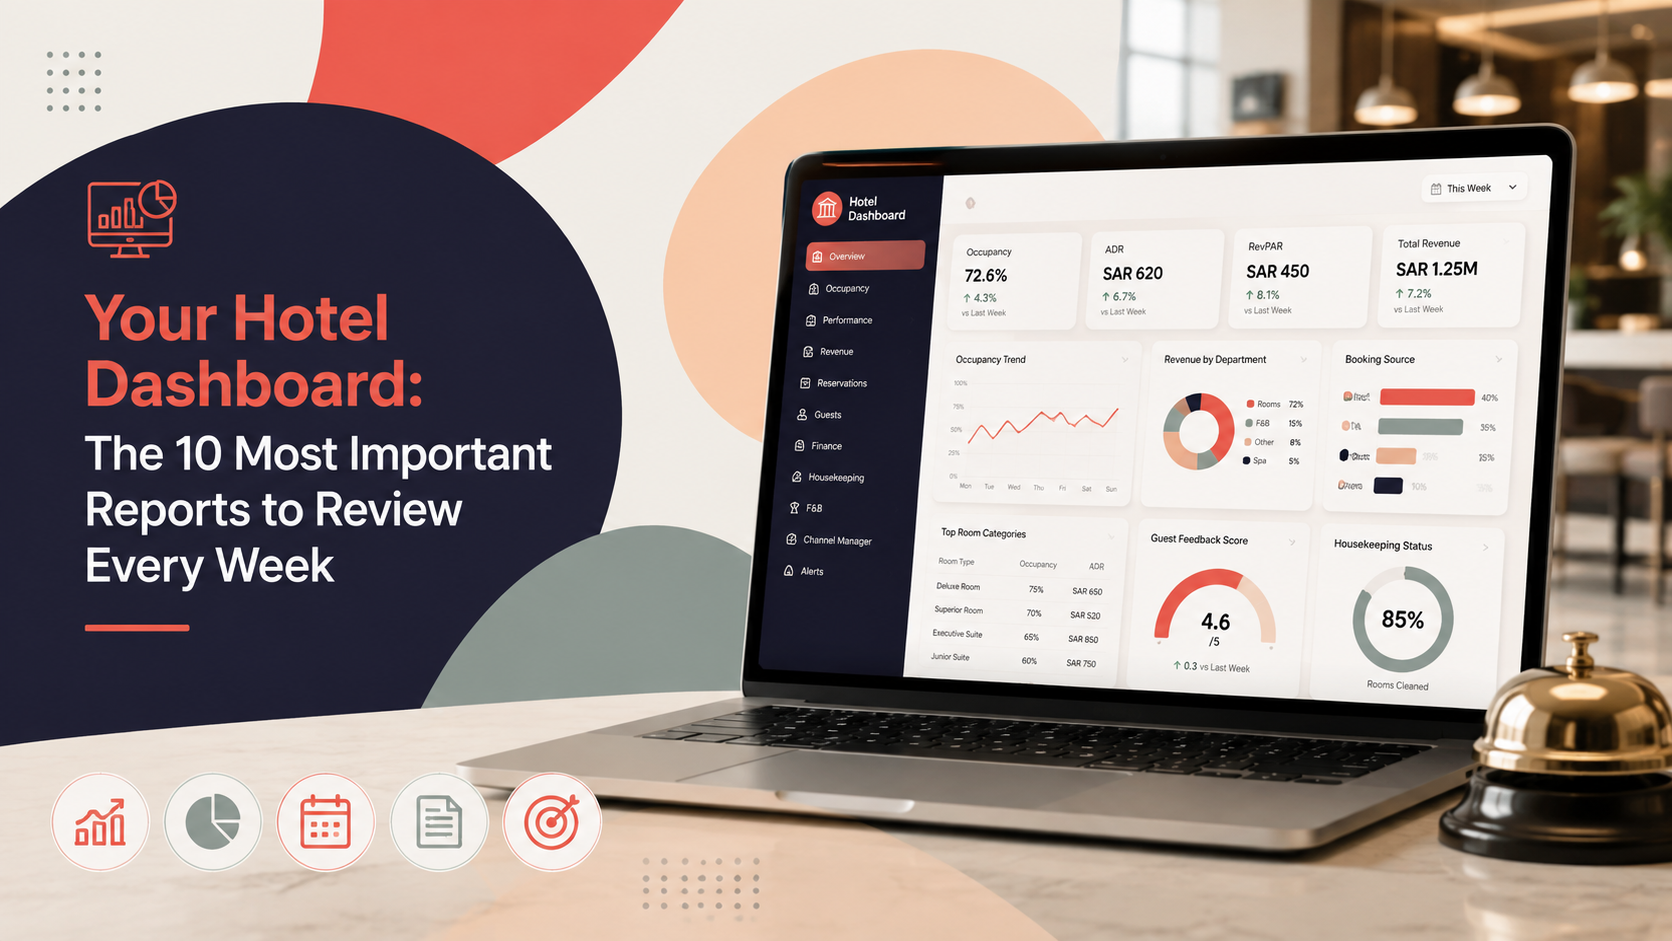
Discover the 10 essential hotel dashboard reports to review every week—occupancy, ADR, RevPAR, booking pace, channels, guest satisfaction & more—to boost revenue and performance in Saudi Arabia....
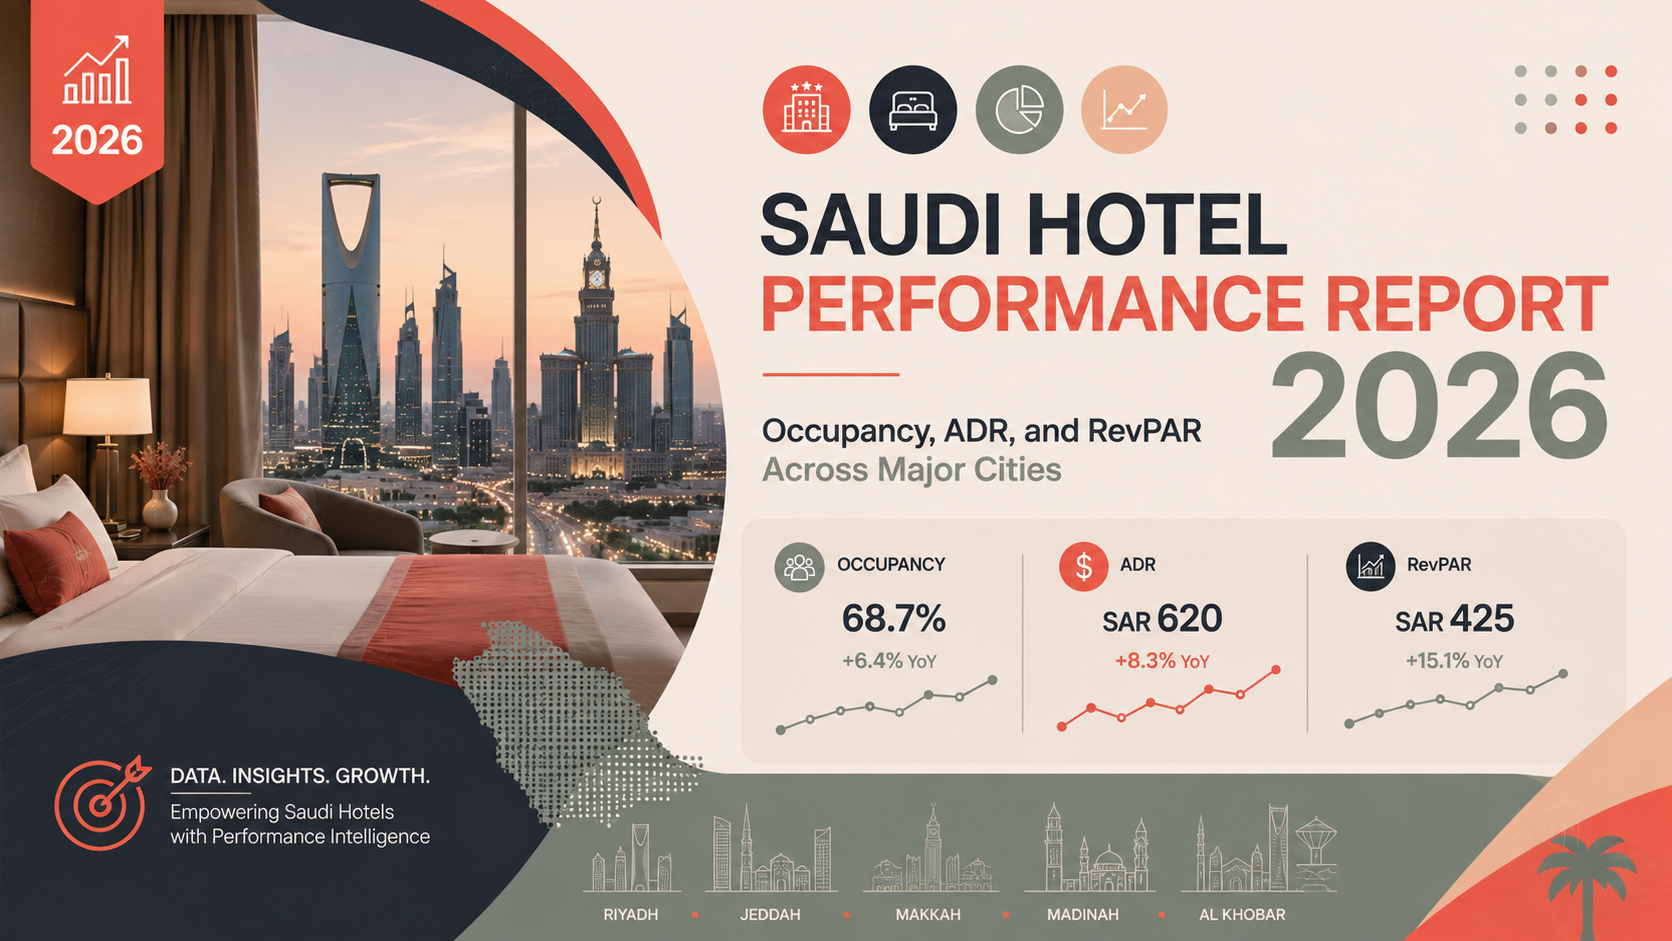
Discover the Saudi Hotel Performance Report 2026 with projected occupancy, ADR, and RevPAR for Riyadh, Jeddah, Makkah, Madinah, Dammam, and AlUla. Key insights for investors and operators aligned with...
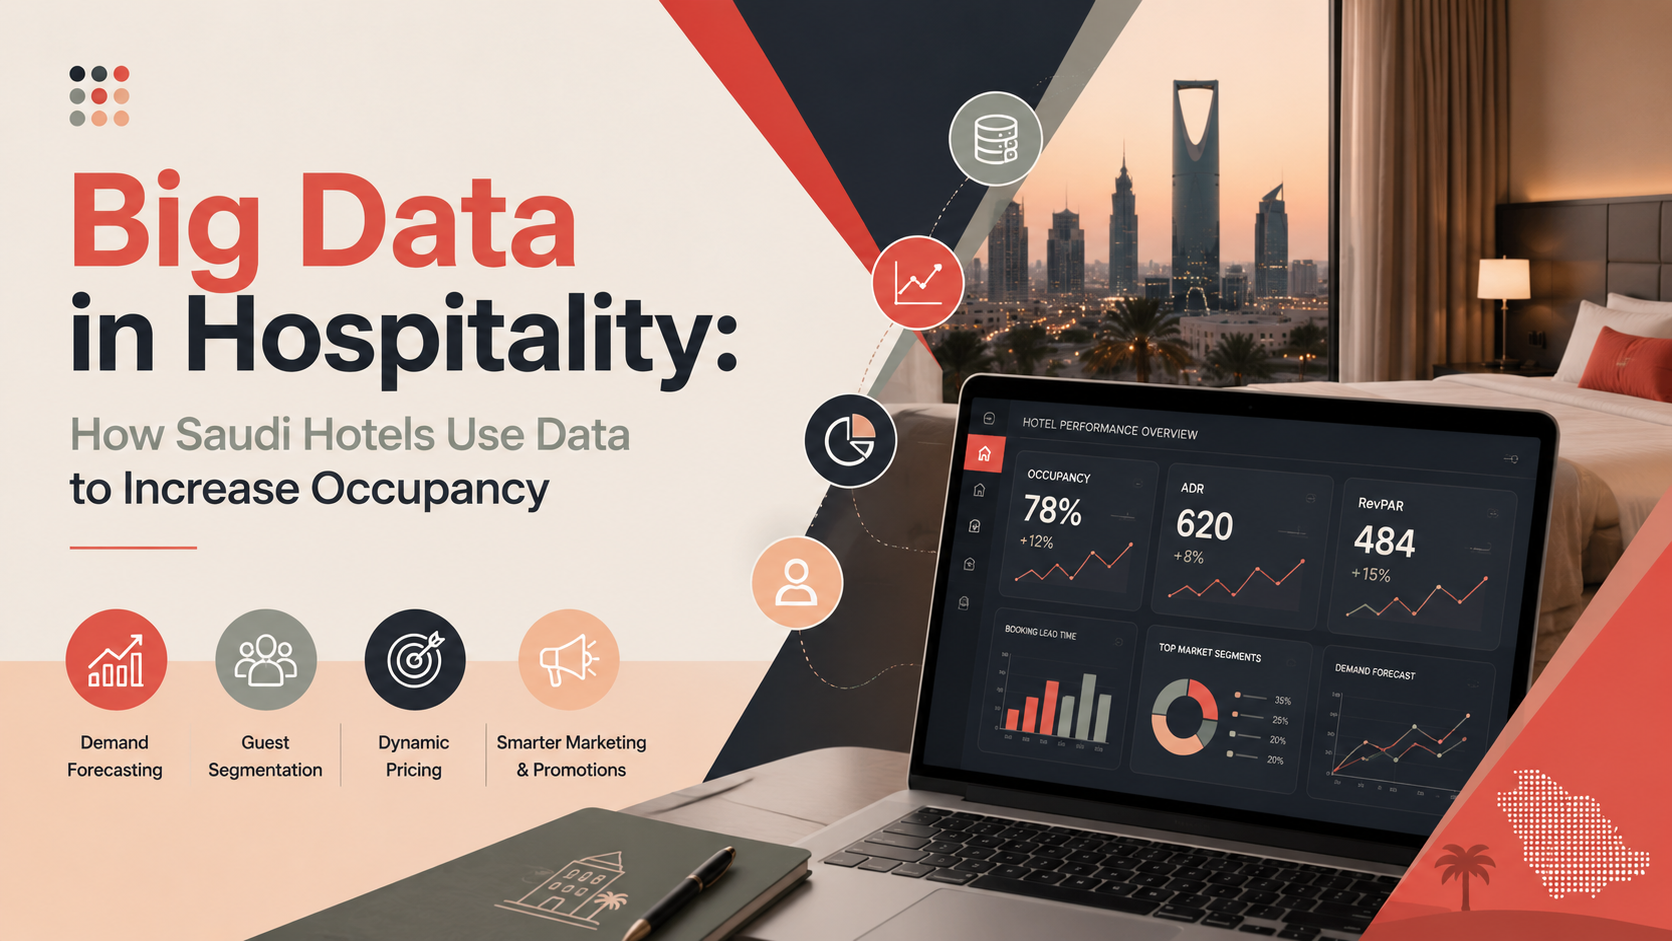
Discover how Saudi hotels use big data analytics, dynamic pricing, and predictive tools to increase occupancy, raise RevPAR, and support Vision 2030 tourism goals....
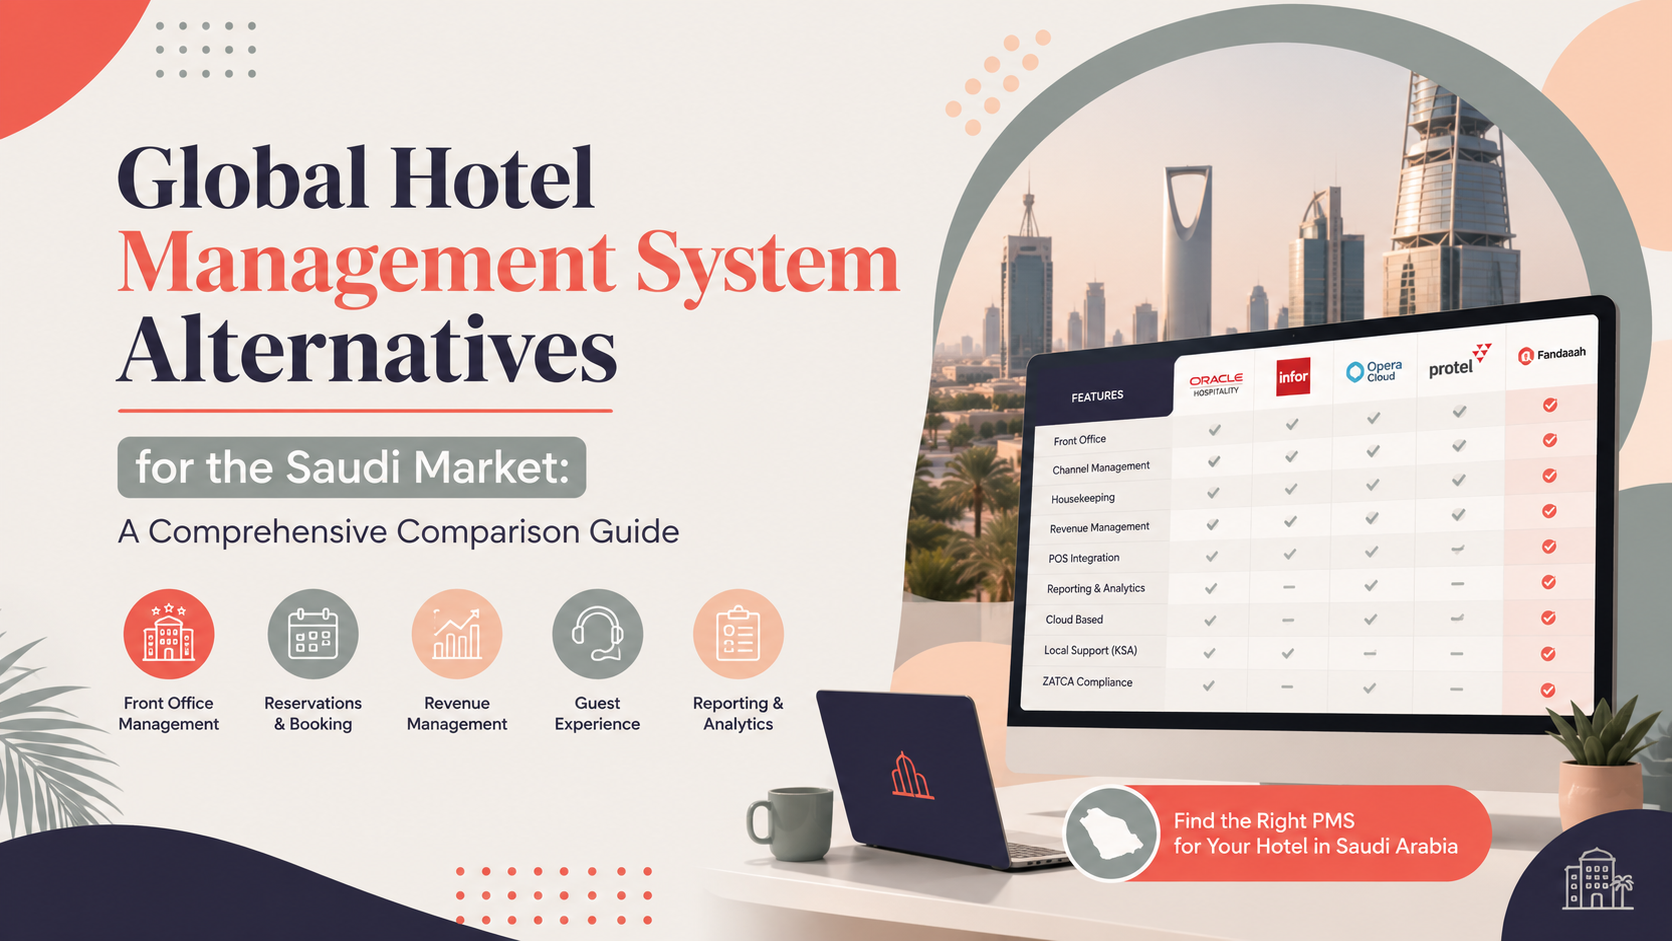
Compare the best hotel management system alternatives for Saudi hotels. Cloudbeds, Mews, Deyafa & more with full Fatoorah e-invoicing support, Arabic UI & Vision 2030 readiness....
Discover 7 warning signs your current hotel PMS is silently draining profits. Learn how upgrading boosts revenue, cuts costs & ensures Dyafa compliance in Saudi Arabia....
Compare Fandaqah vs SiteMinder for Saudi hotels. Discover which channel manager & booking engine wins on Arabic support, local OTAs, Mada payments, pricing & Vision 2030 fit....
Compare Fandaqah and Hotelogix for small & mid-sized hotels in Saudi Arabia and the Gulf. Arabic-first PMS, ZATCA compliance, local payments & more....
Ready-to-use PMS Request for Proposal (RFP) template for Saudi hotels. Compare vendors, define requirements, integrations, security & implementation for smarter hotel software selection....
Learn how to migrate your hotel data to a new PMS without risk. Discover the 2026 step-by-step migration checklist for Saudi hotels, including testing, security, and successful go-live planning....
Learn how a hotel PMS helps front office managers prevent room assignment mistakes, reduce billing errors, and improve guest satisfaction in Saudi hotels....
Learn how hotel sales managers in Saudi Arabia win corporate contracts and conference business with smarter outreach, pricing, and partnerships....
Learn how hotel IT managers choose secure, ZATCA-compliant systems, protect guest data, and ensure seamless PMS, POS, and e-invoicing integration. ...
Discover the hotel food and beverage manager’s core responsibilities, technology tools, and how they improve performance in Saudi hospitality....
Learn the hotel revenue manager's role, key tools, KPIs, and how a PMS helps maximize hotel profitability with dynamic pricing and revenue management....
Learn how a unified omnichannel guest experience improves hotel operations, guest satisfaction, loyalty, and direct bookings with modern hospitality technology....
Learn how Saudi hotels can attract bleisure travelers through smart hospitality strategies, better guest experiences, and Vision 2030 tourism opportunities....
Discover how a smart guest app improves hotel guest loyalty, increases direct bookings, enhances the guest experience, and supports digital hospitality in Saudi Arabia....
Learn how hotel wholesalers work, their benefits and risks, and how Saudi hotels can improve occupancy, revenue, and global distribution....
Learn how hotels in Saudi Arabia can maintain rate parity, monitor pricing across OTAs, protect revenue, and improve distribution strategy....
Learn how Saudi hotels can improve Google Hotel Ads visibility, price accuracy, direct bookings, and profitability without increasing ad costs....
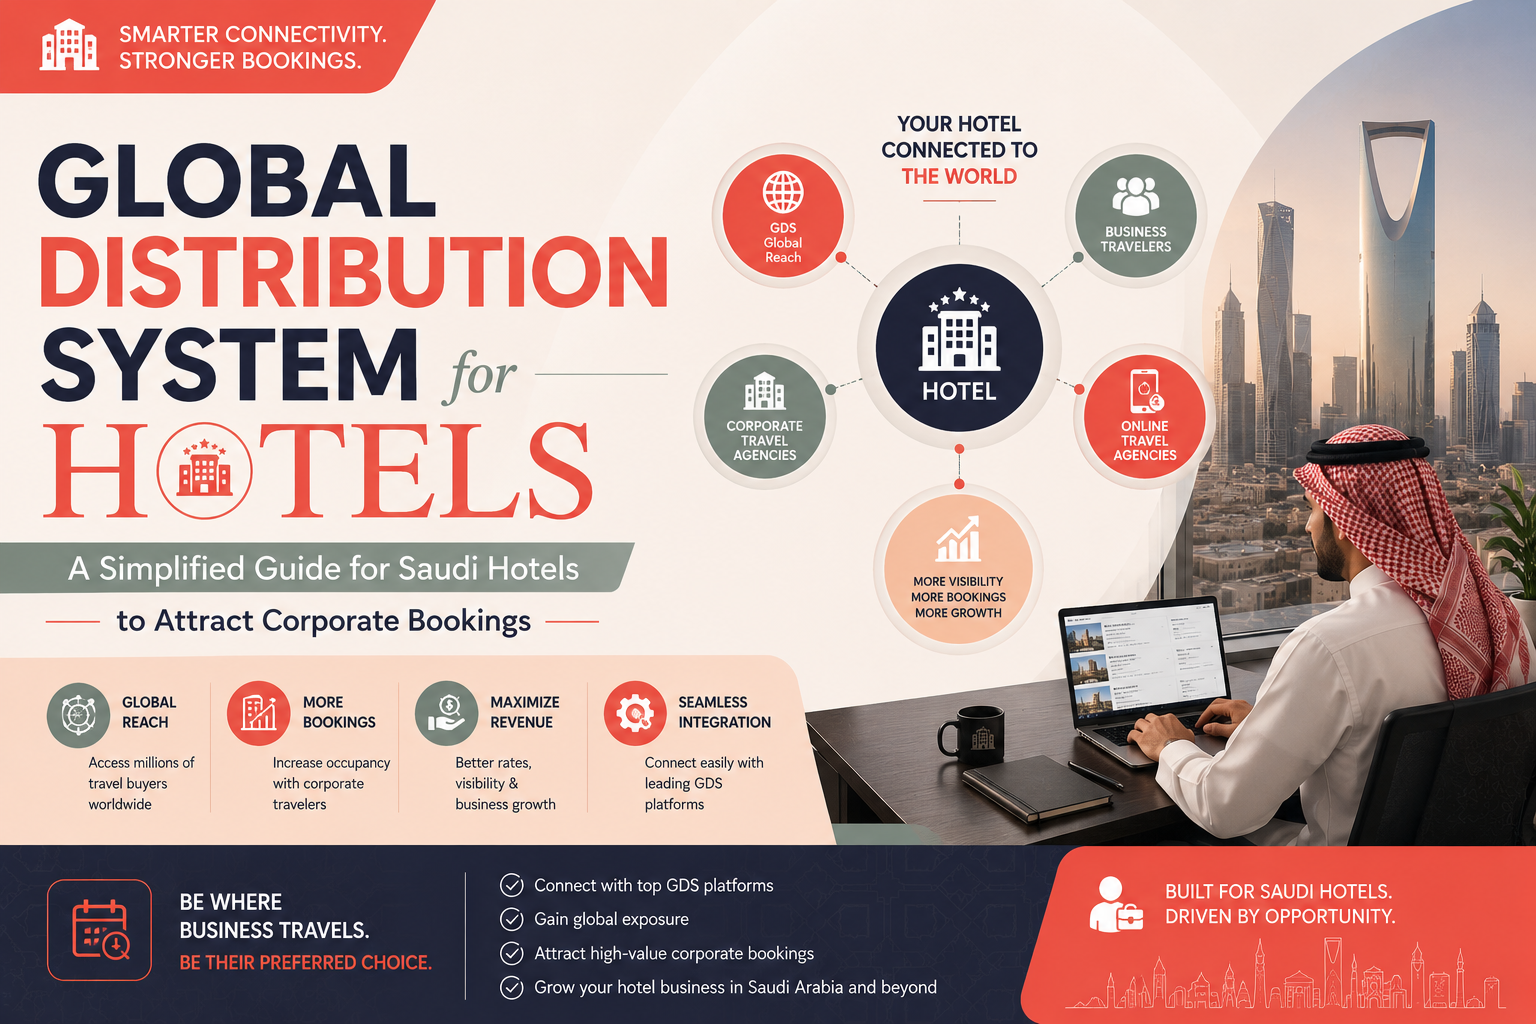
Discover how Saudi hotels in Riyadh, Jeddah, Dammam, and beyond can use a Global Distribution System (GDS) to attract corporate bookings, increase weekday occupancy, and balance distribution channels....
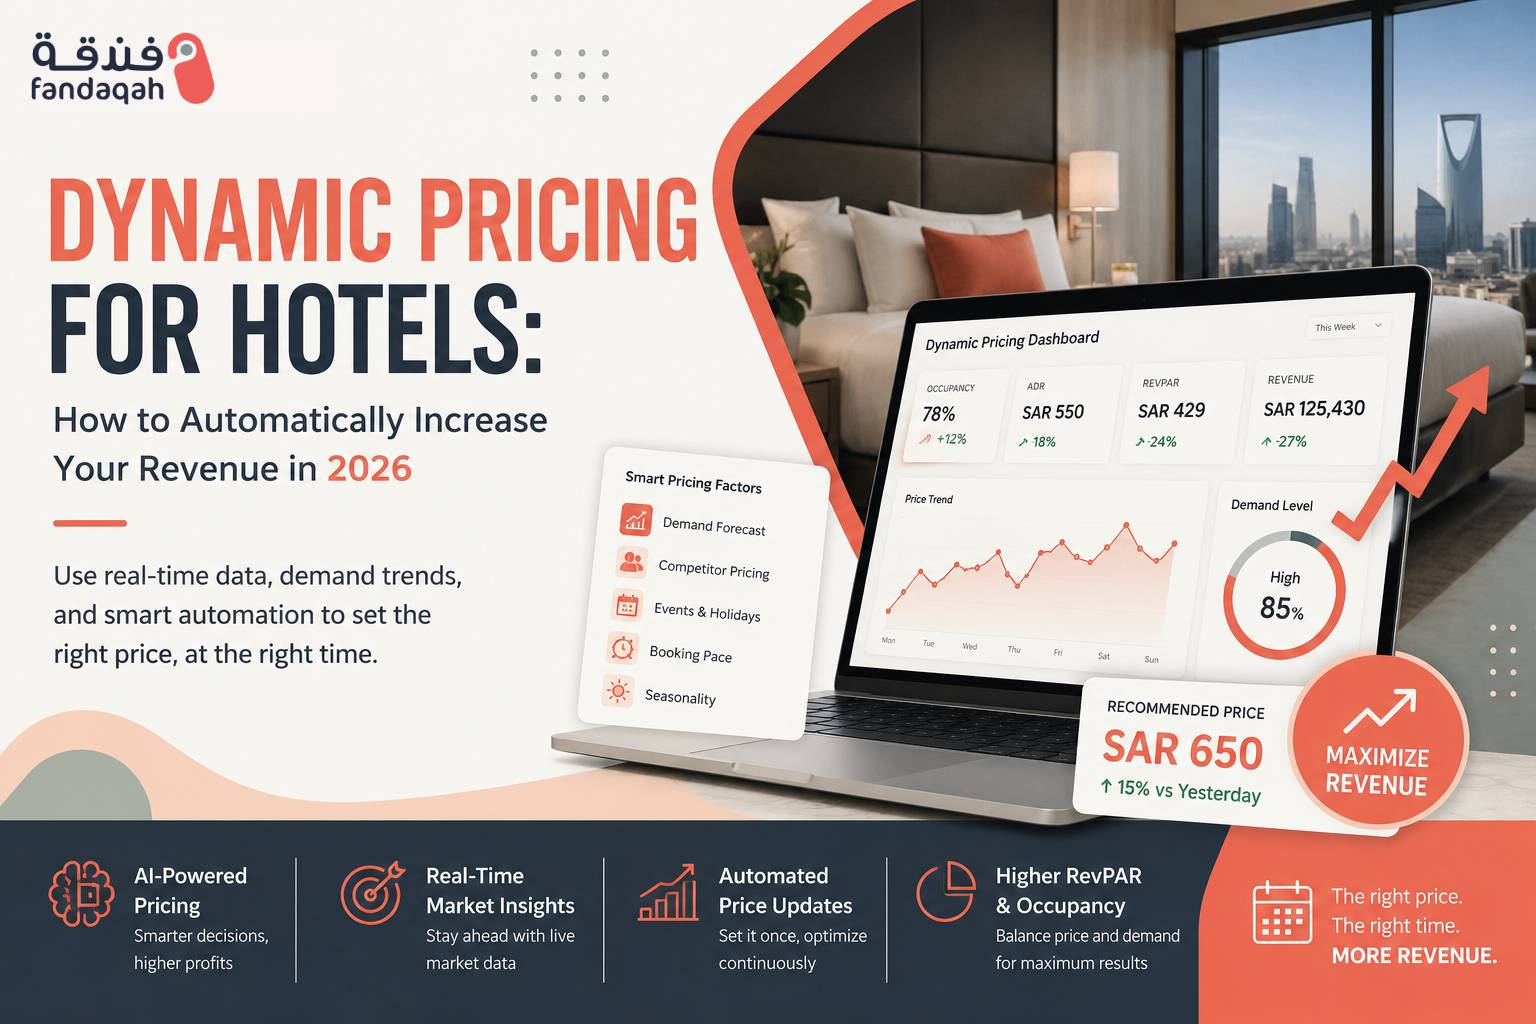
Learn how dynamic pricing uses AI to automatically adjust hotel room rates in real-time. Maximize RevPAR during Hajj, Riyadh Season & Vision 2030 projects with proven strategies for Saudi hotels....
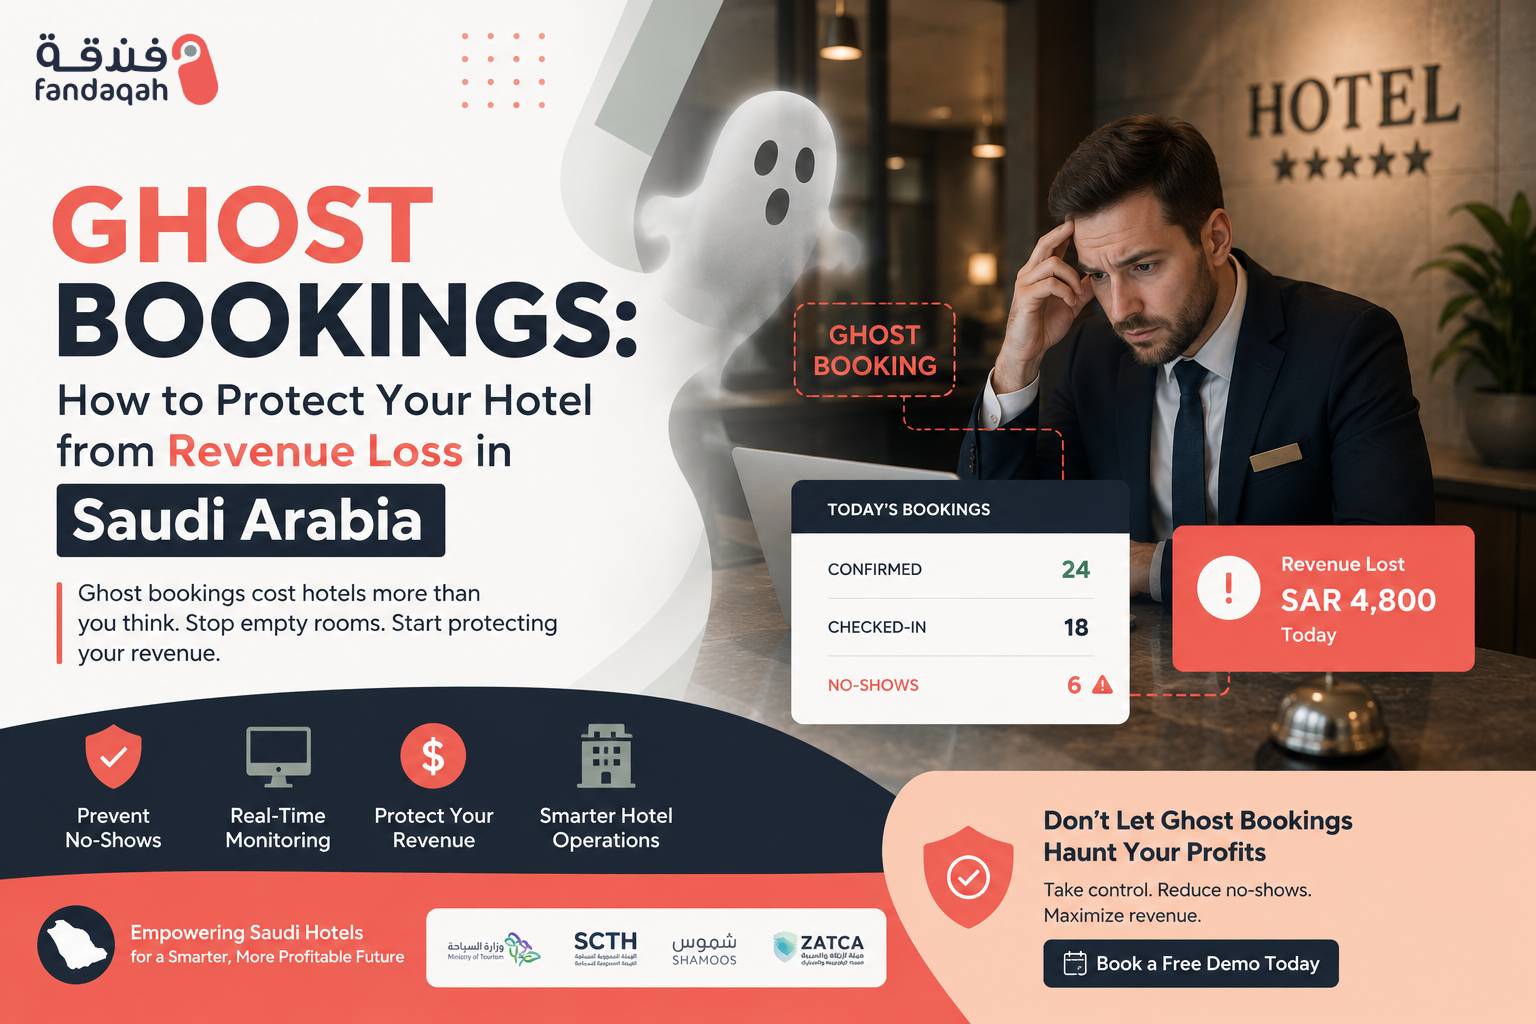
Discover what ghost bookings are, how they silently drain hotel revenue in Saudi Arabia, and practical strategies to prevent them — especially during Hajj, Umrah, and Riyadh Season — in line with ...
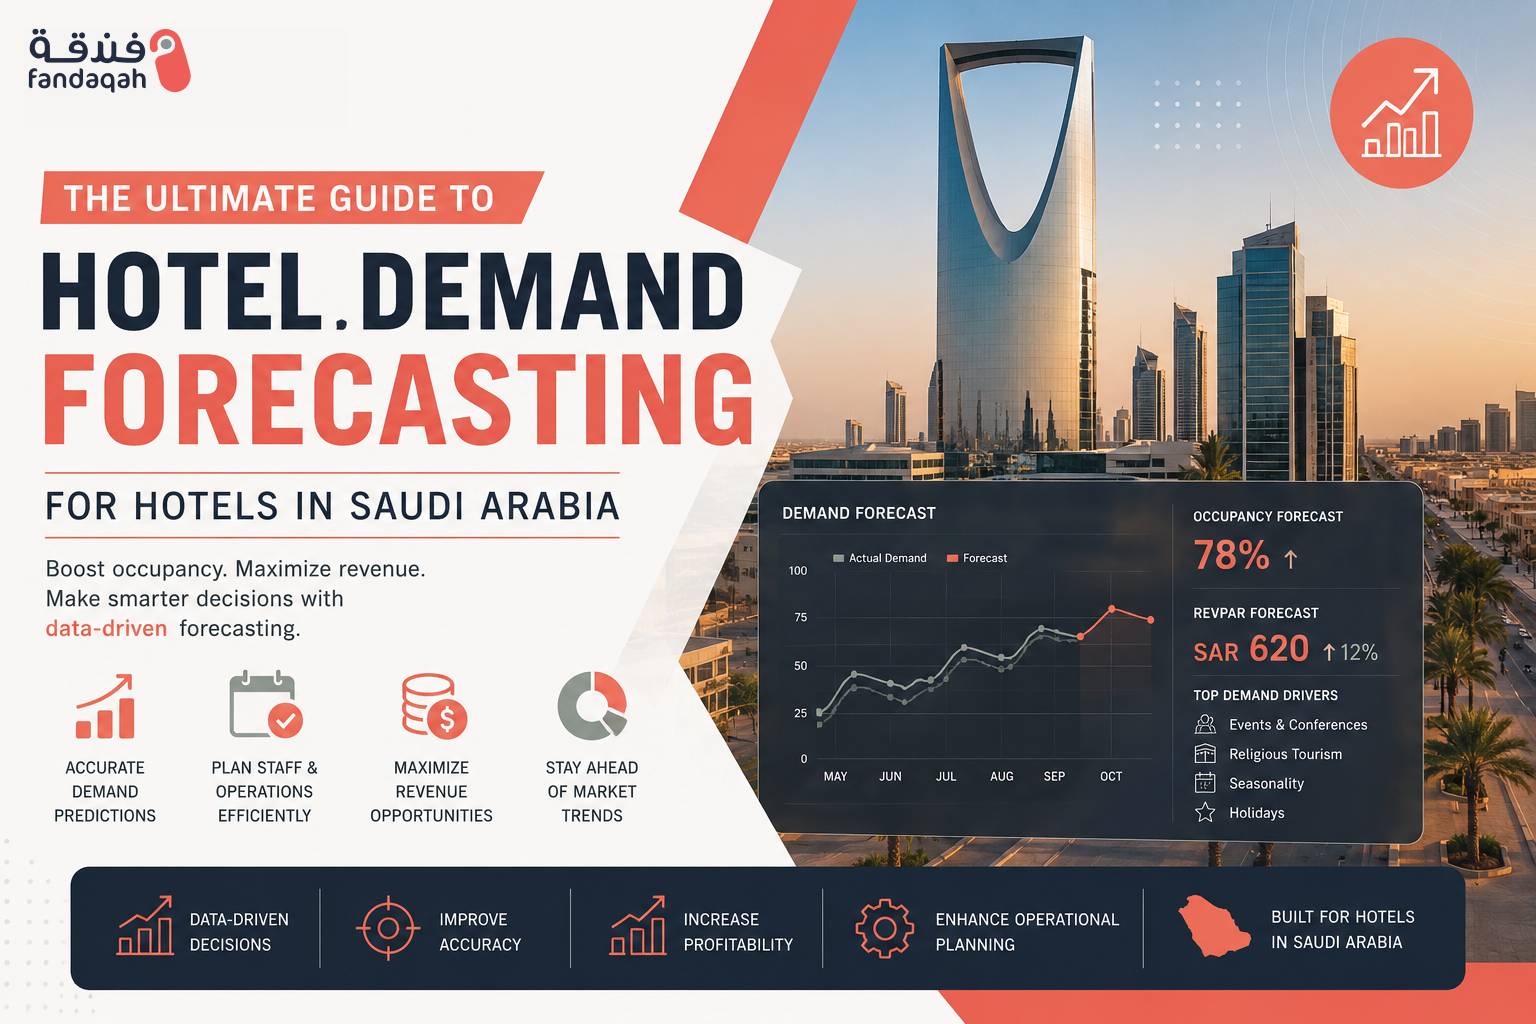
Discover the ultimate guide to hotel demand forecasting in Saudi Arabia. Learn smart strategies for dynamic pricing, revenue management, and maximizing occupancy during Hajj, Vision 2030 events, and p...
Discover how to choose the best Revenue Management System (RMS) for your Saudi hotel. Expert tips on dynamic pricing, forecasting, integrations, and maximizing RevPAR in line with Vision 2030....
Discover how Arab tourists, especially Saudis, are using AI tools like ChatGPT and Gemini to book hotels. Essential strategies for Saudi hoteliers to optimize for AI discovery and thrive under Vision ...
Discover the key difference between hotel automation and true autonomy. Learn how Saudi hotels can embrace AI-driven autonomous operations aligned with Vision 2030 for superior guest experiences and e...
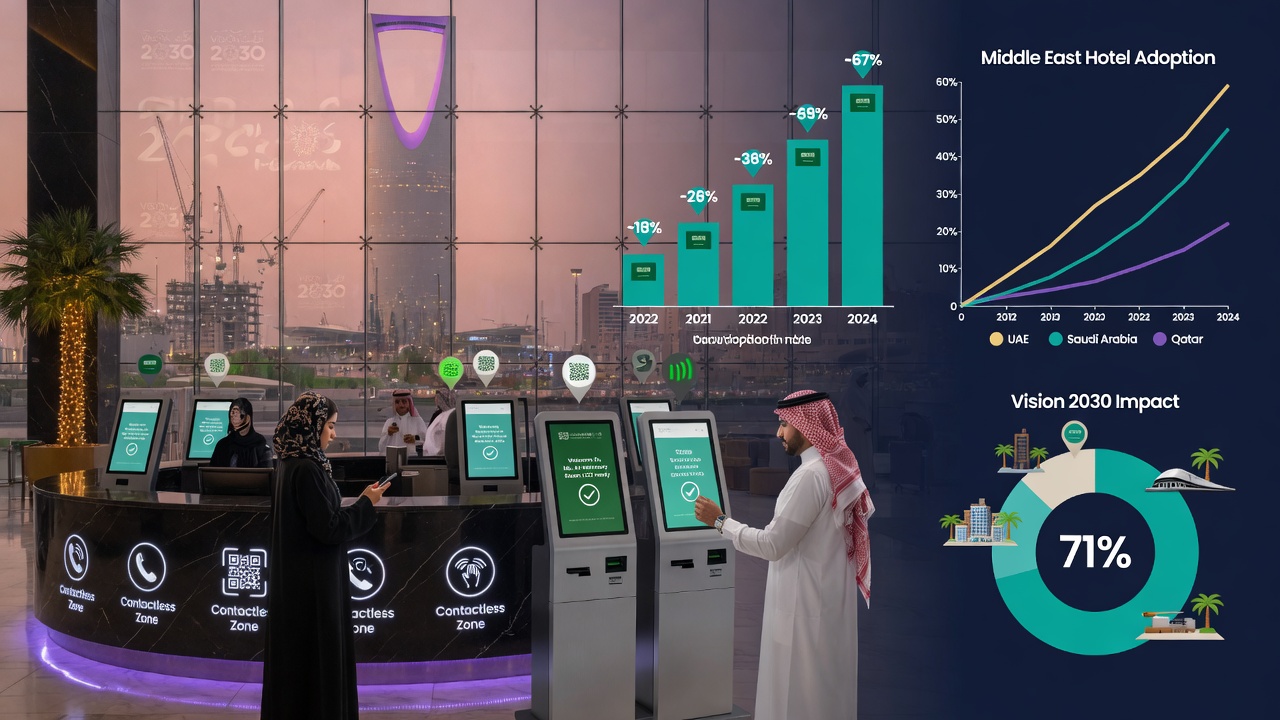
Fast-rising contactless check-in in Middle East hotels 2026. Saudi adoption at 68% thanks to Vision 2030. Benefits, cases & tips for hotel owners....
Discover the best free and affordable hotel PMS tools for 2026 in Saudi Arabia. Features ZATCA e-invoicing, channel manager, and Arabic support for budget hotels....
Complete guide to hotel distribution channels in the Arab world. Optimize OTAs, direct bookings, GDS & metasearch for Saudi hotels to grow revenue with Vision 2030 strategies....
Explore how modern unified payment platforms are simplifying cross-border hotel payments in the GCC. Saudi hotels can now achieve same-day settlements, multi-currency support, reduced fees, automated ...
Master Google Hotel Ads for Saudi hotels in 2026. Optimize your metasearch strategy to drive direct bookings, reduce OTA commissions, and leverage Vision 2030 tourism growth....
Compare Cloudbeds, Mews and Fandaqah PMS platforms for Saudi hotels in 2026. See which system wins on Arabic support, local payments (Mada/STC Pay), Hajj/Umrah peak handling, Vision 2030 readiness and...
Discover how to design a hotel loyalty program with reward points in Saudi Arabia. Boost guest retention, align with Vision 2030, and keep guests returning....
Discover the 12 essential questions Saudi hotels must ask before choosing a Hotel Management System (PMS), including ZATCA compliance, cloud PMS, and Hajj & Umrah operations....
Discover the best hotel management software for 2026 in Saudi Arabia. Compare features, pricing, ZATCA e-invoicing, and Vision 2030 readiness. Free consultation....
Discover how a serviced apartments operations program streamlines hospitality management in Saudi Arabia. Features, benefits & Vision 2030 insights inside....
Discover how hotel apartment software in Saudi Arabia automates accounting, boosts occupancy, ensures ZATCA compliance, and aligns with Vision 2030....
Discover how a hotel operating program (PMS) can streamline operations, boost revenue, and delight guests in Saudi Arabia's tourism sector....
Discover how serviced apartment management software streamlines Saudi hospitality, ensures Taskeen compliance, and boosts revenue. Complete guide....
Discover the best hotel software and PMS in Saudi Arabia. Our ultimate guide covers features, ZATCA compliance, Vision 2030 trends, and top picks for hotels of all sizes....
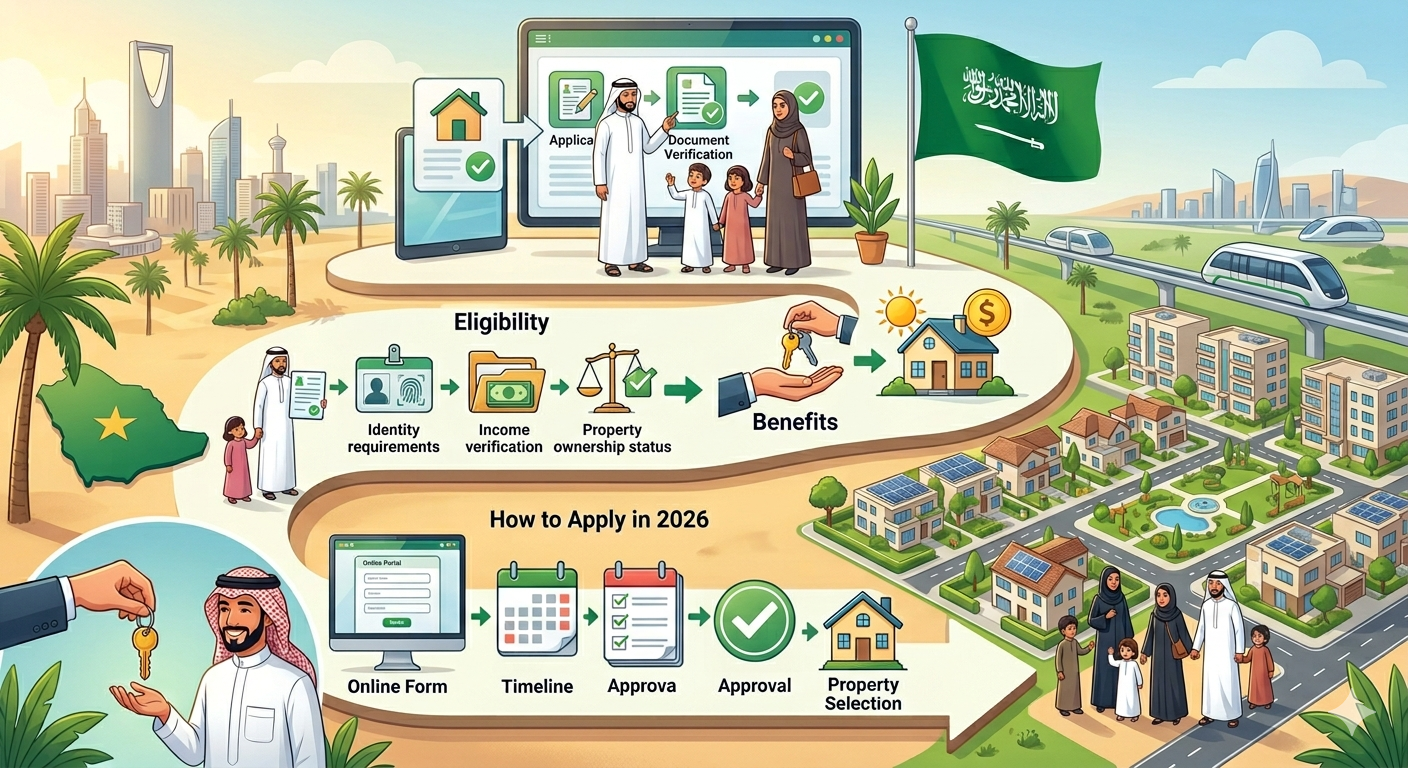
Discover Saudi Arabia’s Housing Allocation Program for government employees: eligibility, Sakani application process, and Vision 2030 homeownership goals in 2026....
Explore the best placement program for strategic talent deployment in KSA. Achieve Vision 2030 goals, enhance Saudization, streamline HR placement. Your guide....
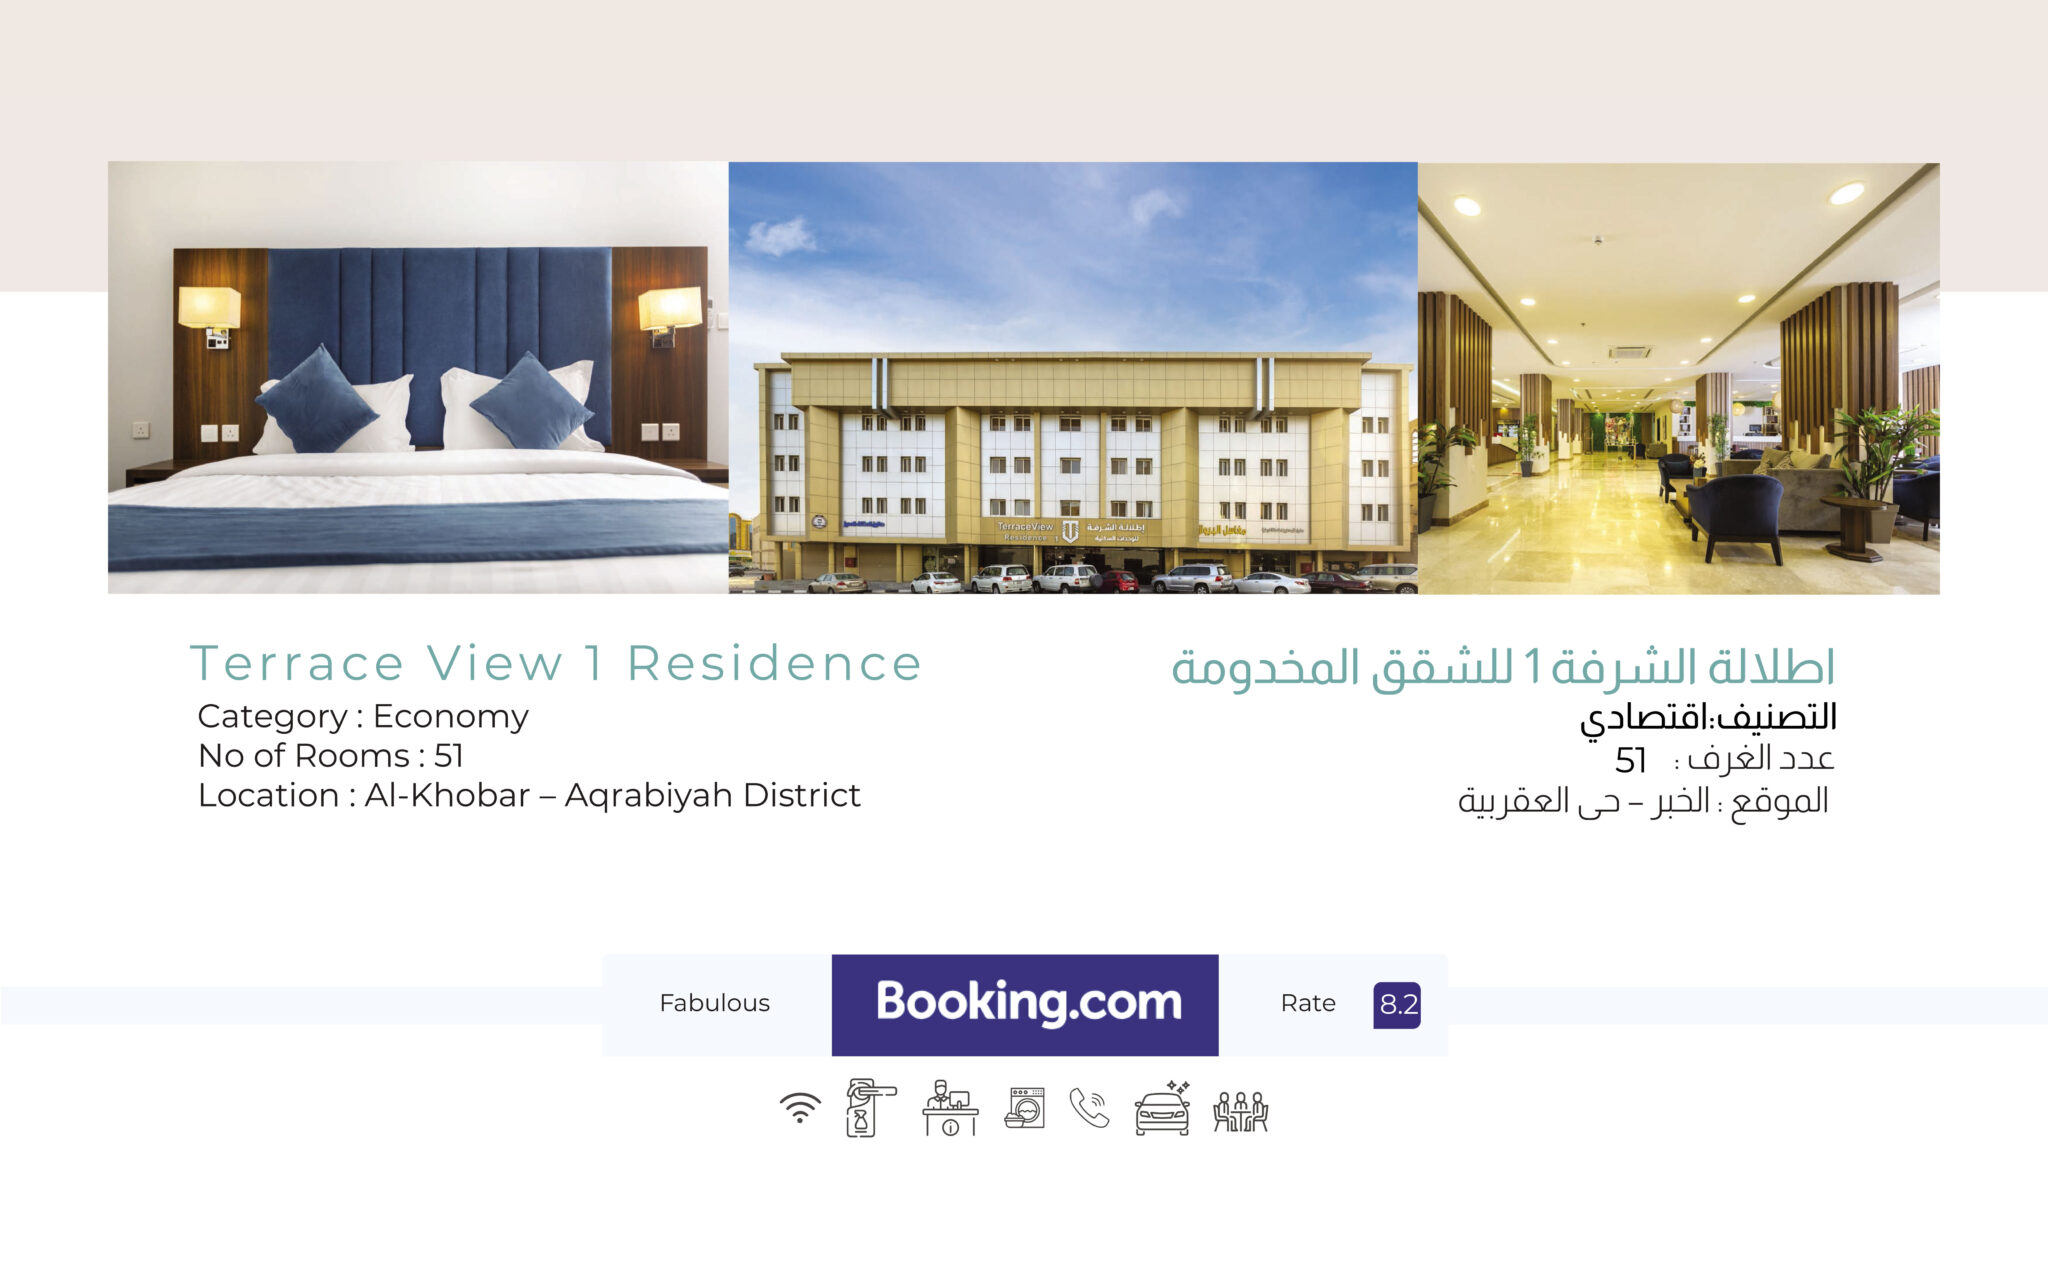
Terrace View 1 Residence, a cozy economy-class serviced apartment in Al-Khobar, faced operational hurdles that many growing hotels and apartments encounter: ...
Eco-Friendly Hotel in Saudi Arabia: Sustainability Guide for Vision 2030. Learn energy, water and waste savings to lower costs and attract eco guests with Fandaqah....
Learn how Saudi hotels can attract MICE tourism with event-ready facilities, smart marketing, group booking tools, and ZATCA-compliant operations....
Discover key principles of scalable hotel digital transformation for Saudi hotels, including cloud PMS, automation, ZATCA compliance, and guest experience....
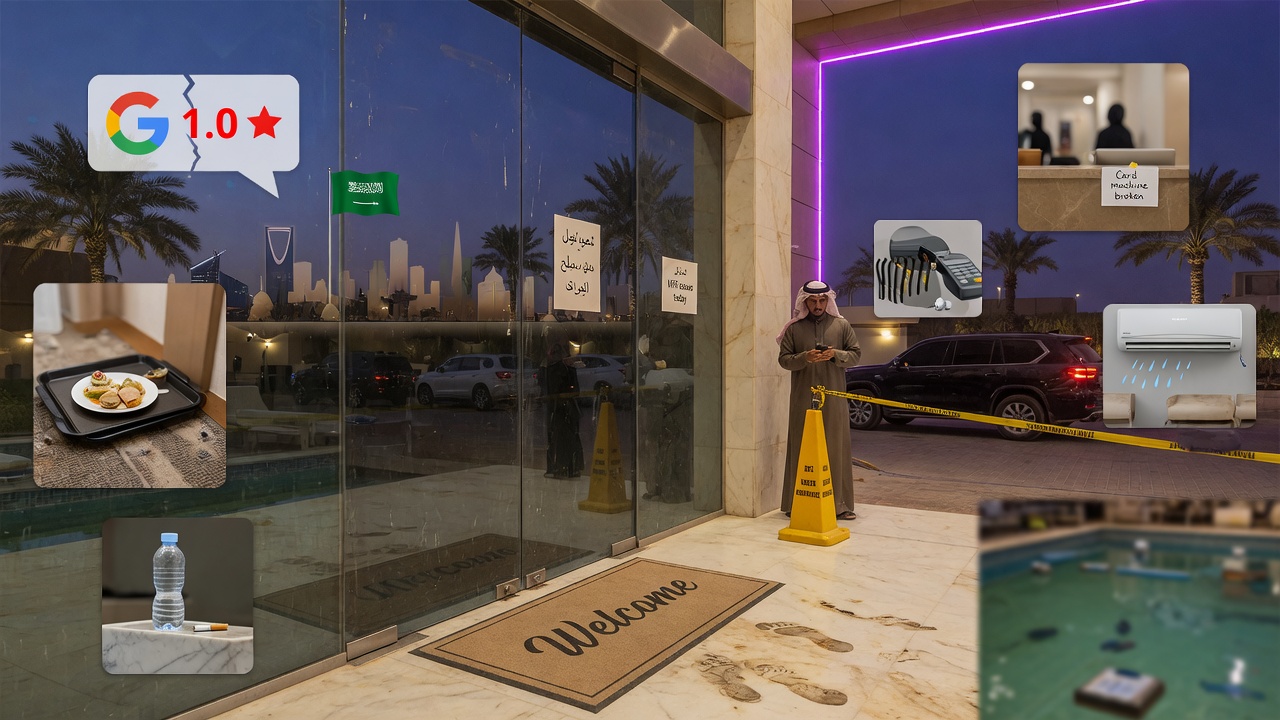
7 friction points killing hotel Google ratings in Riyadh & Jeddah. Fix check-in, cleanliness, communication, noise, fees & tech to boost ratings & bookings....
Discover how guest personalization turns Saudi hotel visitors into loyal advocates. Learn strategies for tailored experiences and loyalty programs....
Complete guide to Personal Data Protection Law compliance for Saudi hospitality. Practical steps to protect guest data, build trust, and meet SDAIA requirements under Vision 2030...
Discover how to stop revenue leakage in Saudi hotels from tax, VAT, and service charge errors. Cloud PMS ensures ZATCA compliance and protects profitability....
Discover how staycation marketing helps Saudi hotels attract local residents and fill empty weeks. Actionable strategies for year-round occupancy....
Learn how Saudi hotels can win corporate RFPs and secure business travel bookings. Strategies for rates, PMS billing, and contract negotiation....
Increase hotel bookings & iftar sales during Ramadan 2026 in Saudi Arabia with targeted marketing strategies, iftar packages, Ramadan tents, and PMS automation....
Learn how WhatsApp Business enhances guest communication and direct bookings for Saudi hotels. Discover strategies, automation & Vision 2030 alignment....
Discover how to choose the best hotel channel manager for Saudi Arabia's hospitality sector in 2026. Boost occupancy, sync rates, and maximize revenue with our complete guide....
Guide to hotel sales manager skills, tools & strategies for corporate and pilgrimage sales in Saudi Arabia. Win with Vision 2030....
Learn to implement self-service & digital check-in in Saudi hotels seamlessly. Align with Vision 2030, cut wait times by 70%, and enhance guest experience....
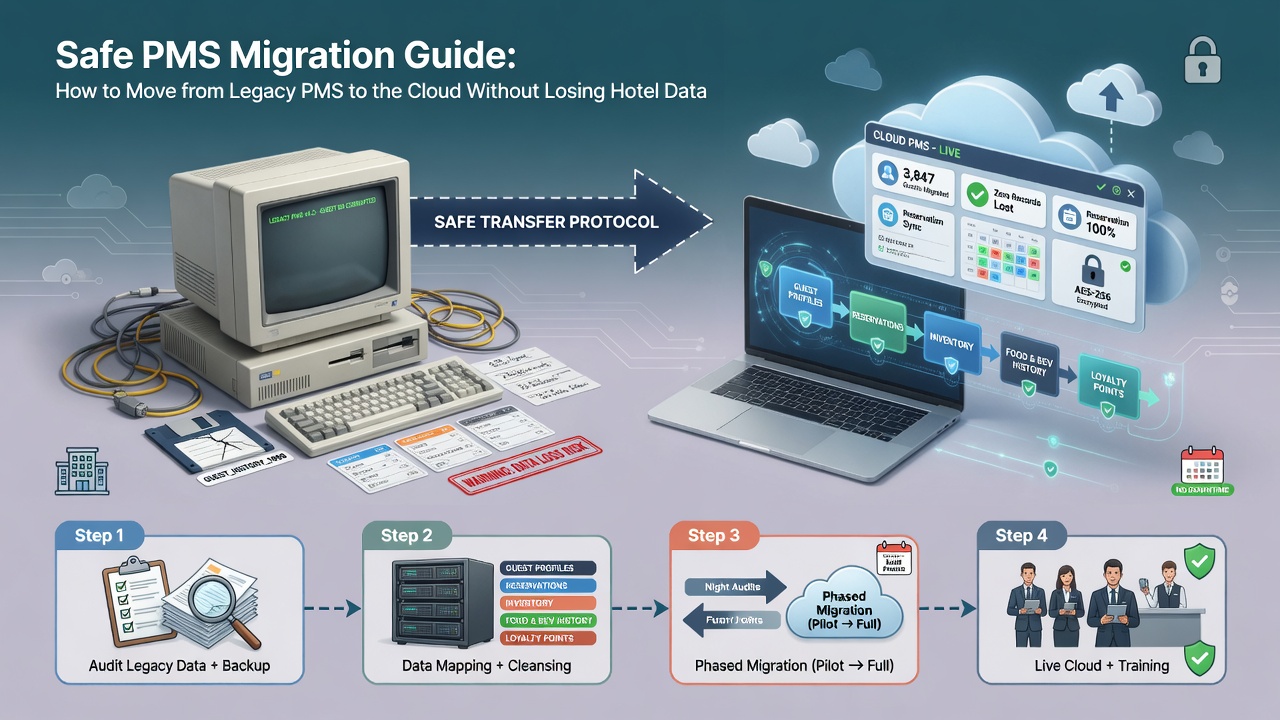
Step-by-step guide for Saudi hotels to safely migrate from legacy PMS to cloud. Protect guest data, reservations & finances. Learn best practices, avoid data loss...
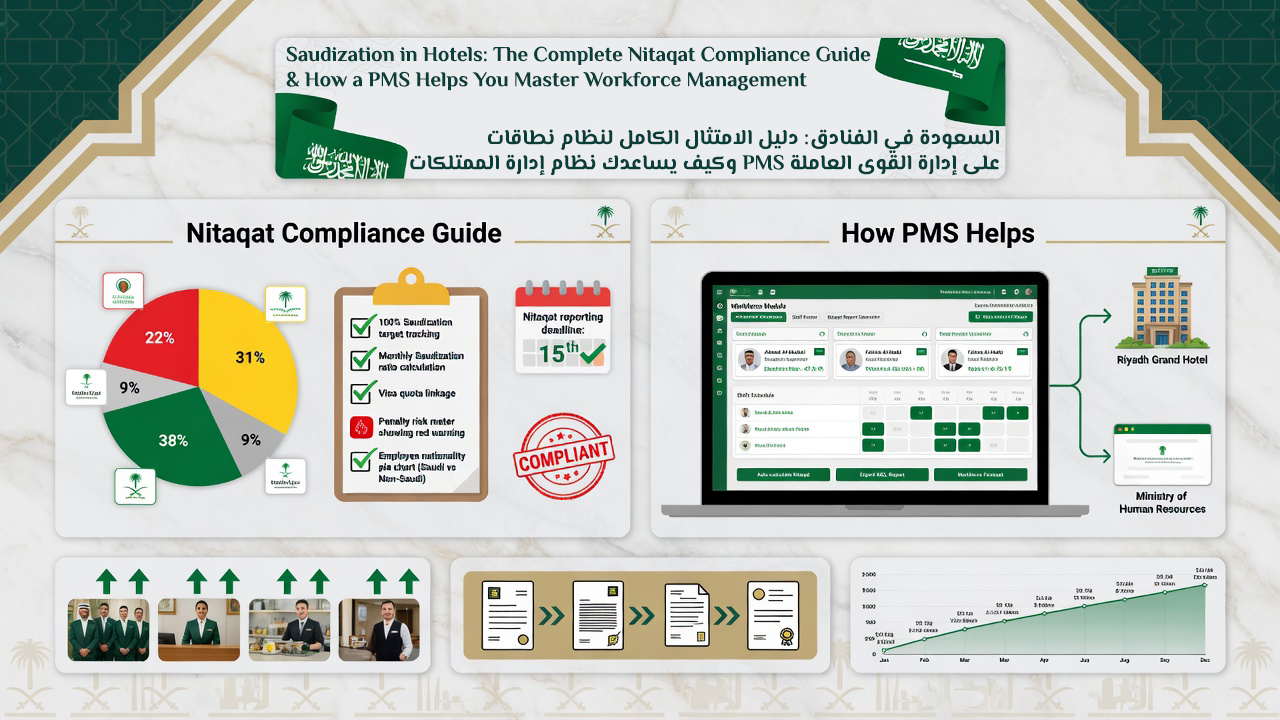
Complete guide to Saudization in hotels & Nitaqat compliance in KSA. Learn how a PMS helps manage workforce, achieve green band status, and avoid penalties. ...
Master connecting hotel restaurant, café, and room service billing with your PMS — ZATCA-compliant, Mada, STC Pay ready. Guide for Saudi hotels Vision 2030....
Discover the best hotel PMS for serviced apartments and chalets in Saudi Arabia. Streamline operations, boost direct bookings, and ensure Shomoos compliance in 2026....
Compare top Saudi hotel payment gateways with Mada & STC Pay. Boost direct bookings with SAMA-compliant, ZATCA-ready solutions like HyperPay, PayTabs....
Streamline Umrah & Hajj pilgrim stays with automation. Bulk check‑ins, prayer‑aware services, Nusuk integration & Vision 2030 compliance for Saudi hotels....
Master cash flow management for small hotels in Saudi Arabia. Our 2026 guide covers seasonal planning, cost control, and profit optimization....
Safeguard guest data in Saudi hotels with our expert guide covering NCA, PDPL, PCI DSS compliance, ransomware prevention, and cybersecurity best practices....
Learn how to increase direct hotel bookings in Saudi Arabia, cut OTA commissions, and boost profit with direct booking engine, loyalty program & best-rate....
Discover how Cloud PMS technology accelerates Saudi Vision 2030 tourism goals. Improve hotel efficiency and guest experience with digital transformation in KSA....
Learn how AI in Saudi hotels boosts revenue through dynamic pricing, chatbots, and guest personalization. Start your smart hospitality transformation....
Master seasonal demand in Saudi Arabia. Learn how to optimize hotel revenue during Hajj and Umrah using automated PMS, dynamic pricing, and channel managers...
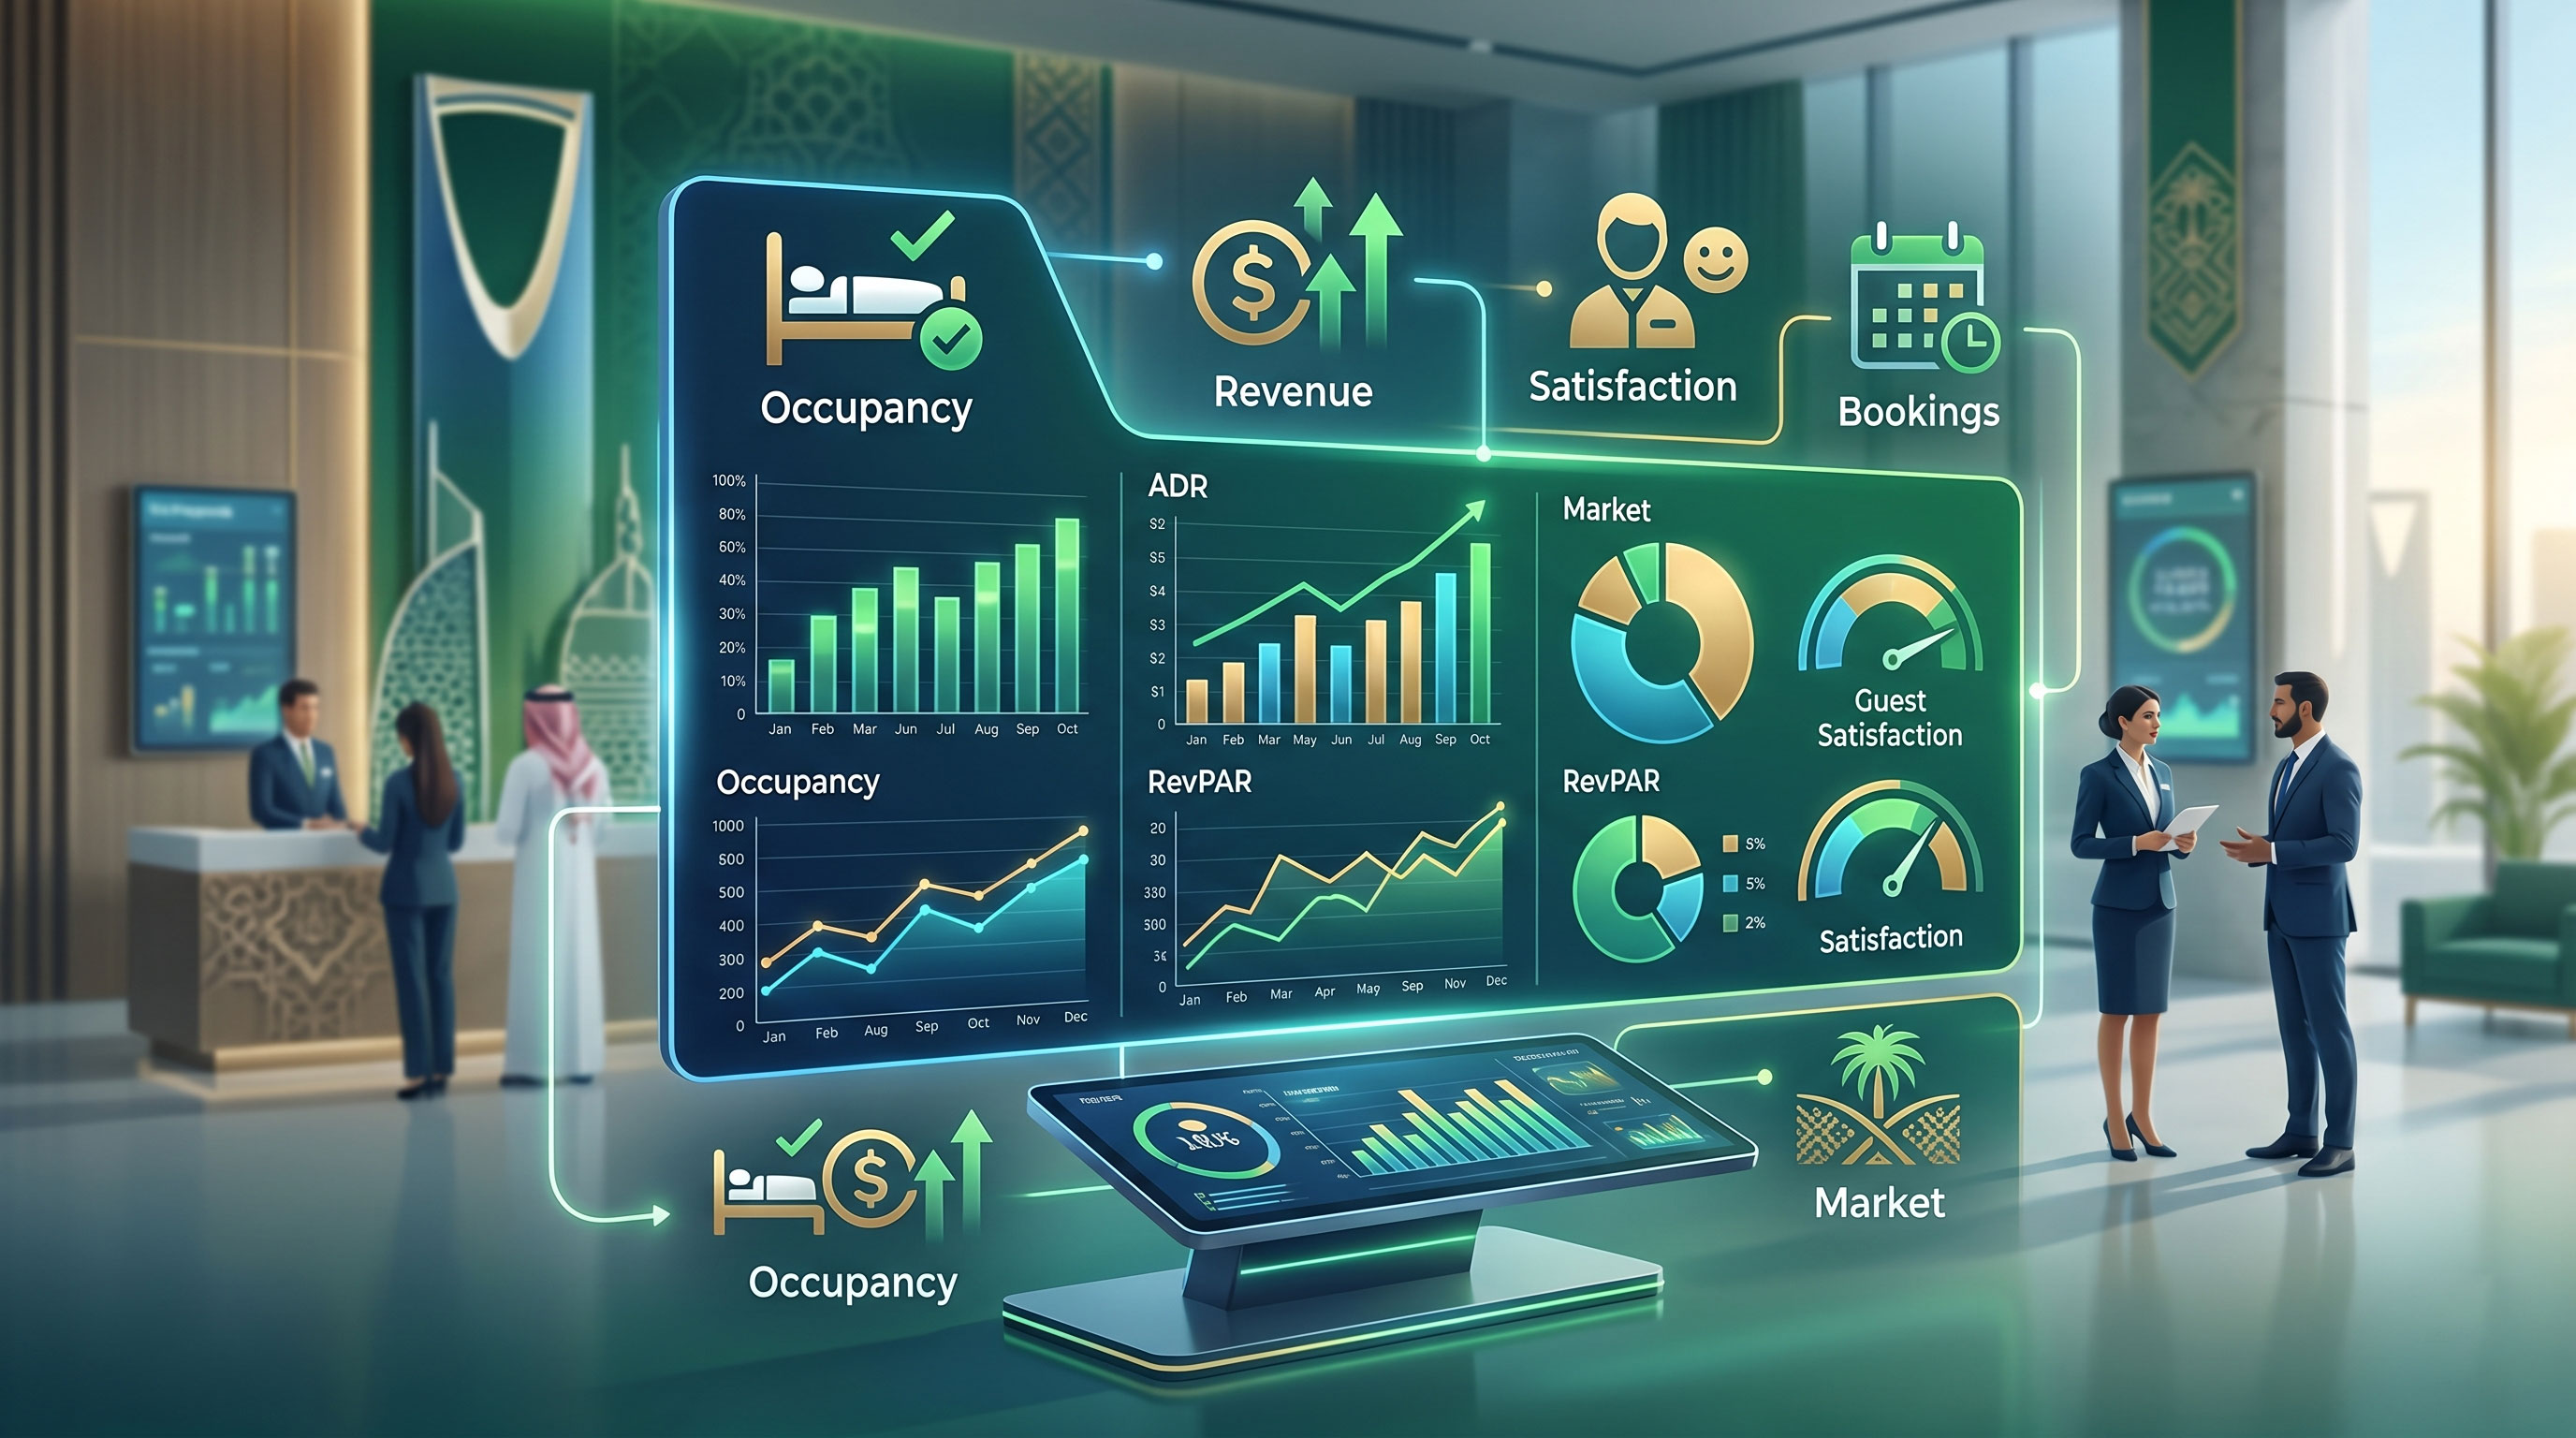
Discover essential daily KPIs every hotel owner in Saudi Arabia should track with a BI dashboard. Boost RevPAR, compliance, and profit with data-driven insights....
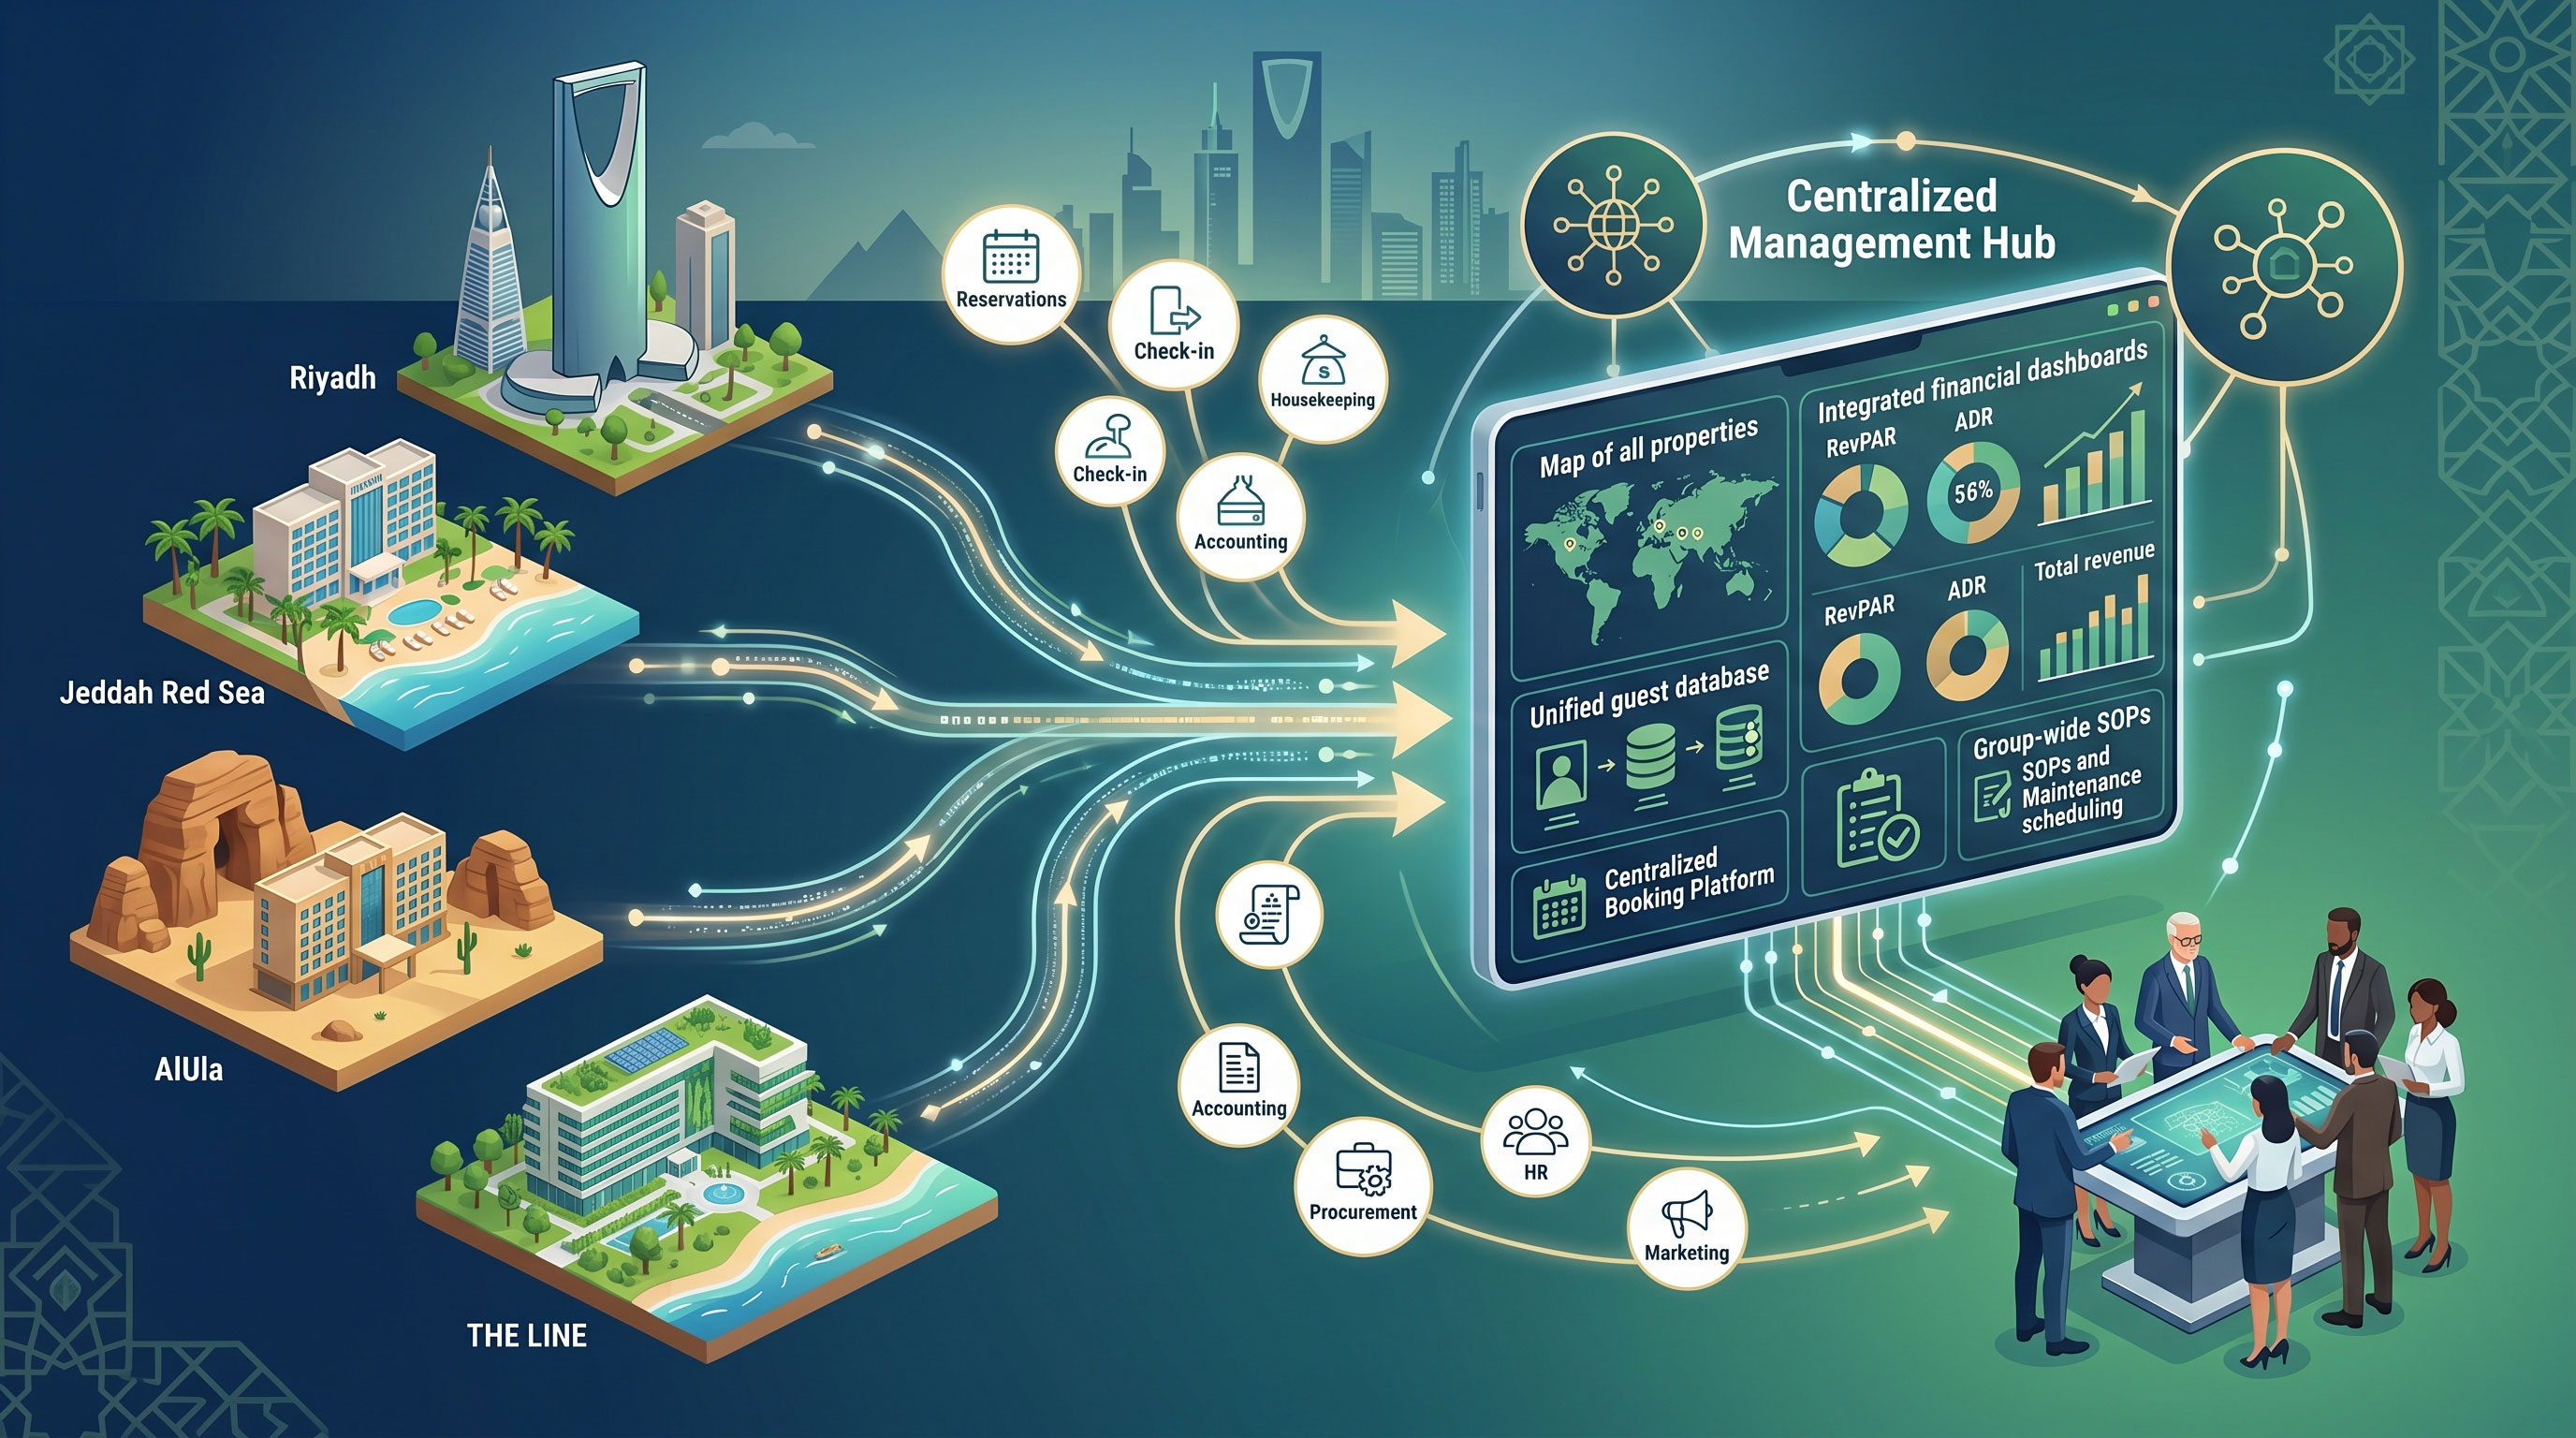
Centralize hotel operations in Saudi Arabia: multi-property management, unified reporting, revenue optimization, procurement, HR, and ZATCA compliance for Vision 2030 growth....
Compare what Saudi hotels need in 2026: cloud PMS, ZATCA e-invoicing, Shomoos, Ministry of Tourism, channel manager, booking engine, automation, and guest management....
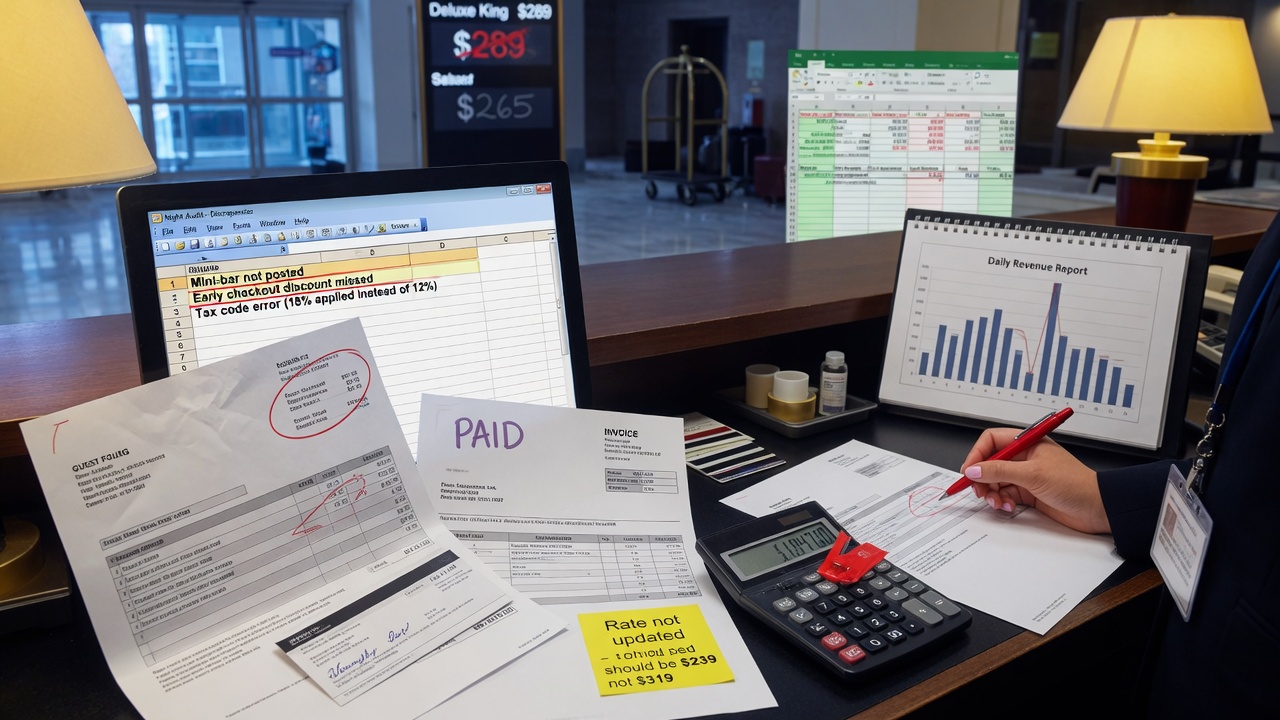
Top common hotel billing errors in Saudi hotels cost SAR 100K+ yearly via VAT & fee mistakes. Stop leakage with ZATCA PMS automation now....
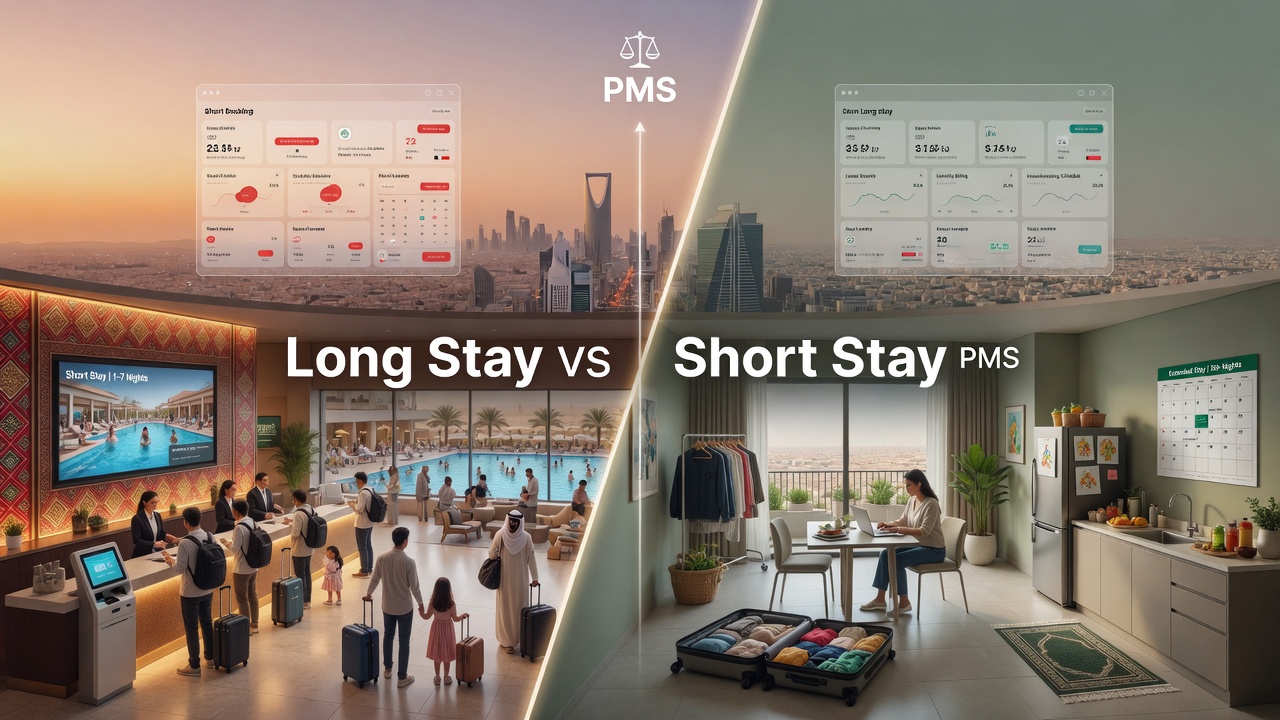
Compare long stay vs short stay PMS for Saudi hospitality. Learn key differences, must‑have features, Ejar compliance, and Vision 2030 insights...
Compare what Saudi hotels need in 2026: cloud PMS, ZATCA e-invoicing, Shomoos, Ministry of Tourism, channel manager, booking engine, automation, and guest management....
Discover why hotel data management is essential for Saudi hotels. Learn how to leverage guest insights, ensure ZATCA & Shomoos compliance, and boost revenue with a modern PMS. Free demo from Fandaqah...
Vision 2030 is transforming vacation ownership in Saudi Arabia. Explore the hotel meets residential trend at Red Sea Global and NEOM for families and investors....
Saudi Arabia hotel keyless entry under Vision 2030: mobile keys, biometrics, guest benefits, hotel savings, Mövenpick Riyadh and Red Sea Global case studies....
Legacy PMS is silently costing Saudi hotels guests, direct bookings, and revenue through slow operations, poor personalization, and lost opportunities. Discover the true hidden costs of outdated hotel...
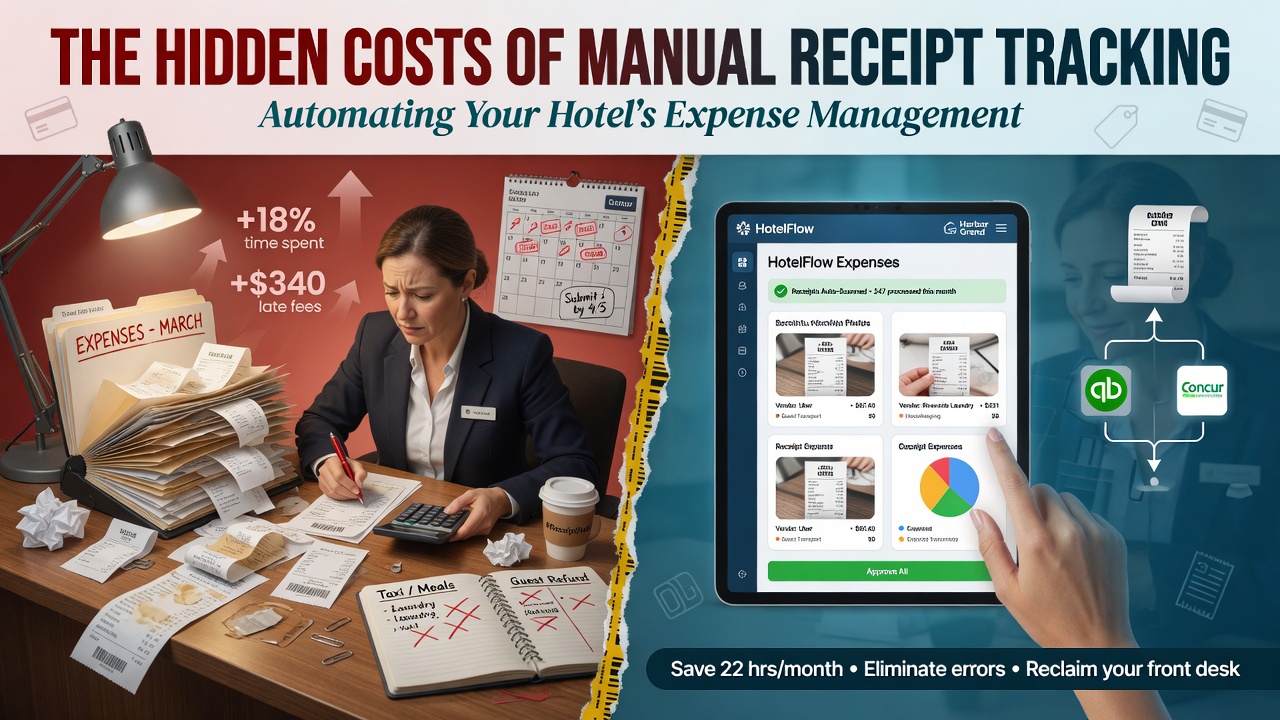
Saudi hotels lose tens of thousands of SAR yearly on manual receipt tracking. Discover hidden costs — wasted labor, VAT leakage, fraud & ZATCA risks — and how automated expense management software...
Discover how AI, IoT, and smart building tech are driving sustainable hotel operations in Saudi Arabia. Reduce costs, meet Vision 2030 goals, and enhance guest experience....
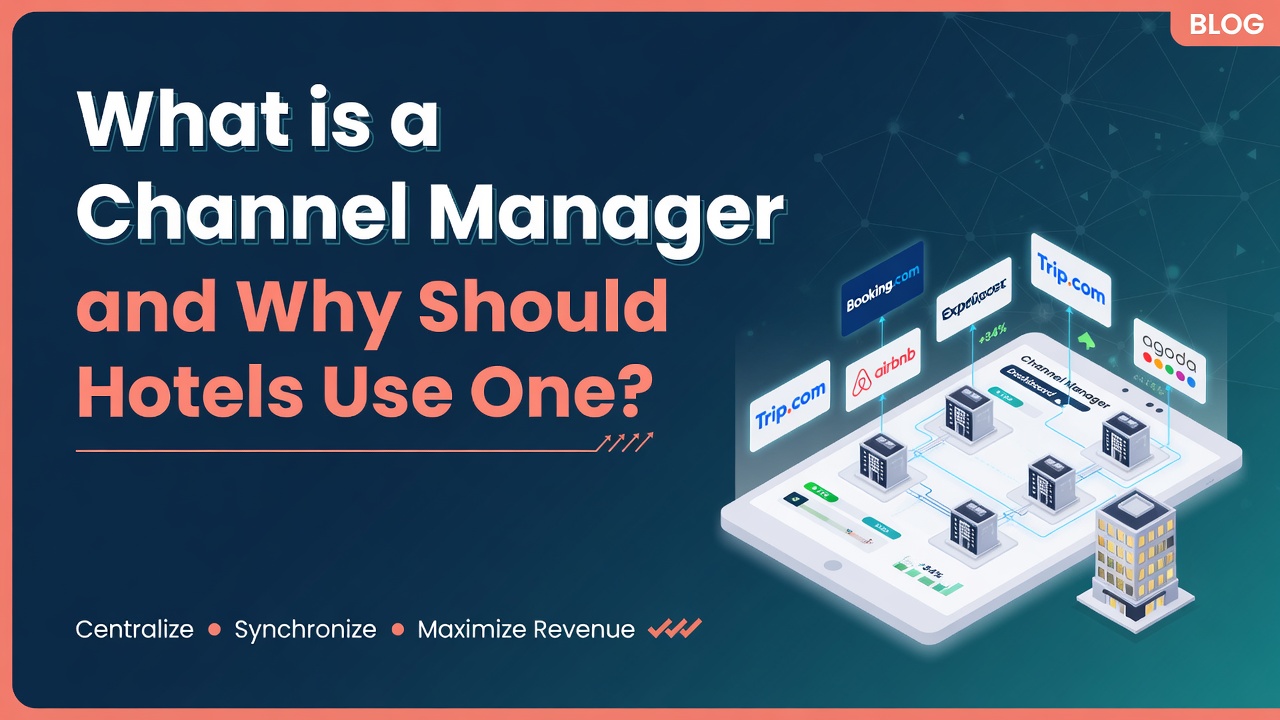
Discover what a channel manager is and why Saudi hotels need it. Automate OTA distribution, prevent overbookings, boost direct bookings, and stay compliant. Free demo from Fandaqah...

Reduce hotel check-in time from 15 minutes to under 3 minutes using automated Shomoos registration and passport scanning. Free demo for Saudi hotels...

Discover how smart room integration with hotel PMS in Saudi Arabia enhances guest experience, energy efficiency, and compliance with ZATCA & Shomoos. The future of Vision 2030 hospitality starts here....
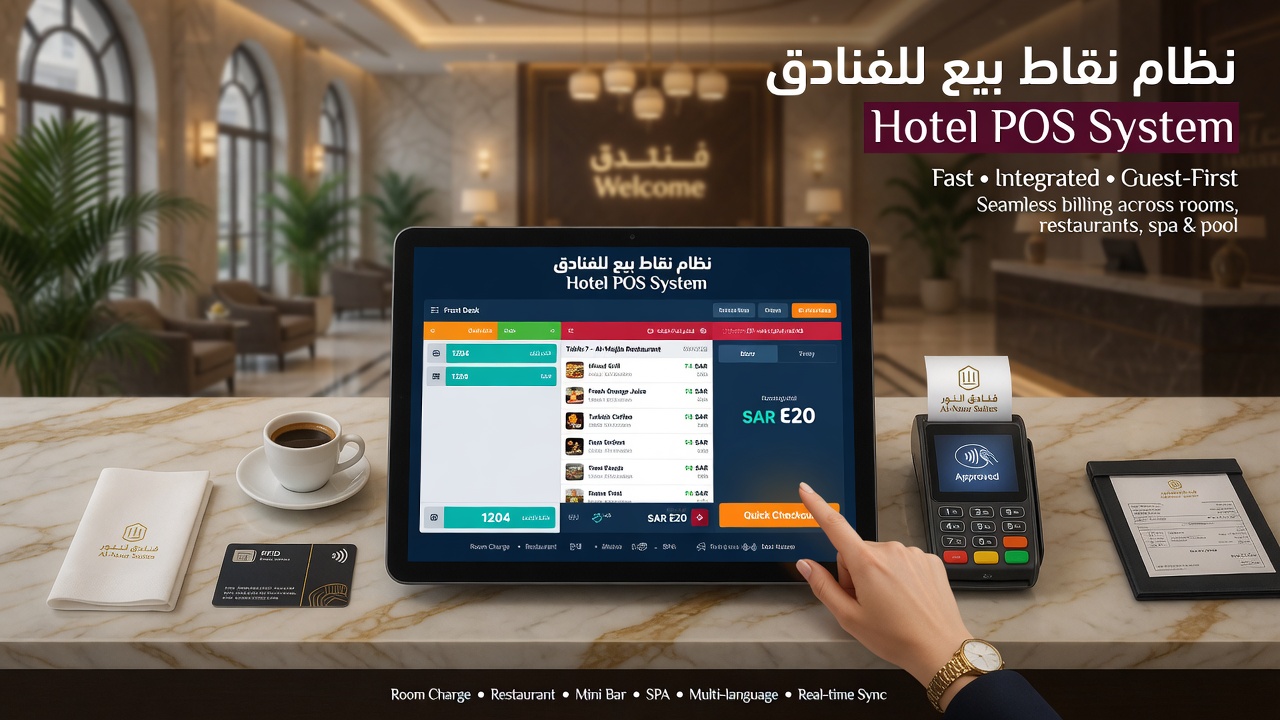
Discover why Arabic interface and POS integration are essential for hotels in Saudi Arabia. Boost staff efficiency, guest satisfaction, and compliance with Fandaqah’s all-in-one PMS...
Try Fandaqah’s 30‑day free demo account for hotel PMS in Saudi Arabia. Experience ZATCA e‑invoicing, Shomoos integration, passport scanning, and check‑in automation – risk‑free. Start your...
Discover proven strategies to avoid empty rooms during low season in Saudi Arabia. Learn dynamic pricing, direct booking tactics, and how a hotel PMS Saudi Arabia can boost occupancy year‑round. Fre...
ZATCA Phase 2 deadline for hotels: March 31, 2026. Learn Wave 23 requirements, e-invoicing integration, penalties, and how a compliant hotel PMS ensures full compliance. Free demo from Fandaqah...
Complete guide to buying a hotel PMS in Saudi Arabia. Learn key features, compliance with ZATCA & Shomoos, ROI, and how to choose the best hotel management system KSA for your property...
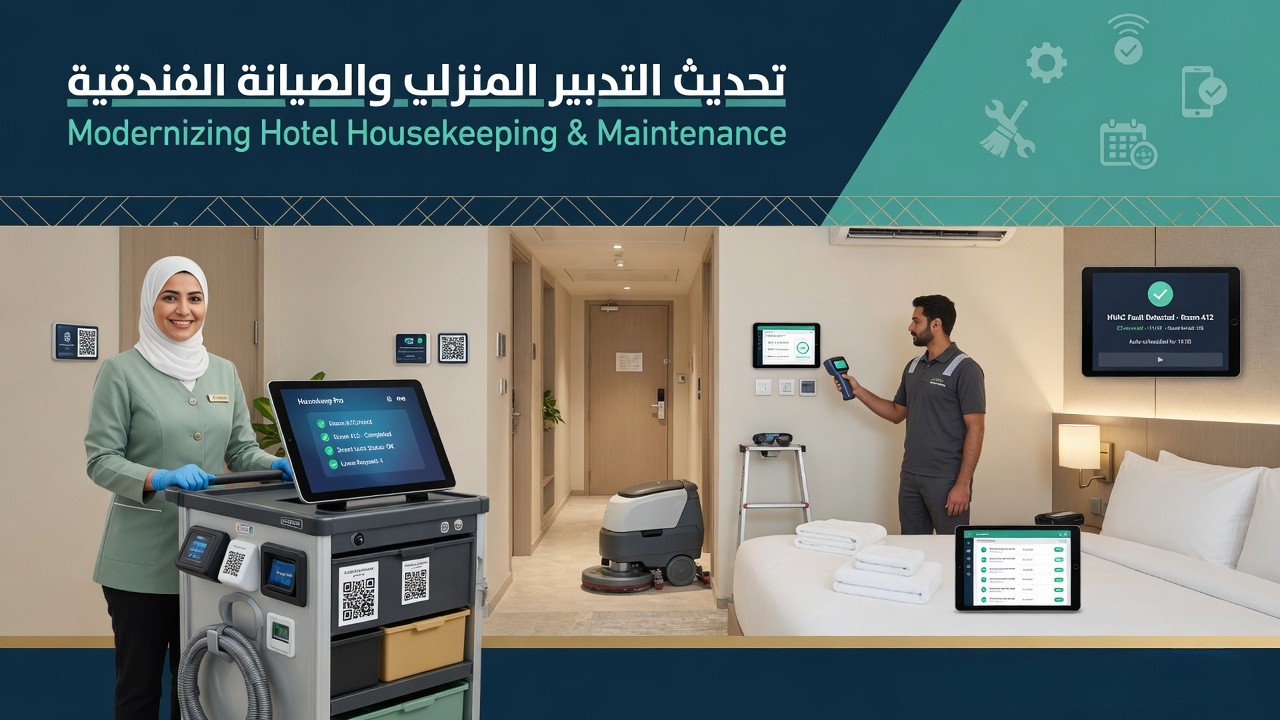
Go paperless with hotel housekeeping and maintenance. Learn how digital checklists, real‑time updates, and integrated PMS boost efficiency, guest satisfaction, and compliance in Saudi Arabia...
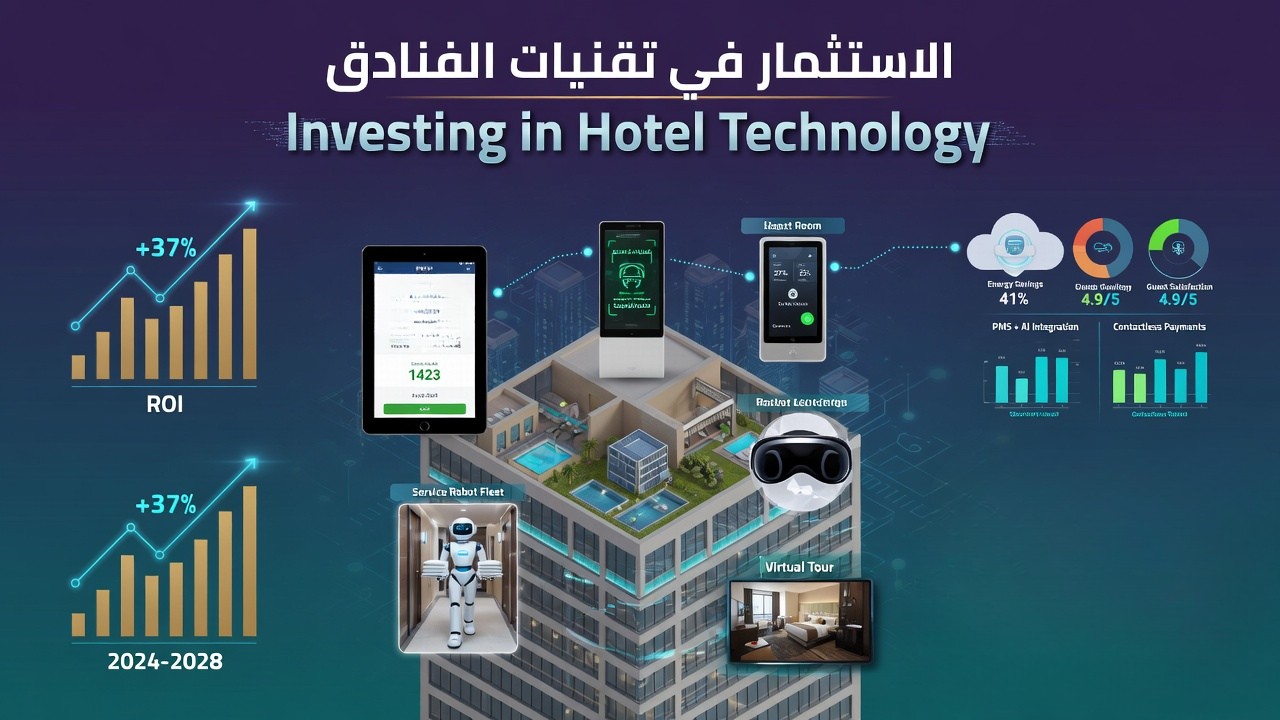
Learn how hoteliers can build a business case for new technology. Show ROI, improve guest satisfaction, and ensure ZATCA & Shomoos compliance. Free demo for Saudi hotels...
Discover how gift cards for hotels can boost occupancy, increase revenue, and attract new guests. Learn to integrate with your hotel PMS Saudi Arabia for seamless automation....
Discover proven destination marketing ideas for hotels in Saudi Arabia. Attract more guests, leverage Vision 2030, and boost direct bookings. Free consultation inside....
Hostel vs hotel – what's the difference? Compare cost, privacy, amenities, and social experience. Perfect for Saudi travelers and tourists under Vision 2030. Find your ideal stay....
Complete guide to lodging taxes for hotels in Saudi Arabia: VAT (15%), municipality fees, tourism tax, ZATCA e-invoicing compliance, and how to automate tax management. Essential for hoteliers....
Complete guide to PMS training for hotel staff in Saudi Arabia. Learn how to train your team on ZATCA e‑invoicing, Shomoos integration, passport scanning, and check‑in automation. Free demo from F...
Compare the best cloud PMS for serviced apartments in KSA: Fandaqah vs. legacy systems. Discover automation, ZATCA & Shomoos compliance, and why modern cloud PMS wins. Free demo...
Saudi Arabia’s hospitality sector is experiencing unprecedented growth, driven by Vision 2030. Success now requires more than just a prime location—it demands the smart use of hotel management too...
As part of Saudi Arabia’s digital transformation, e-invoicing has become a cornerstone in regulating the relationship between businesses and the Zakat, Tax and Customs Authority (ZATCA). With the ro...
Discover the Kingdom’s transformation through Vision 2030, where ancient spirituality meets modern adventure tourism. The Future of Hospitality Summit is driving regional change. Explore spiritual j...
Property management software Saudi Arabia by Fandaqah: ZATCA & Shomoos compliant, passport scanner, 85% faster check-in. Trusted by 850+ hotels. Demo now....
Complete guide to Shomoos and Siyaha integration for Saudi hotels. Learn how to automate guest registration, avoid fines, and streamline operations with a modern hotel PMS. Free demo from Fandaqah...
Complete guide to hotel PMS cost in Saudi Arabia. Understand pricing models, hidden fees, ZATCA & Shomoos compliance costs, and how to choose the right hotel management system KSA for your budget...
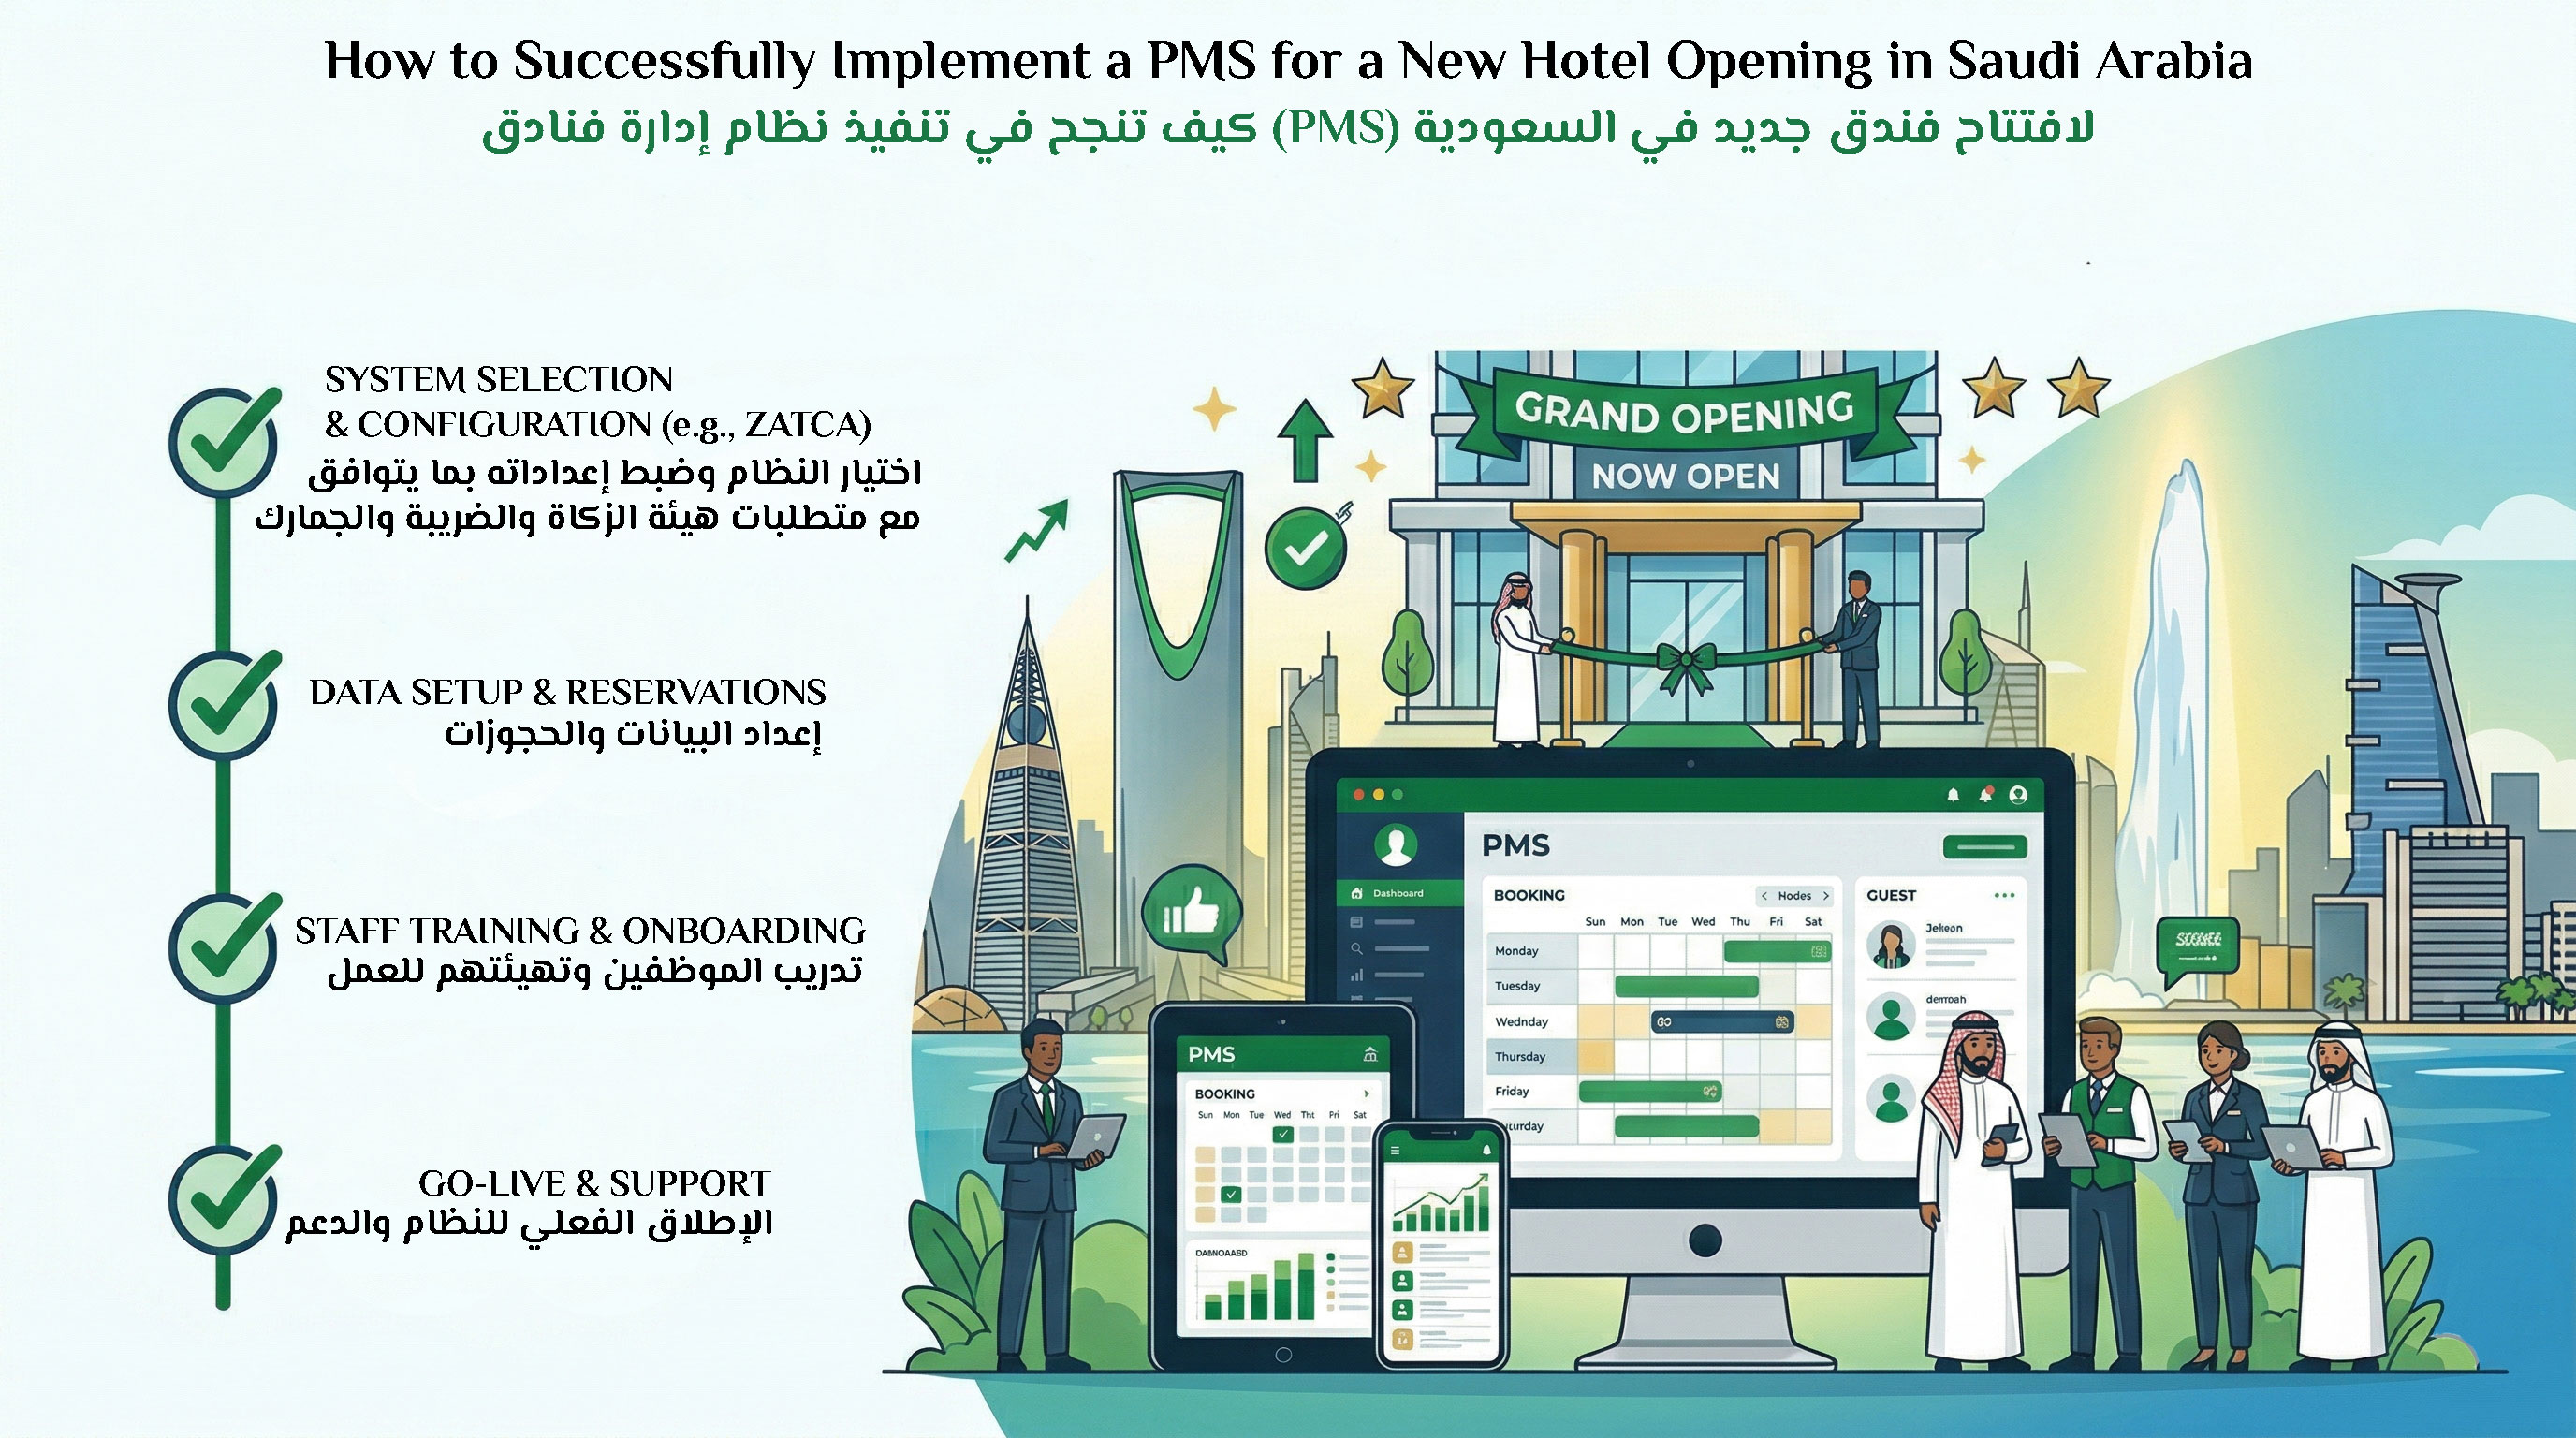
Step‑by‑step guide to implementing a PMS for a new hotel opening in Saudi Arabia. Covering ZATCA, Shomoos, check‑in automation, and best practices for a successful launch. Free demo from Fandaqa...

Discover why a local PMS vendor in Riyadh or Jeddah is the smart choice for your hotel. Faster support, ZATCA & Shomoos compliance, Arabic interface, and data residency. Free demo from Fandaqah...
Discover the best PMS for serviced apartments in Saudi Arabia. Automate check-in, manage multiple units, ensure ZATCA & Shomoos compliance, and boost revenue. Free demo for property managers...
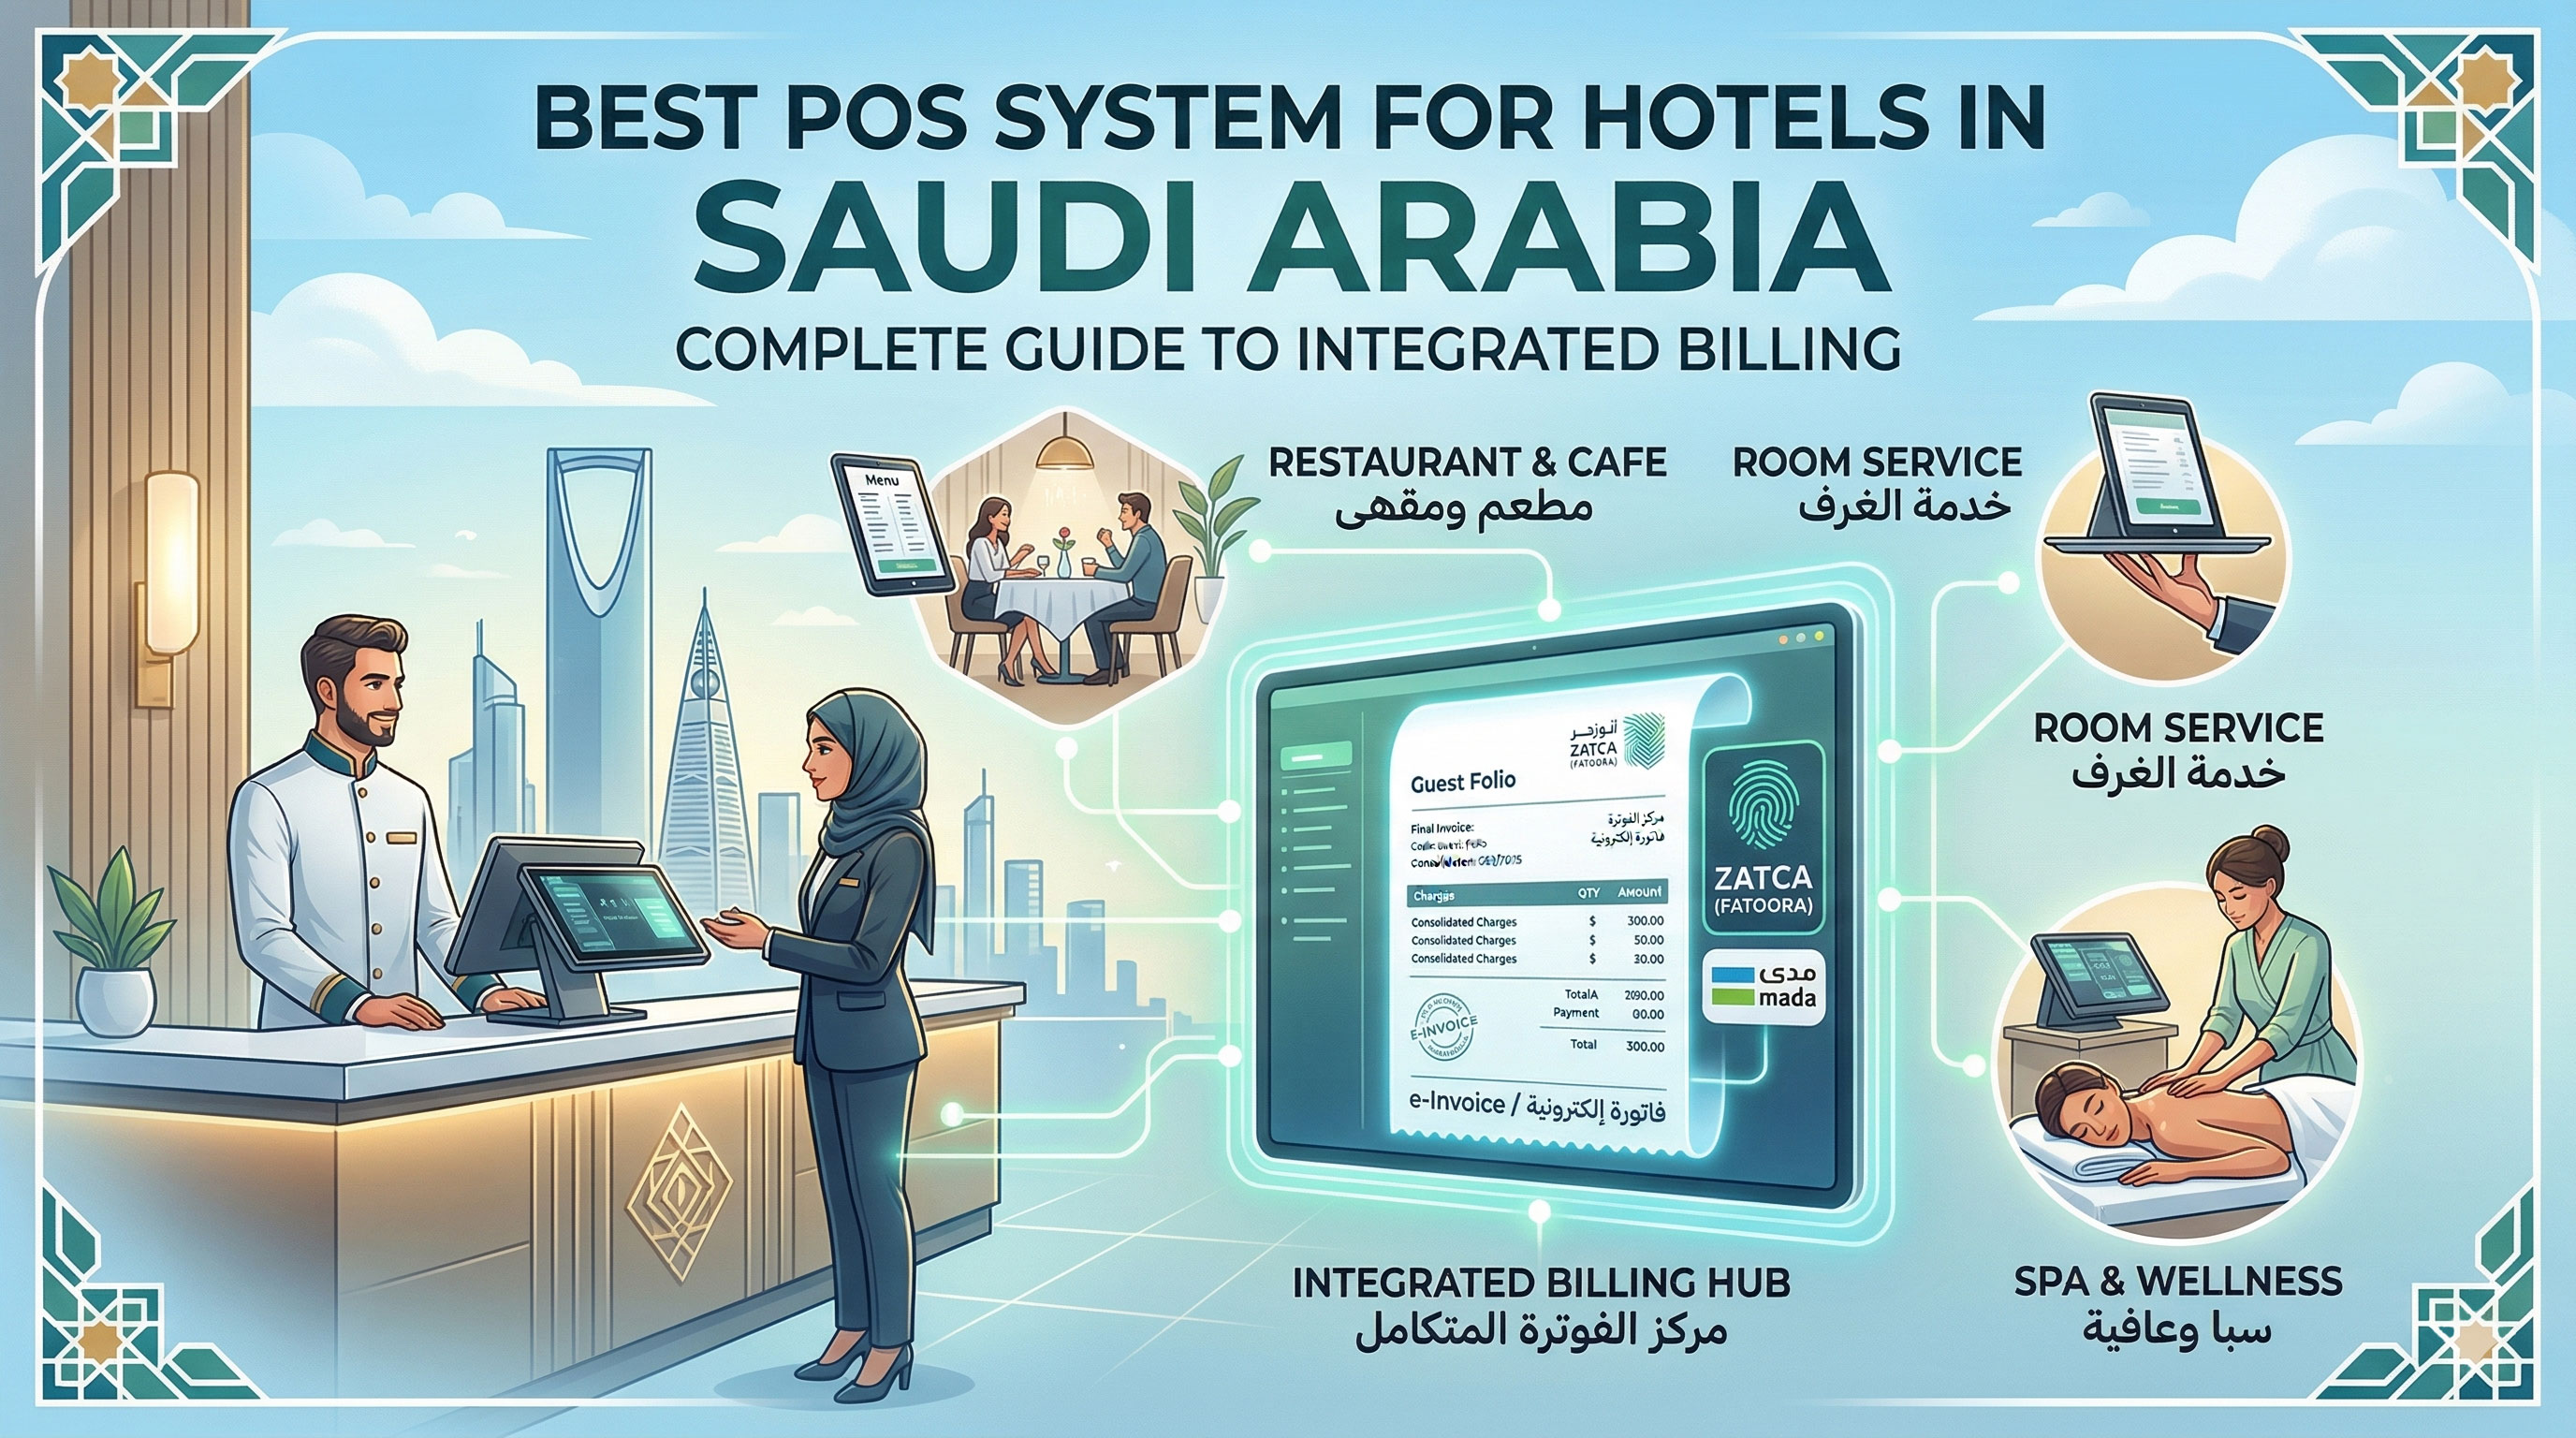
Discover the best POS system for hotels in Saudi Arabia. Integrate F&B, spa, and retail billing with your hotel PMS. ZATCA compliant, Shomoos ready. Free demo for hoteliers...
Fandaqah is Saudi Arabia's leading hotel management software. ZATCA, Shomoos & Ministry of Tourism compliant. PMS, booking engine & channel manager in one platform....
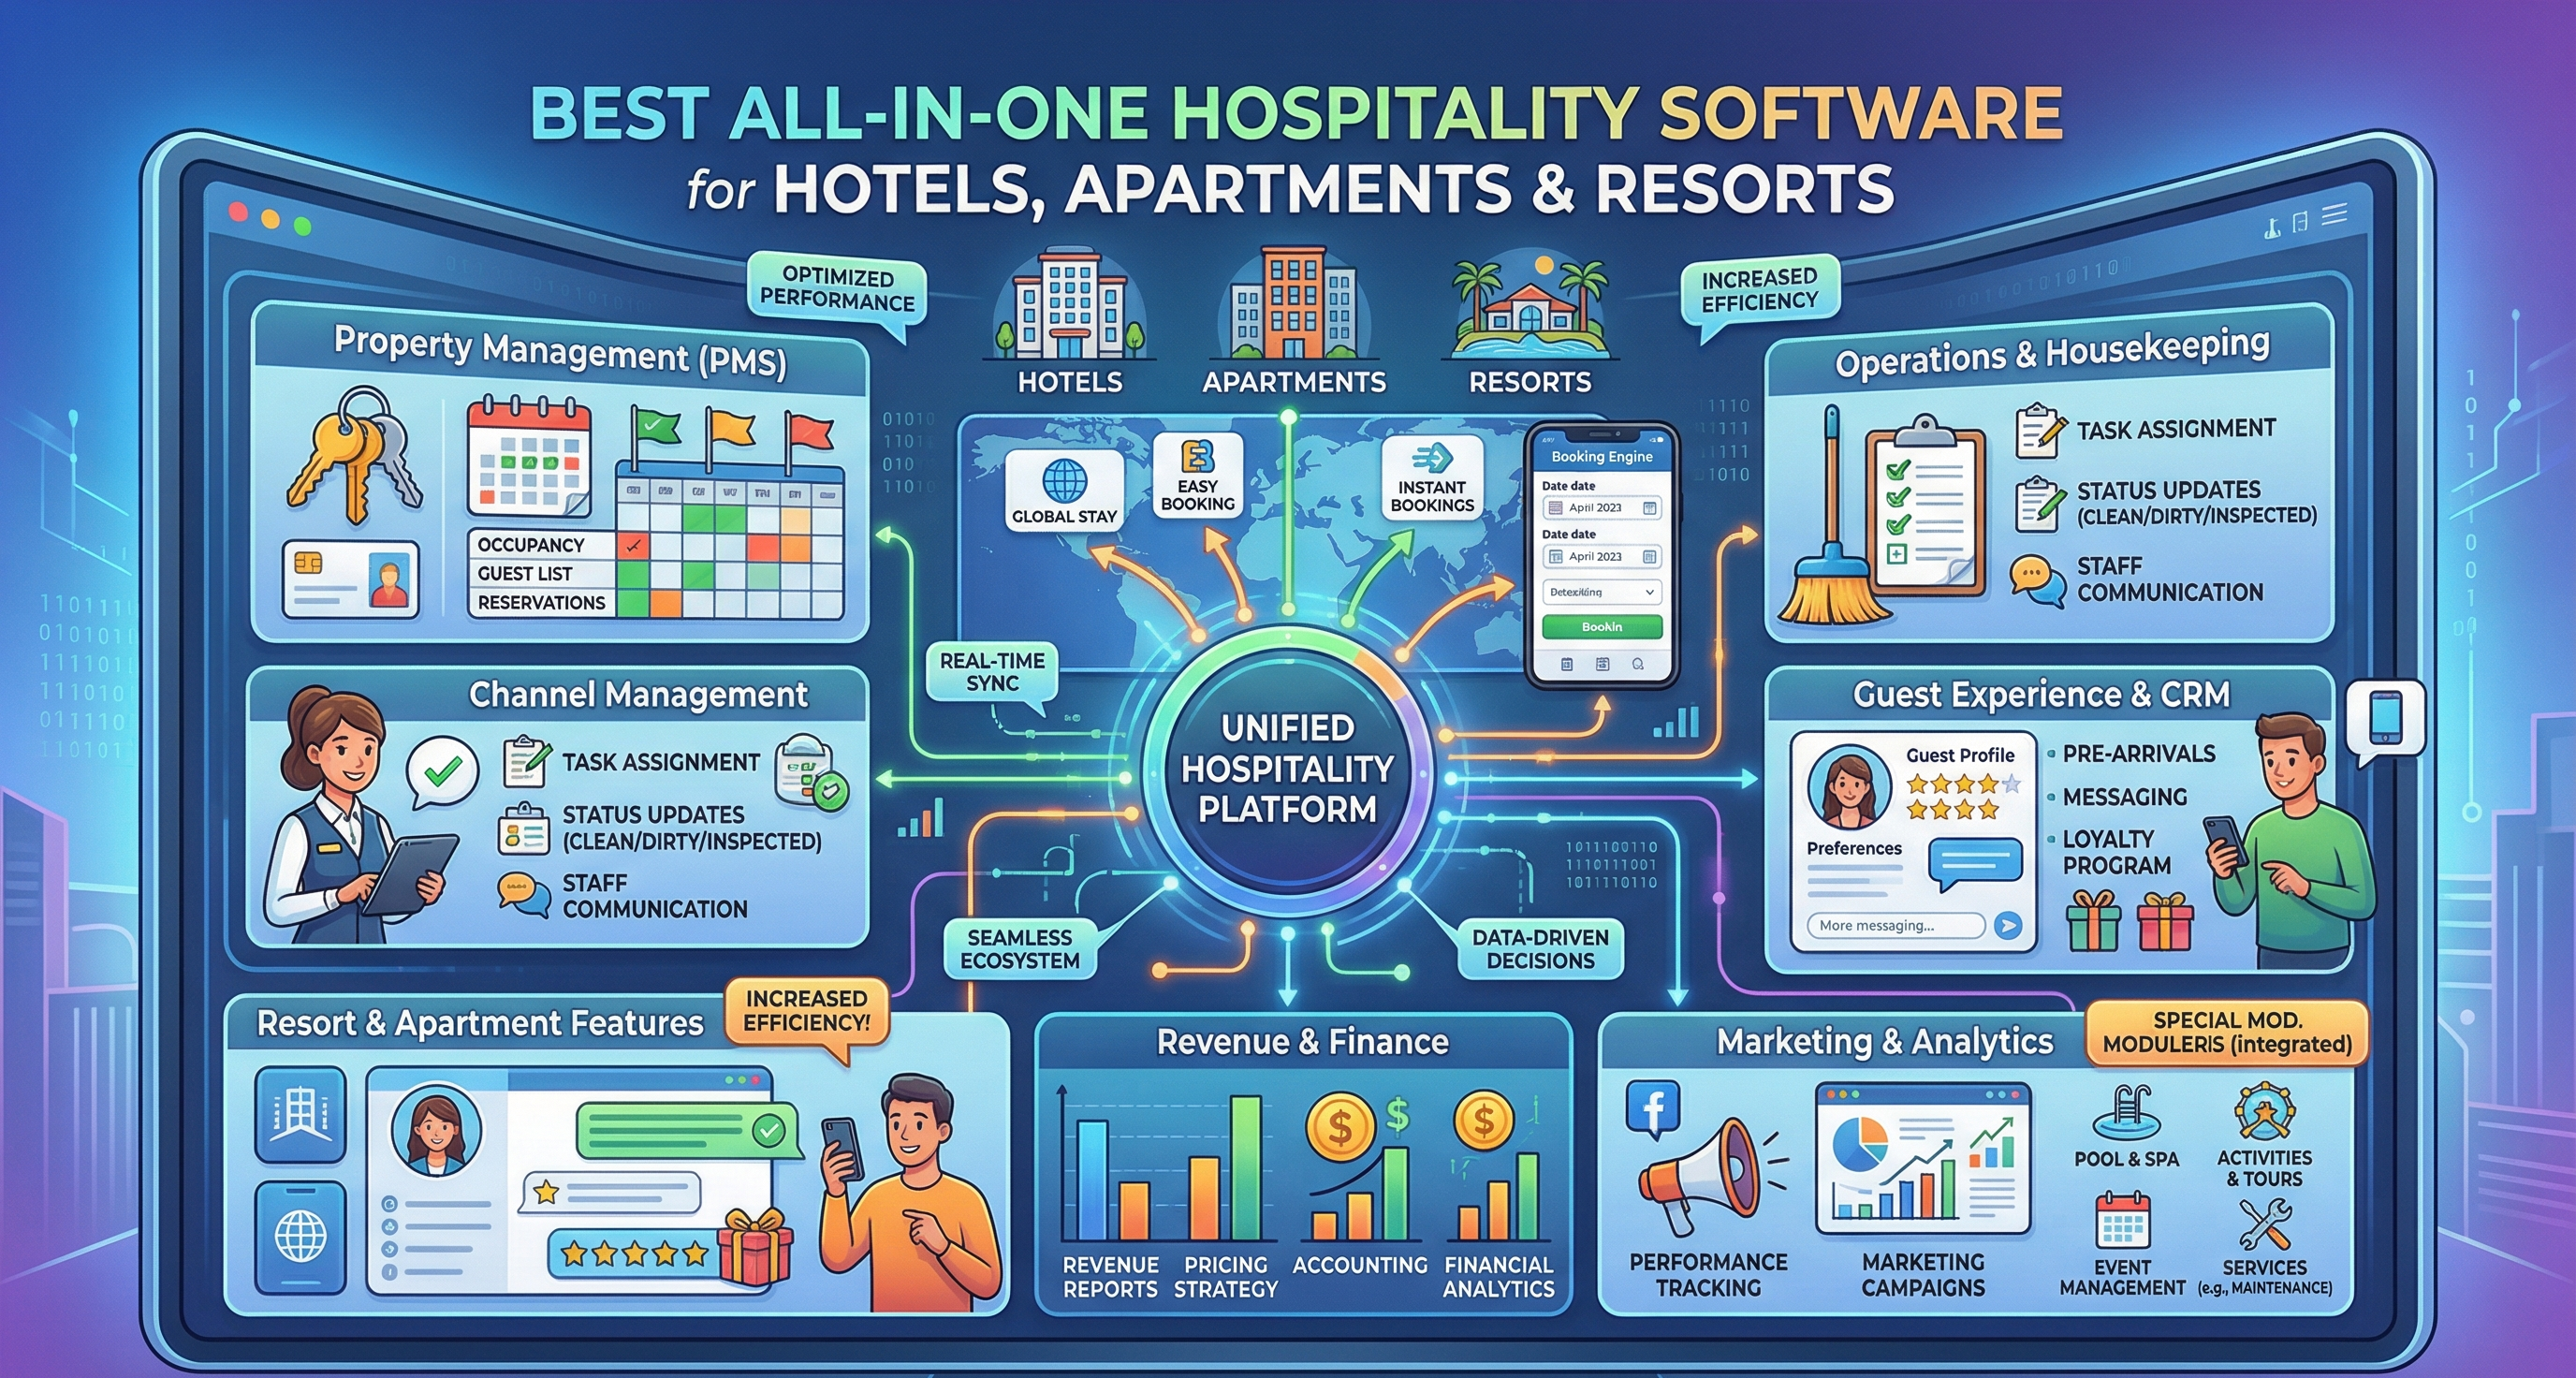
Discover Fandaqah trusted property management software for hotels, apartments & resorts. ZATCA, Shomoos & Tourism compliant. Request your free trial today!...
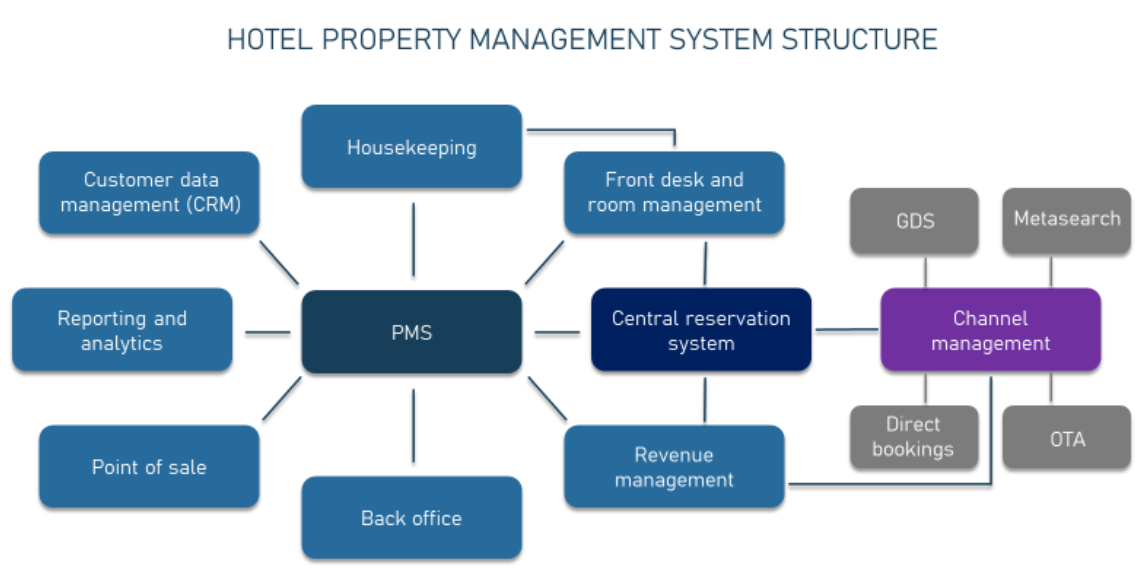
Fandaqah PMS automates hotel check‑in, ensures ZATCA Phase 2 e‑invoicing & Shomoos integration. 85% faster, trusted by 850+ Saudi properties. Start your free trial....
Automate hotel check-in Saudi Arabia with passport scanning. ZATCA compliant, Shomoos integrated. Reduce waiting time 70%. Free demo!...
Join Fandaqah's partner program for hotel management software Saudi Arabia. Earn 200 SAR per referral, ZATCA compliant. 800+ hotels trusted!...
Complete guide to analyzing guest feedback and improving hotel performance in Saudi Arabia. Learn about KPIs, technology, ZATCA & Shomoos compliance, and strategies to increase revenue and guest satis...
Discover how Fandaqah Channel Manager helps Saudi hotels manage and streamline rates across all OTA platforms. Increase direct bookings, automate distribution, ensure ZATCA & Shomoos compliance, and b...
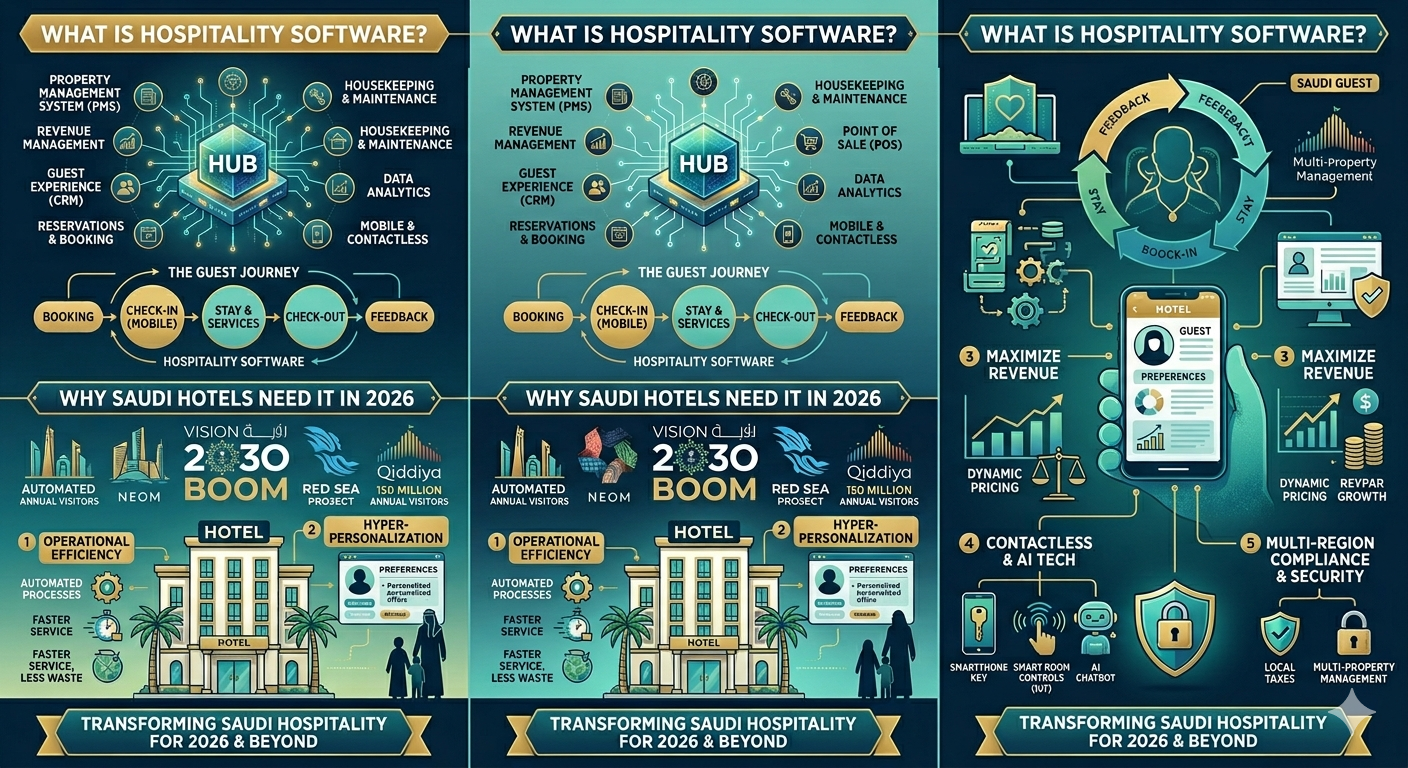
Discover what hospitality software is and why Saudi hotels need it in 2026. Complete guide to hotel management systems, check-in automation, ZATCA & Shomoos compliance, and guaranteed ROI. Fandaqah so...
Complete guide to OTA channel manager for hotel distribution in Saudi Arabia. Learn how to increase bookings, automate distribution, comply with ZATCA & Shomoos, and boost revenue. Fandaqah solutions....

Complete hotel audit guide for 2026: learn about night audit procedures, financial reports, compliance with ZATCA & Shomoos, and how automated audits improve accuracy and efficiency for Saudi hotels....
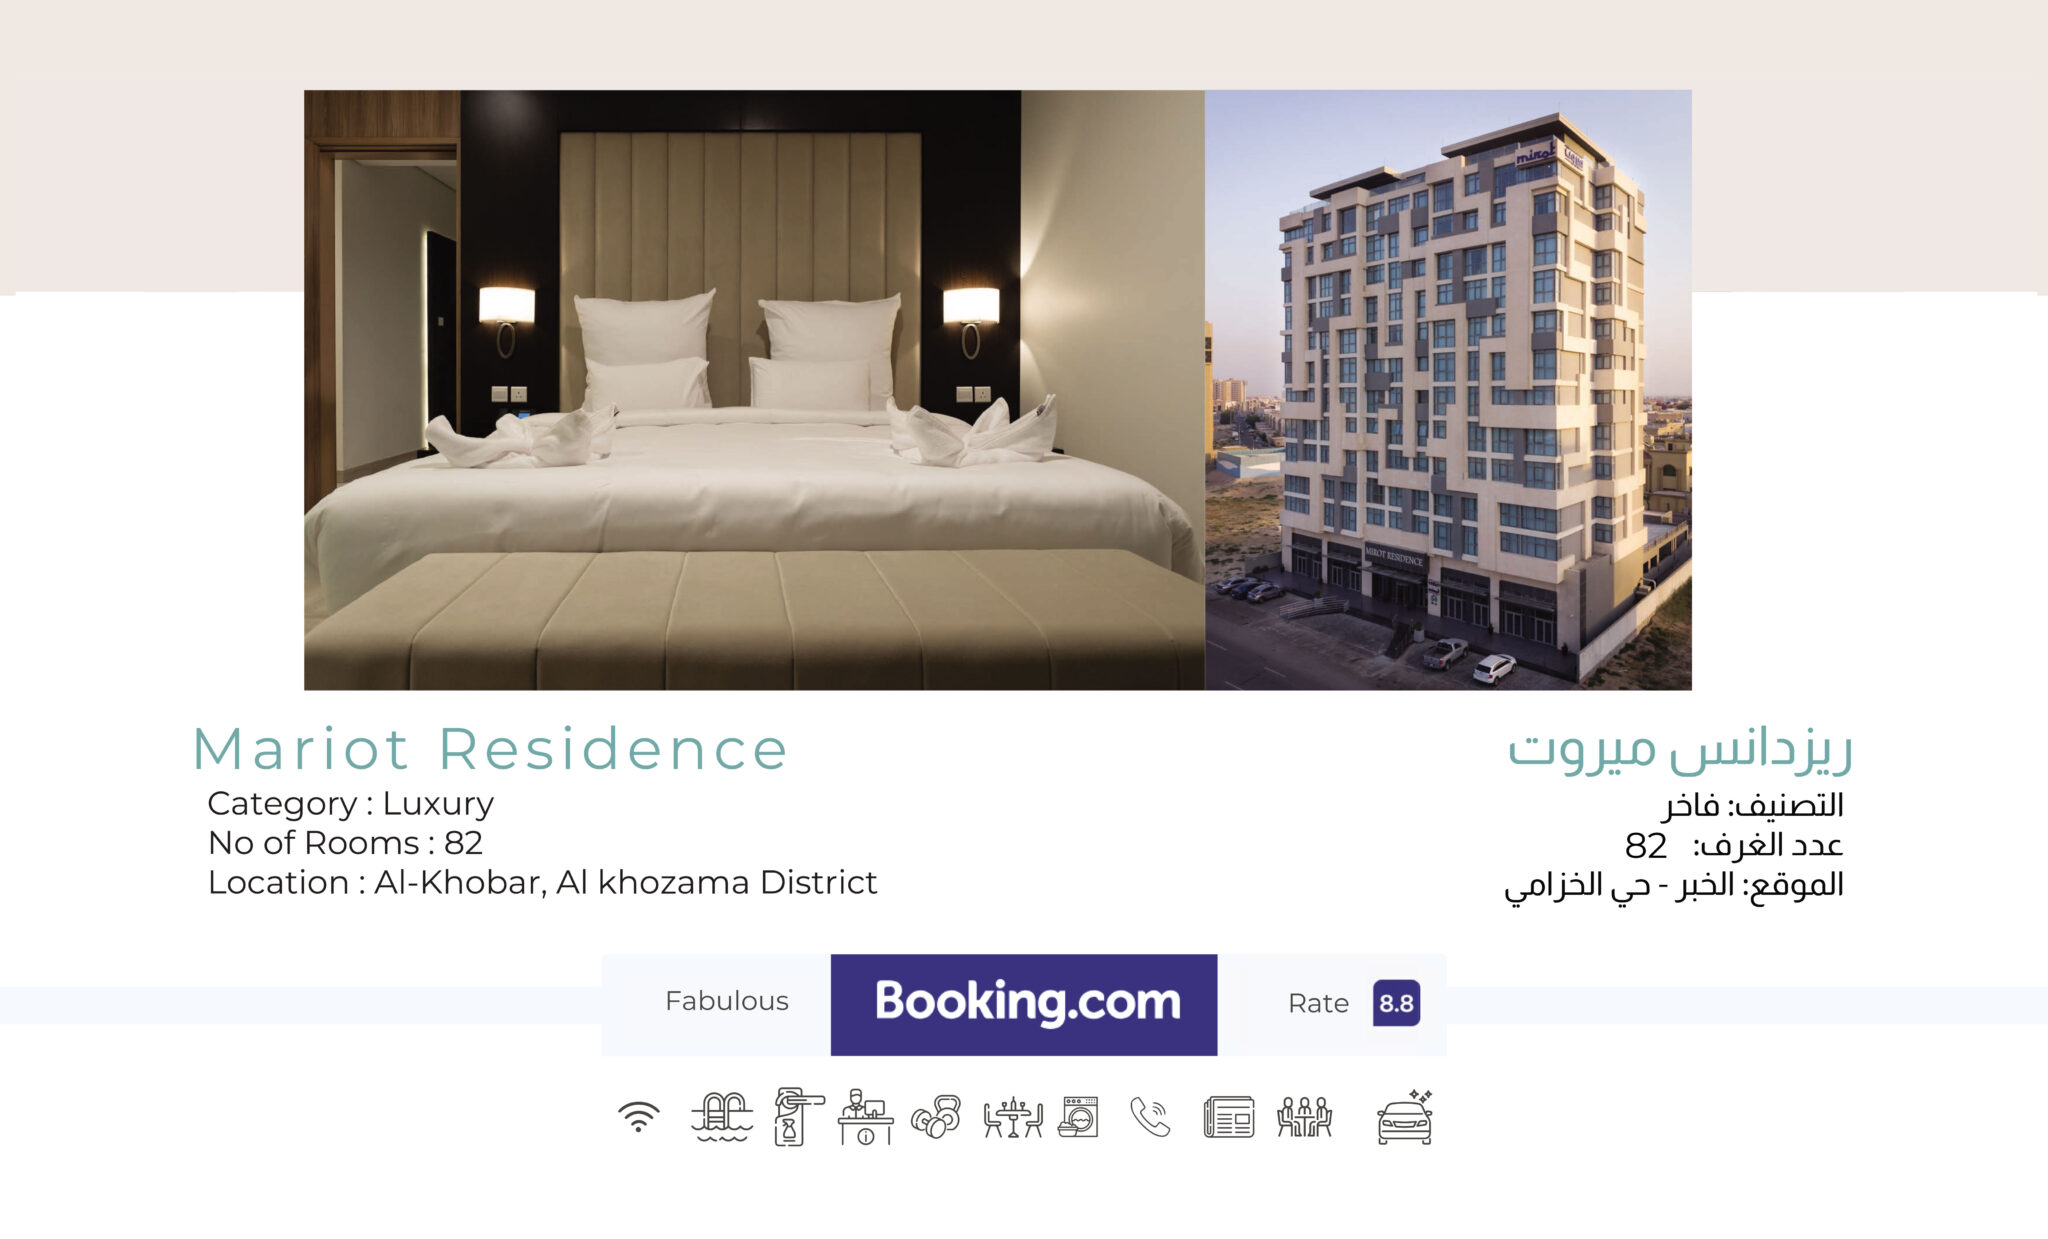
Mariot Residence began as a modest 1-star property with: Limited digital infrastructure Manual operations Basic amenities Difficulty attracting guests and maintaining service quality...

In the hospitality industry, room pricing isn’t just a number on a screen—it’s a strategic decision that directly impacts revenue, occupancy, and guest satisfaction....
In hospitality, every moment matters. From the first greeting at the front desk to the final checkout, hotels strive to offer a seamless and comfortable experience for every guest. Yet, one aspect oft...
The complete guide to the Saudi Future Hospitality Summit 2026: dates, venue, speakers, investment opportunities, technology, and ZATCA & Shomoos compliance. Join 1,500+ industry leaders in Riyadh....
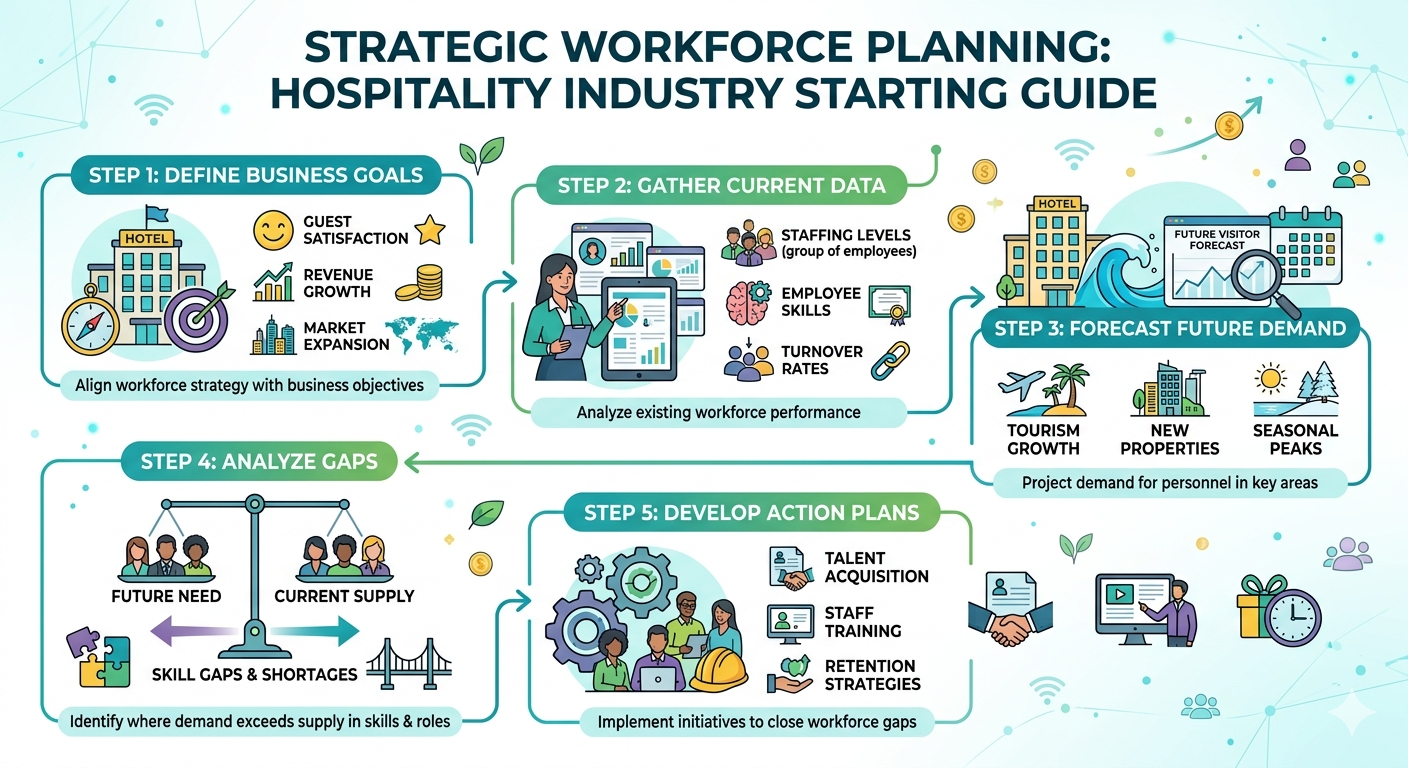
Master strategic workforce planning for Saudi hospitality. Achieve Nitaqat compliance, reduce turnover, and build Vision 2030-ready teams with expert strategies...
In line with Saudi Vision 2030, the tourism sector is undergoing an unprecedented digital transformation. One of the most impactful tools driving this change is the National Tourism Monitoring Platfor...
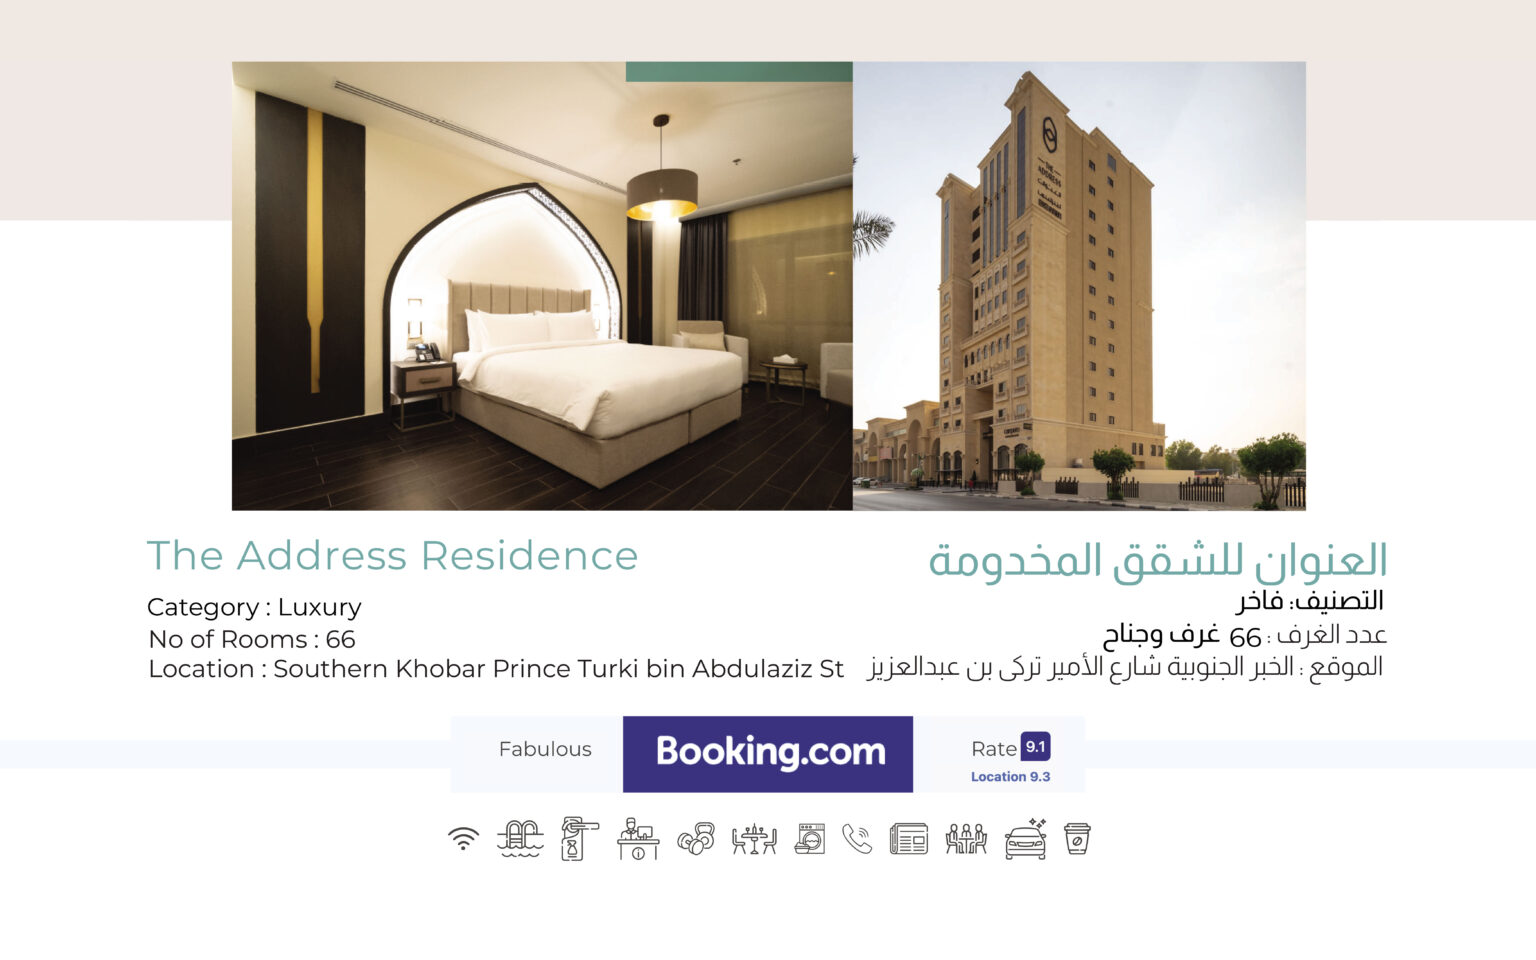
The management adopted Fandaqah PMS, a Saudi-built property management system designed for operational efficiency and government compliance. The result? A complete transformation across operations, gu...
In today’s hospitality landscape, competition is no longer just about location or star ratings. Success now hinges on how effectively a hotel leverages smart technologies to streamline operations an...